Symple Lending Lawsuit in 2026: What’s Filed, What’s Settled, and What Borrowers Should Know
Quick Answer
- A Symple Lending lawsuit, as a formal court case, does not appear in verified court records as of September 2026.
- Consumer complaints about the lender exist with the CFPB and state regulators, but no class action has been certified.
- No settlement fund, claim deadline, or consumer payout exists for any Symple Lending case.
If you searched for “Symple Lending lawsuit,” you likely took out a loan with the company, had a problem with the terms, or heard something about legal trouble.
This article gives you the verified status as of September 9, 2026. It explains what Symple Lending is, what complaints exist, and whether any lawsuit or settlement is real.
Here’s the part most articles skip: complaints to a government agency are not lawsuits. A company can have hundreds of consumer complaints without ever being sued in a way that produces a settlement or payout.
The Facts
| Item | Detail |
|---|---|
| Official Case Name | Not found in verified court records |
| Court / Jurisdiction | Not confirmed |
| Current Status | Consumer complaints and regulatory scrutiny only |
| Total Settlement Fund | Not applicable |
| Est. Per Person | Not applicable |
| Claim Deadline | Not applicable |
| Administrator | Not applicable |
| Proof Needed | Not applicable |
Is the Symple Lending Lawsuit Real?
No verified lawsuit naming Symple Lending as a defendant exists in public court records as of September 9, 2026.
What does exist: consumer complaints filed with the Consumer Financial Protection Bureau and state regulators. These complaints allege various lending practices, but complaints are not lawsuits.
A complaint to the CFPB is a consumer report. The agency reviews complaints and may investigate patterns. But most complaints never become enforcement actions or lawsuits.
The distinction matters because people searching for a “lawsuit” often expect a settlement or payout. That doesn’t exist here.
Key Takeaway: Symple Lending has faced consumer complaints, but no verified lawsuit or settlement exists as of September 9, 2026.
What Is Symple Lending?
Symple Lending is a financial services company that offers personal loans, often marketed to consumers with less-than-perfect credit.
The company’s lending model focuses on debt consolidation and personal installment loans. It markets convenience and fast approval, which appeals to borrowers who need money quickly.
Symple Lending operates online and through direct mail offers. It’s not a traditional bank. It’s a nonbank lender, which means it faces different regulatory requirements than banks.
The nonbank lending space has been a focus of CFPB scrutiny in recent years, and Symple Lending is part of that broader regulatory environment.
What Complaints Have Been Filed Against Symple Lending?
Consumer complaints against Symple Lending, as reflected in CFPB complaint data, fall into several categories.
| Complaint Type | Description |
|---|---|
| High interest rates | Borrowers report rates higher than expected |
| Hidden fees | Origination fees and other charges not clearly disclosed |
| Customer service | Difficulty reaching representatives or resolving issues |
| Payment processing | Problems with autopay and payment allocation |
| Collections practices | Aggressive collection tactics reported by some borrowers |
These complaints are similar to those filed against many nonbank lenders. They don’t necessarily indicate illegal conduct. They indicate consumer dissatisfaction.
The CFPB publishes complaint data but doesn’t verify individual complaints. A complaint is an allegation, not a finding.
Has the CFPB Taken Action Against Symple Lending?
No verified CFPB enforcement action against Symple Lending exists as of September 9, 2026.
The CFPB has been active in the nonbank lending space, bringing enforcement actions against various lenders for deceptive practices. But no such action naming Symple Lending specifically has been verified.
The absence of an enforcement action doesn’t mean the CFPB has cleared the company. It simply means no public enforcement action exists.
State regulators may have their own investigations or actions, but none are verified in public records as of the date of this article.
Reality Check: No legitimate organization contacts you about a Symple Lending settlement. No one charges a fee to “process” a refund from a lender. If someone asks for money to help you get money from a lawsuit that doesn’t exist, it’s a scam.
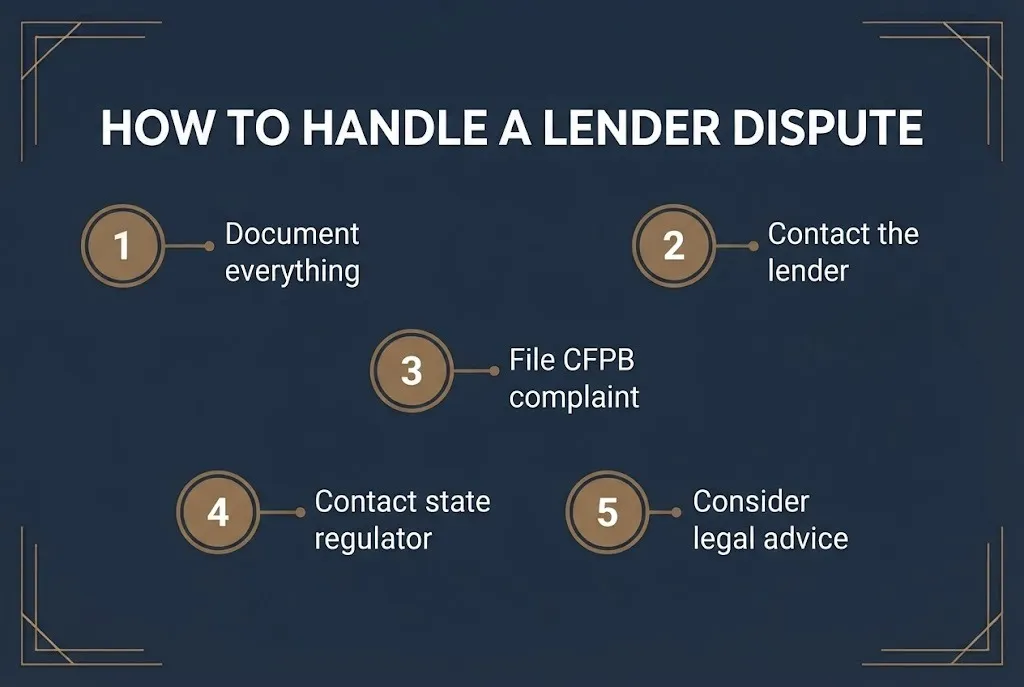
What Should You Do If You Have a Problem With Symple Lending?
You have options even without a lawsuit.
- Contact Symple Lending directly to try to resolve the issue.
- Document everything: loan terms, payment history, correspondence.
- File a complaint with the CFPB through its complaint portal.
- File a complaint with your state’s attorney general or financial regulator.
- Consider a complaint with the Better Business Bureau.
- Consult a consumer protection attorney if you believe your rights were violated.
- Explore your state’s unfair lending laws and remedies.
The CFPB complaint process is free and can sometimes produce results. The agency forwards complaints to the company and tracks responses.
If a pattern of complaints emerges, the CFPB may investigate. But individual complaints rarely produce individual remedies on their own.
Can You Sue Symple Lending Yourself?
Yes, if you have a valid legal claim and the statute of limitations hasn’t expired.
Individual borrowers can sue lenders for violations of lending laws. Common claims include:
- Truth in Lending Act violations for disclosure failures
- State usury law violations for excessive interest
- Deceptive trade practices under state law
- Breach of contract for failing to honor loan terms
The viability of a claim depends on your specific facts and your state’s laws. A consumer protection attorney can evaluate whether you have a case.
Small claims court is an option for smaller disputes, though the amount limits vary by state.
What Are the Signs of a Predatory Lender?
Predatory lending practices are illegal, but they’re not always obvious.
| Warning Sign | What It Means |
|---|---|
| Pressure to sign quickly | Legitimate lenders give you time to review terms |
| Unclear interest rates | APR should be disclosed in writing before you sign |
| Fees before funding | Legitimate lenders don’t charge upfront fees |
| Balloon payments | Large final payments can trap borrowers |
| No credit check promised | Often a sign of hidden costs |
If you experienced these practices with Symple Lending or any lender, you may have a legal claim. Document what happened and consult an attorney.
Key Takeaway: A lawsuit doesn’t exist against Symple Lending yet, but individual borrowers can still pursue their own claims if they’ve been harmed.
What Is the Statute of Limitations for Suing a Lender?
The deadline depends on your claim type and your state’s laws.
Federal Truth in Lending Act claims generally have a one-year statute of limitations from the loan date for disclosure violations. Other claims under state law may have longer windows.
State consumer protection laws typically allow two to six years, depending on the state and the specific claim.
The clock starts when the violation occurred or when you discovered it, depending on the state’s discovery rule.
If you’re considering legal action against any lender, the time to act is now. Waiting risks losing the claim.
What Happens Next With Symple Lending?
The company’s regulatory future depends on whether complaints lead to enforcement action.
- Ongoing: CFPB complaint data continues to accumulate.
- Possible investigation: If complaints show a pattern, the CFPB or state regulators may act.
- Possible enforcement: A future enforcement action could produce refunds for affected borrowers.
- No guarantee: Most complaints never lead to enforcement.
For borrowers, the practical next step is resolving individual issues through the complaint process or legal action. Don’t wait for a class action or settlement that may never come.
Frequently Asked Questions
Is there a Symple Lending class action lawsuit?
No verified class action exists.
No class has been certified.
No settlement has been approved.
Can I get a refund from Symple Lending?
Possibly, if you have a valid claim.
Contact the company first, then file a CFPB complaint.
Legal action may be necessary.
What is Symple Lending?
A nonbank personal loan company.
Offers debt consolidation and installment loans.
Markets to consumers with various credit profiles.
Has Symple Lending been sued?
No verified lawsuit exists in public records.
Consumer complaints exist but are not lawsuits.
No enforcement action is confirmed.
How do I file a complaint about Symple Lending?
File with the CFPB online.
Contact your state attorney general.
Document everything first.
Is Symple Lending a legitimate company?
Yes, it’s a real lending company.
Legitimacy doesn’t mean all practices are legal.
Borrowers should review loan terms carefully.
What should I do if Symple Lending overcharged me?
Contact the company in writing.
File a CFPB complaint.
Consider legal action if unresolved.
Can I sue a lender for high interest rates?
Possibly, if the rate violates state usury laws.
Consult a consumer protection attorney.
The statute of limitations applies.
If you searched for a Symple Lending lawsuit expecting a settlement, the verified answer is that no such lawsuit exists. But if you’ve had a problem with the lender, your individual options are real. File a complaint, document everything, and consider legal advice.
The most important fact: no lawsuit means no settlement, but your individual claim may still be valid, and the clock is running.