Wisconsin Deferred Compensation in 2026: What the WDC 457(b) Program Actually Is, and When It Becomes a Lawsuit
Quick Answer
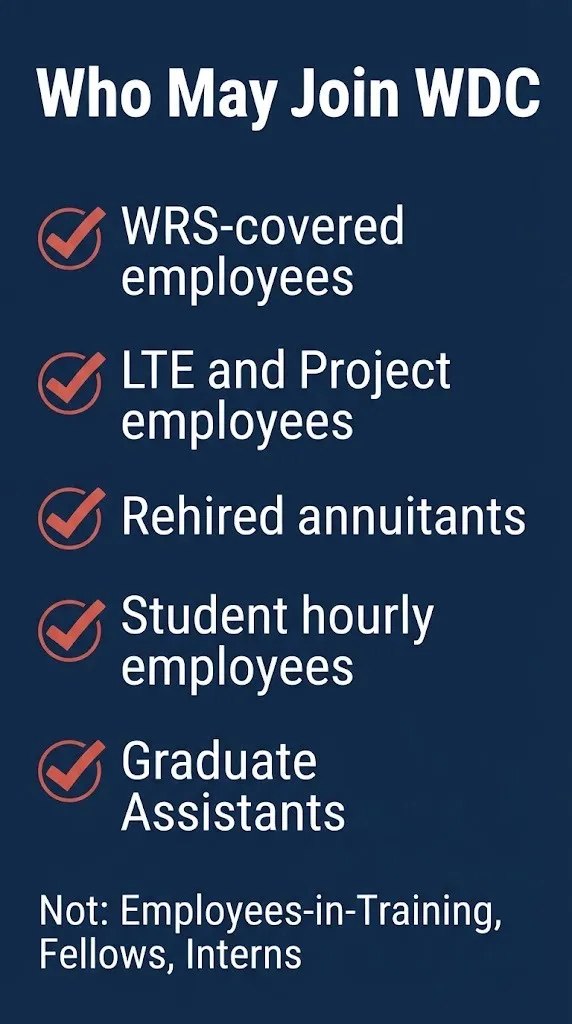
- The Wisconsin Deferred Compensation Program (WDC) is a voluntary 457(b) retirement savings plan for state and local public employees, not a lawsuit or settlement.
- There is no WDC settlement payout, and no claim deadline exists, because the program itself has not been sued or settled.
- The one active deferred compensation lawsuit in Wisconsin right now is a private dispute between a former CEO and his employer, not the state WDC plan.
The phrase “Wisconsin deferred compensation” pulls up two very different things in 2026, and mixing them up can cost you money. One is a boring, legitimate government retirement plan that nearly every public worker in the state can join. The other is a private legal fight that has nothing to do with that plan.
If you got here because you typed “wisconsin deferred compensation” and expected a claim form, there isn’t one for the state program. But there are real things happening in 2026 that you should know about, including a rule update, a federal lawsuit involving a former CEO, and an $850,000 retirement plan settlement involving a different Wisconsin employer. This article separates all of it, source by source.
The Facts
| Item | Detail |
|---|---|
| Program Name | Wisconsin Deferred Compensation (WDC) 457(b) Program |
| Status | Active state retirement plan, not a settlement |
| Who Runs It | Wisconsin Department of Employee Trust Funds (ETF) |
| Recordkeeper | Empower Retirement |
| Active WDC Lawsuit | None against the state plan |
| Related 2026 Lawsuit | Shekoski v. Primex, Inc., et al., E.D. Wis. Case No. 2:26-cv-1183 |
| Related 2026 Settlement | Quad/Graphics $850,000 retirement plan settlement, fairness hearing Feb. 18, 2026 |
| Rule Update Status | Statement of Scope SS 005-26, comments closed March 20, 2026 |
| Settlement Deadline | Not applicable, no WDC settlement exists |
Is the Wisconsin Deferred Compensation Program Legit or a Scam?
It is legit. The WDC program is a government-administered 457(b) plan created under Wisconsin law and overseen by the Employee Trust Funds Board and the Deferred Compensation Board. There is no scam here, and no one should be paying a third party to “unlock” a WDC settlement that does not exist.
The confusion likely comes from how the phrase “deferred compensation” gets used in legal headlines. When a company gets sued over deferred compensation, it usually means an executive or employee says the employer broke a contract to pay them later. That is a private contract dispute. The state WDC plan is a statutory retirement benefit, not a contract with your employer that can be breached in the same way.
If you are a Wisconsin public employee, your WDC account is real, your contributions are yours, and you can check your balance through Empower at wdc457.org or by calling 877-457-9327. If someone calls or texts you about a “Wisconsin deferred compensation settlement payout,” that is not connected to the real program.
Key Takeaway: The Wisconsin Deferred Compensation Program is a legitimate state retirement plan, and any message promising you a WDC settlement payout is false.
How Much Can You Contribute to Wisconsin Deferred Compensation in 2026?
The 2026 contribution limits for the WDC program are $24,500 for participants age 49 and under, and $32,500 for those age 50 to 59, according to University of Wisconsin benefits documentation. Participants age 60 to 63 get a higher limit of $35,750 under the super catch-up provision.
Those limits are per person, per year. Participation is voluntary, and there is no employer match, which surprises a lot of new state employees. You contribute pre-tax, post-tax Roth, or a mix of both.
Here is the full 2026 limit table:
| Age During 2026 | Maximum Contribution |
|---|---|
| 49 and under | $24,500 |
| 50 to 59 | $32,500 |
| 60 to 63 | $35,750 |
| 64 and over | $24,500 (standard limit applies) |
There is also a Special Catch-Up provision for employees within three years of normal retirement age, which can let you contribute up to twice the basic limit if you under-contributed in prior years. You cannot use both the Special Catch-Up and the Age 50+ Catch-Up in the same calendar year.
Key Takeaway: Your 2026 WDC contribution ceiling depends on your age, and the highest limit, $35,750, applies to participants age 60 to 63.
What Is the Shekoski v. Primex Deferred Compensation Lawsuit?
It is a private breach of contract lawsuit filed July 6, 2026, by former Primex CEO Paul Shekoski in the U.S. District Court for the Eastern District of Wisconsin, Case No. 2:26-cv-1183. The case has nothing to do with the state WDC program.
Shekoski led Primex for more than twenty years and says the company agreed to pay him an equity-based deferred compensation amount when he retired for “Good Reason,” which the plan defined to include reaching age 62. He retired in January 2026 at that age.
According to the complaint, Primex refused to start the valuation process or pay him. The company then, only after his resignation, tried to reclassify his departure as a termination “for Cause,” citing expense reimbursement and confidential information allegations. Shekoski denies wrongdoing and calls those claims a pretext to avoid payment.
He is asking the court to force Primex to follow the compensation plan, pay what he says he is owed, and declare the company’s non-compete and confidentiality restrictions unenforceable under Wisconsin Statute §103.465.
Key Takeaway: The Shekoski lawsuit is a private employment contract dispute against Primex, not a class action, and it does not create any claim or payout for the general public.
Is There a Wisconsin Deferred Compensation Settlement Payout in 2026?
No, there is no Wisconsin Deferred Compensation settlement payout in 2026. The WDC program itself is not a defendant in any known settlement, and no claims administrator has been appointed to pay WDC participants.
What does exist is a separate settlement involving a different Wisconsin employer’s retirement plan. Quad/Graphics Inc. reached an $850,000 class settlement over its retirement plan’s investment options and fees. That deal received preliminary approval from Judge Pamela Pepper in the Eastern District of Wisconsin, with a fairness hearing set for February 18, 2026.
That settlement covers roughly 25,000 people who were in the Quad/Graphics retirement plan since October 2014. The recovery equals nearly 19% of the estimated losses. It is not a WDC settlement, and WDC participants are not automatically covered by it.
There is also a $980,000 final settlement for ThedaCare Inc. workers over retirement plan fees, benefiting about 18,820 people. Again, that is a private employer plan case, not the state WDC program.
Key Takeaway: If you are searching for a WDC settlement payout, it does not exist; the retirement plan settlements in Wisconsin in 2026 involve Quad/Graphics and ThedaCare, not the state 457(b) plan.
How Do You File a Claim for Wisconsin Deferred Compensation?
You do not file a claim for WDC because the program is not a settlement. What you do is enroll, manage your account, and take distributions when you separate from service.
Here is how the account actually works:
- Enroll through Empower at wdc457.org or by calling 877-457-9327.
- Set your deferral rate through Empower, and your employer processes the payroll deduction.
- Choose investments from the plan’s fund menu, which includes a Stable Value option and mutual funds.
- Track your balance online, and update your contact and beneficiary information regularly.
- Request a distribution after termination, retirement, death, or an unforeseeable emergency.
- Choose a payout form: lump sum, periodic payments, or a rollover to an IRA or another eligible plan.
The monthly administrative fee is $0 if your balance is $5,000 or less, and $3.90 per month ($46.80 annually) if your balance exceeds $5,000.
Key Takeaway: Filing a WDC “claim” means enrolling and managing your retirement account, not submitting a settlement form, because no settlement exists.
Reality Check: No one texts you settlement money first. If you get a message saying you are owed a Wisconsin deferred compensation payout and need to pay a fee or provide your Social Security number to “release” it, that is a scam. Real retirement plan settlements publish official notices and never charge you to receive your own money.
What Is the 2026 Rule Change for Wisconsin Deferred Compensation?
The Wisconsin Department of Employee Trust Funds proposed technical updates to the administrative rules for the WDC program in 2026 under Statement of Scope SS 005-26. The changes are minor and technical, not substantive overhauls.
ETF held a preliminary public hearing on March 20, 2026 to take comments on the scope statement. That comment period closed the same day. The scope statement expires under state law on August 2, 2028, if the rules are not finalized before then.
The affected rule chapter is ETF 70 in the Wisconsin Administrative Code. ETF described the intent as drafting technical updates, deleting obsolete language, and making other minor substantive changes. Nothing in the scope statement suggests changes to contribution limits, distribution rules, or investment options that would affect participants’ day-to-day accounts.
The formal rule-making process comes next. Once ETF drafts actual rule language, there will be another public comment period and legislative review before anything takes effect.
Key Takeaway: The 2026 WDC rule change is a routine technical update to ETF 70, and the public comment window closed on March 20, 2026.
When Will You Get Your Wisconsin Deferred Compensation Money?
You can access your WDC money when you separate from service, retire, die (through a beneficiary), or face an unforeseeable financial emergency. The plan does not pay out on a settlement schedule because there is no settlement.
After you terminate or retire, you elect a distribution date. You can generally wait until April 1 of the calendar year following the year you reach required minimum distribution age, or the year you terminate, whichever is later.
The distribution options are:
- Lump sum of all or part of your balance
- Periodic payments monthly, quarterly, semi-annually, or annually
- Unforeseeable emergency release for a severe financial hardship within the last 12 months
An unforeseeable emergency is not the same as wanting your money early. Regulations do not count a planned or voluntary event as an emergency. If you are thinking about a hardship withdrawal, read the plan’s Unforeseeable Financial Emergency Distribution Guide first.
You can also roll WDC dollars into an IRA, 401(k), or 403(b) if you leave public employment. The tax rules of the new plan then apply.
Key Takeaway: Your WDC money is available when you leave public service, retire, or qualify for a hardship distribution, and the timing is under your control, not a court’s.
What Happens Next
March 20, 2026: Preliminary public hearing on SS 005-26 held; comment period closed. (Completed)
Expected late 2026 or 2027: ETF drafts formal rule language for ch. ETF 70 and opens a new public comment period. (Pending)
February 18, 2026: Fairness hearing for the Quad/Graphics $850,000 retirement plan settlement. (Held)
July 6, 2026: Shekoski v. Primex complaint filed in E.D. Wis. (Filed)
Expected 2027: Further proceedings in the Shekoski case, including possible motion practice or trial scheduling. (Pending)
Frequently Asked Questions
Is the Wisconsin deferred compensation program a settlement?
No. The WDC program is an active state retirement plan, and it is not a defendant in any settlement. There is no WDC settlement fund and no claim deadline.
How much is the Wisconsin deferred compensation payout?
There is no payout because there is no settlement. Your WDC account balance depends on what you contribute and how your investments perform, not on a court award.
Is the Shekoski v. Primex lawsuit related to Wisconsin deferred compensation?
It involves a deferred compensation contract, but it is a private dispute between a former CEO and his employer. It is not related to the state WDC program and creates no claim for the public.
Can I still contribute to Wisconsin deferred compensation in 2026?
Yes. The 2026 limits are $24,500 for age 49 and under, $32,500 for age 50 to 59, and $35,750 for age 60 to 63. Enrollment is through Empower.
What is the deadline for the Wisconsin deferred compensation rule change comments?
The comment period for Statement of Scope SS 005-26 closed on March 20, 2026. A new comment period will open when ETF publishes formal rule language.
How do I check my Wisconsin deferred compensation account balance?
Log in at wdc457.org or call Empower at 877-457-9327. You can also email [email protected].
Do I need a lawyer for Wisconsin deferred compensation?
No. The WDC program is a standard retirement plan, and you do not need legal representation to enroll, contribute, or take distributions.
Is there a class action settlement for Wisconsin deferred compensation?
No WDC class action settlement exists. The 2026 Wisconsin retirement plan settlements involve Quad/Graphics and ThedaCare, which are separate private employer plans.
Closing
The single most important thing to remember: the Wisconsin Deferred Compensation Program is a retirement plan, not a settlement, and there is no money waiting for you to claim from the state. If you are a public employee, your action is to check your contribution level and beneficiary information before the year closes. If you got a message promising a WDC payout, delete it.