Is the Visa Mastercard Settlement Legit? Credit Card Settlement 2026 Update
Quick Answer
- Yes, both settlements are real court cases, not scams: one pays merchants cash, the other cuts swipe fees going forward.
- The older $5.54 billion cash fund’s claim deadline (February 4, 2025) has already passed; a second payment distribution is expected in September 2026.
- The new $38 billion deal is not a cash payout. It lowers interchange rates for five years and still needs final court approval, expected late 2026 or early 2027.
If you searched “credit card settlement” hoping for a check, you landed in the middle of two separate cases that most headlines blur together. One is an old antitrust fund still paying out claims filed years ago. The other is a brand-new deal that changes what merchants pay Visa and Mastercard going forward, with no claim form involved.
This mostly affects merchants and small business owners who accepted Visa or Mastercard payments, not individual credit card holders looking for a refund on their own statements. The one date that matters most right now is September 2026, when the second round of payments from the older case is expected to go out.
This article sorts out which settlement applies to you, what each one actually pays, and what to watch for next. One detail most coverage skips: the new $38 billion figure is a savings estimate over five years, not a fund sitting in an account waiting to be claimed.
The Facts
| Case | In re Payment Card Interchange Fee and Merchant Discount Antitrust Litigation (MDL No. 1720) |
| Court | U.S. District Court, Eastern District of New York (Brooklyn) |
| Status | Older cash fund: in distribution. Newer $38B deal: preliminary approval only |
| Fund Size | $5.54 billion (older cash fund) / $38 billion in estimated rate relief (newer deal, not cash) |
| Est. Per Merchant | Not publicly set per claimant; based on each business’s interchange fees paid, 2004 to 2019 |
| Claim Deadline | February 4, 2025 (passed, older fund only). No claim deadline applies to the newer deal |
| Administrator | Not named by court filings found in this research; check the official Payment Card Settlement website |
| Proof Needed | Records of Visa or Mastercard transactions accepted between January 1, 2004 and January 25, 2019 |
Is the Visa Mastercard Settlement Legit?
Yes. Both cases trace back to real federal court dockets in the Eastern District of New York, not a text scam.
The older case, formally called In re Payment Card Interchange Fee and Merchant Discount Antitrust Litigation, reached final approval on December 13, 2019. The U.S. Court of Appeals for the Second Circuit upheld it in March 2023.Merchants that accepted Visa or Mastercard credit or debit card payments in the United States between January 1, 2004 and January 25, 2019 may be entitled to monetary damages or other forms of relief as compensation for the overcharges.
The newer case is a revised settlement in the same long-running dispute. Judge Brian M. Cogan said he expected to ultimately grant final approval, describing the terms as “fair, reasonable, and adequate.” That is a federal judge on the record, not a marketing claim from either card network.
Neither settlement contacts merchants by unsolicited text asking for banking details upfront. If you got a message like that, treat it as a red flag, not a payout notice.
How Much Is the Credit Card Settlement Payment?
The payout amount depends entirely on which of the two settlements applies to your business, and neither one uses a flat per-person number.
Older $5.54 billion fund: Individual payouts were calculated from each merchant’s actual interchange fees paid between 2004 and 2019, based on data Visa, Mastercard, and the banks provided to the settlement administrator. There is no public flat-rate table.
Newer $38 billion deal: This figure is not a cash fund. It’s an estimate of merchant savings from lower interchange rates over five years, not money sitting in an account.
| Settlement | Cash to Merchants? | Basis for Amount |
|---|---|---|
| $5.54B (2019, in distribution) | Yes | Interchange fees actually paid, 2004 to 2019 |
| $38B (2026, preliminary approval) | No, rate relief only | 0.1 percentage point rate cut plus rate caps, over 5 years |
Key Takeaway: The $38 billion number making headlines in 2026 is a projected savings estimate, not a check you can claim.
Credit Card Lawsuit Settlement: Which Case Applies to You?
This is the single most confused point in coverage of this story, and it matters for what you should actually do next.
If you filed a claim before February 4, 2025, you’re part of the older $5.54 billion fund and your payment status depends on the distribution schedule below. If you did not file by that date, that fund’s window has closed.
The newer $38 billion deal does not require any claim form at all. It’s not a fund for cash payouts, but rather represents cumulative merchant savings on interchange rates over a five year period. If it gets final approval, the rate changes apply automatically to eligible merchant accounts.
A simple way to think about it: the older case is like a delayed tax refund you already applied for. The newer case is more like a store lowering its prices going forward, nothing to fill out.
How to Check Your Interchange Fee Settlement Payment Status
If you already filed a claim in the older $5.54 billion fund, here’s how to check where your payment stands:
- Locate your claim confirmation number from when you filed.
- Visit the official Payment Card Settlement website (paymentcardsettlement.com is the court-authorized site named in official filings).
- Look for the claims administrator’s payment status lookup tool.
- Confirm your business was included in the population covered by the June 2026 distribution motion.
- Watch for mailed notices or direct deposit confirmations tied to the September 2026 window.
- If your claim wasn’t included in this distribution, check back for updates on later rounds.
There’s no separate status check needed for the newer $38 billion deal yet. It has no individual claim numbers because no claim form has been created.
Credit Card Lawsuit Settlement Deadline: Did You Miss It?
If you never filed a claim for the older interchange fee settlement, that window has closed and there’s no current path to reopen it. The deadline was extended to February 4, 2025 for victims of overpaid credit or debit card transaction fees to file a claim to their share of the $5.54 billion settlement.
There is no deadline to track for the newer $38 billion deal because it doesn’t require a claim. It will apply automatically to covered merchant accounts if and when it receives final approval.
Reality Check: No legitimate settlement administrator asks you to pay upfront to “unlock” a payment, and no one calls or texts asking for your bank login to release funds. If you already have a confirmed claim and don’t want to wait for distribution, some third-party firms buy claims outright, but that’s a separate, optional transaction, not a requirement to get paid.
Payment Card Interchange Fee Settlement: Second Distribution Explained
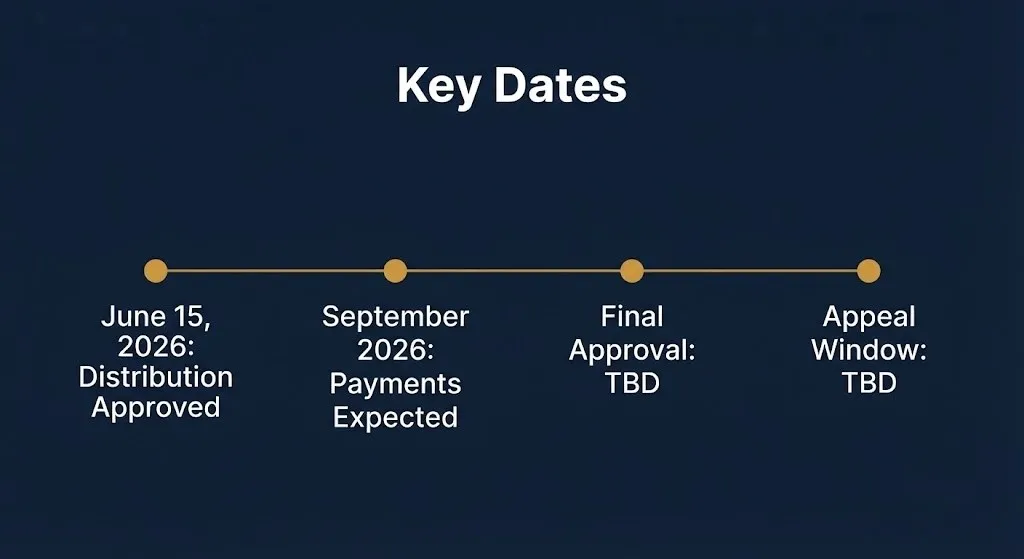
A second round of payments from the older $5.54 billion fund is now confirmed and moving forward. On May 26, 2026, Class Counsel filed a motion requesting Court approval of a second initial distribution of settlement funds. On June 15, 2026, the Court approved the motion, finding that the proposed distribution is in the best interests of eligible claimants while protecting those whose claims are not yet ready for distribution.
The second initial distribution is anticipated to occur in September 2026. Not every claimant is included in this round.
| Milestone | Date |
|---|---|
| Court approved second distribution motion | June 15, 2026 |
| Expected payment window | September 2026 |
| Eligible population | Limited to claimants named in Class Counsel’s motion |
| Claimants not yet ready | Held for a future distribution round |
Not sure if your claim is in this batch. Check the official settlement website’s distribution notice for the exact list of criteria used, since general news coverage doesn’t break down individual eligibility.
Visa and Mastercard Settlement: What Changed in the New $38 Billion Deal
The newer deal replaces a prior version that a judge rejected as inadequate. A US judge on Tuesday rejected a $30 billion antitrust settlement in which Visa and Mastercard agreed to limit fees they charge merchants who accept their credit and debit cards. Judge Margo Brodie in Brooklyn said she was not likely to grant final approval to the settlement. That rejection happened in June 2024.
The revised version raises the value and adds new merchant rights. Under the agreement announced last November, Visa and Mastercard agreed to lower swipe fees by 0.1 percentage point for five years and cap standard consumer card rates. The rate cap sits at no more than 1.25% for eight years.
The settlement also grants merchants the right to decline entire categories of cards, including commercial cards, premium consumer cards with rewards, and standard consumer cards, and provides more flexibility to impose surcharges on customers.
Key Takeaway: The new deal changes merchant rights and fee rates going forward. It does not send anyone a check.
Who Qualifies for the Interchange Fee Settlement
Eligibility splits cleanly along the same line as the payout question, so check which case fits your business first.
For the older $5.54 billion cash fund, eligibility covers businesses that accepted Visa or Mastercard credit or debit cards in the U.S. between January 1, 2004 and January 25, 2019. That window is fixed and closed to new claims.
For the newer $38 billion deal, the class is broader and more current. The settlement covers more than 12 million merchants. Coverage applies to businesses currently accepting Visa or Mastercard, not a historical date range.
- Older fund: merchants active 2004 to 2019, claims already closed
- Newer deal: roughly 12 million current merchants, no action needed if approved
- Neither settlement covers individual cardholders disputing their own statements
- Payment facilitators’ merchant-customers, not the facilitator itself, are typically the eligible class members
Mastercard Visa Settlement Lawsuit: How We Got Here
This fight has run for more than two decades, so a short timeline helps make sense of where things stand now.
The underlying lawsuit began in 2005, when merchants accused Visa, Mastercard, and partner banks of conspiring to fix interchange fees. The settlement resolves litigation that began in 2005, when merchants accused Visa, Mastercard, and banks of conspiring to violate antitrust laws through the collection of interchange fees, the charges retailers pay each time a customer swipes a credit or debit card.
An earlier $7.25 billion settlement attempt was thrown out by the Second Circuit for treating different merchant groups unfairly. The case was renegotiated into the $5.54 billion fund that reached final approval in 2019. A separate push for a fresh, larger settlement covering ongoing rate relief led to the rejected $30 billion offer in 2024, then the revised $38 billion deal approved on a preliminary basis in June 2026.
Key Takeaway: Two decades, at least three major settlement versions, and two very different kinds of relief now sitting side by side.
Settlement Payments: When Will Checks Mail in 2026
For the older cash fund, the next confirmed payment window is September 2026, tied to the court-approved second distribution. Not every claimant receives a check in this round.
For the newer $38 billion deal, there are no checks to mail because it isn’t a cash settlement. Merchants would see the benefit through lower processing rates on future transactions, not a lump sum.
| Fund | Payment Type | Next Confirmed Date |
|---|---|---|
| $5.54B older settlement | Direct payment or deposit | September 2026 |
| $38B newer settlement | Ongoing rate reduction | Applies after final approval, no fixed date confirmed |
If your business filed a claim years ago and never got paid, September 2026 is the date to watch, not a scam text claiming an earlier payout.
What the New Credit Settlement Means for Cardholders
Individual cardholders aren’t part of the class in either settlement, but the rate changes could still touch your wallet indirectly. Lower interchange costs sometimes translate into lower prices at checkout, though that isn’t guaranteed.
According to data from the Merchants Payments Coalition, the average swipe fee was 2.36% last year, and total fees increased year over year. Swipe fees totaled $118.8 billion for Visa and Mastercard in the United States in 2025, up from $111.2 billion in 2024 and $25.6 billion in 2009.
The new deal also lets merchants decline certain premium or rewards cards, similar to how a store might stop accepting a warranty from a defunct retailer. That could mean some cardholders find their rewards cards refused at more checkout counters if merchants use the new opt-out rights.
Objections and Appeals: Could This Credit Card Lawsuit Settlement Fall Apart
Preliminary approval isn’t the finish line, and several large players are already pushing back. Merchant lobbyists were crying foul over the latest attempt to end a two decade legal fight, and analysts predicted an appeal.
Separate statements from the National Retail Federation and the National Association of Convenience Stores characterized the credit card market as “broken” and said the revised terms do nothing to fix it. Objectors, including Walmart, argued that merchants would still pay too much to accept rewards cards.
NACS said it will appeal to the Second Circuit U.S. Court of Appeals if Cogan grants final approval. Keefe, Bruyette & Woods predicts a final approval and decision late in 2026 or early 2027, with a formal objection period for merchants and a follow-up hearing, and a lengthy appeal process could push final implementation to 2029.
Key Takeaway: Final approval is not guaranteed on any timeline yet, and an appeal could delay real-world changes for years.
What Happens Next
September 2026: Expected payment window for the second distribution of the older $5.54 billion cash fund.
Late 2026 or early 2027 (expected): Projected timeframe for final approval consideration of the newer $38 billion deal, per analyst estimates.
Following final approval (if granted): A formal objection and comment period for the class, then a final approval hearing.
After final approval (if granted): Likely appeal to the Second Circuit U.S. Court of Appeals from groups including NACS, which could stretch resolution toward 2029.
Ongoing: Additional distribution rounds for claimants not included in the September 2026 payment from the older fund.
Frequently Asked Questions
Is there still time to file a claim in the Visa Mastercard settlement?
Not for the older $5.54 billion fund. That claim deadline was February 4, 2025, and it has passed.
The newer $38 billion deal doesn’t use a claim form at all.
How much will I get from the credit card settlement?
There’s no flat number. Older fund payouts are based on your business’s actual interchange fees paid between 2004 and 2019.
The newer deal isn’t a cash payout, so there’s no individual amount to calculate.
Is the $38 billion settlement a cash payout for consumers?
No. It’s an estimate of merchant savings from lower interchange rates over five years, not a fund sitting in an account.
Individual cardholders aren’t part of either settlement’s class.
What is the interchange fee settlement administrator’s name?
That detail wasn’t confirmed in current court filings reviewed for this article.
Check the official Payment Card Settlement website for the current administrator’s contact information.
Do I need a lawyer to file a claim?
Filing a claim is free, and the claims window for the older fund is already closed regardless.
For future settlements, official claim forms never require payment to file.
What happened to the $30 billion settlement?
A judge rejected it in June 2024 for not going far enough. Fees would have stayed above pre-violation levels under those terms.
The rejected deal was later revised into the $38 billion settlement approved on a preliminary basis in June 2026.
When will the new settlement get final approval?
No confirmed date exists yet. Analysts at Keefe, Bruyette & Woods estimate late 2026 or early 2027.
A formal objection period and hearing come first, and an appeal could follow.
Can I still sell my claim if I already filed?
Some third-party firms buy already-filed claims for immediate payment instead of waiting for distribution.
That’s an optional, separate transaction, not something the court settlement requires.
If your business filed a claim in the older interchange fee fund, mark September 2026 on your calendar and check the official settlement website for your distribution status. If you’re watching the newer $38 billion deal, there’s no form to file yet, only a final approval hearing still to come.