National Life Group Lawsuit 2026: The IUL Illustration Ruling, Refiled Claims, and What Investors Need to Know
Quick Answer
- A Vermont judge dismissed the core claims against National Life in January 2026, but the plaintiff refiled with new allegations in January .
- The case centers on an IUL policy that returned 0% and allegations that National Life failed to disclose the Pacesetter Index was an “excess return” index .
- No settlement fund, claim deadline, or class action exists in this case as of October 2026 .
National Life Group is fighting a growing wave of litigation over indexed universal life insurance policies that failed to deliver the returns illustrated to buyers. A Vermont federal judge handed the company a significant win in January 2026, but the plaintiff refiled within weeks, and other cases are moving through courts in Pennsylvania, California, and beyond .
The core allegation is consistent across cases: National Life illustrated unrealistic returns using back-tested index data, downplayed the risks of premium financing, and failed to clearly disclose that certain indices were “excess return” rather than “total return” benchmarks .
There is no class action settlement to claim from. No payout fund exists. These are individual lawsuits with individual plaintiffs, each fighting for rescission of their policy or damages.
This article breaks down the Vermont ruling, the refiled complaint, the related Pennsylvania premium financing case, and what policyholders should understand about their legal options.
The Facts
| Case | Status | Key Detail |
|---|---|---|
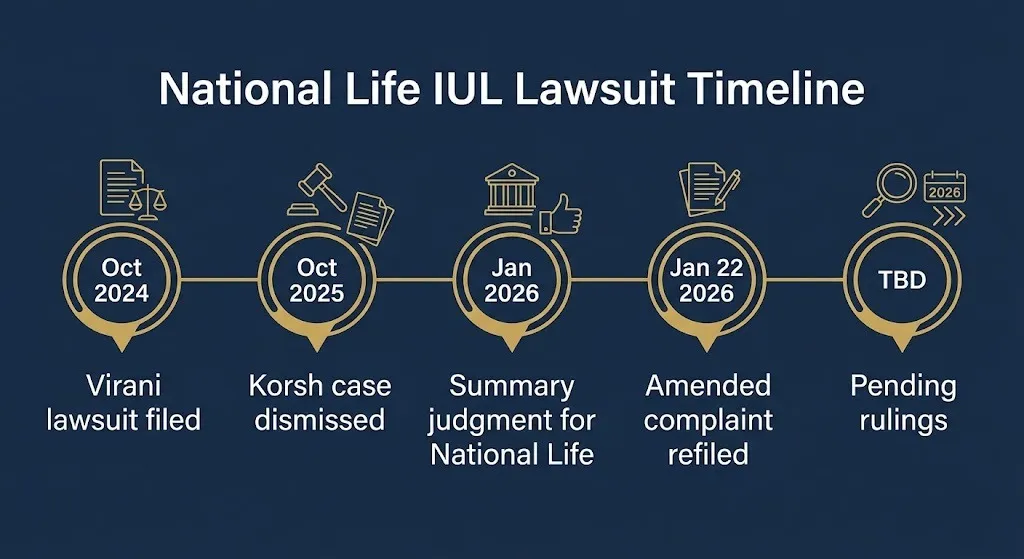
| Virani v. NLV Financial (D. Vt.) | Amended complaint pending | Summary judgment granted Jan. 2026; refiled Jan. 22, 2026 |
| Betts Client v. Life Insurance Co. of Southwest (Pa.) | Active in Allegheny County | Premium financing fraud claims, treble damages sought |
| Tsaturyan v. National Life Group (C.D. Cal.) | Active | Removed to federal court Aug. 2024 |
| Del Franco (D. Ariz.) | Interpleader action | National Life filed against agents over commissions |
| Korsh (W.D. Pa.) | Dismissed Oct. 2025 | National Life’s suit against doctor dismissed |
What did the Vermont judge rule in the National Life IUL lawsuit?
The Vermont judge ruled that National Life did not deceive the plaintiff during her life insurance purchase. Chief District Judge Christina Reiss granted summary judgment on breach of contract, deception, and racketeering claims brought by Sanya Virani of Indiana .
Judge Reiss found that Virani “failed to state a valid claim that she was deceived during her life insurance purchase.” The court noted that Virani did not assert the illustration or policy contained “any steering language that induced her to obtain the Policy and deposit her Accumulated Value into one Index rather than another” .
The ruling turned on a critical legal point: under Massachusetts law, insurance illustrations and buyer’s guides are not part of the contract. The policy itself governs, and the policy clearly allowed for 0% credited interest in a given year .
The judge gave Virani 20 days to refile an amended complaint, which she did on January 22, 2026 .
Key Takeaway: The Vermont ruling was a procedural and substantive win for National Life, but it did not end the case. The refiled complaint targets different legal theories and could survive a second motion to dismiss.
What does the refiled National Life lawsuit allege?
The amended complaint alleges material misrepresentation and deception in how National Life marketed the Pacesetter Index. Virani claims National Life disclosed that the Balanced Trend Index was an “excess return” index but failed to make the same disclosure for the Pacesetter Index .
That omission, “especially when coupled with the affirmative disclosure that Defendant did make concerning the Balanced Trend Index, had the capacity to mislead a reasonable consumer into believing that the Pacesetter Index was a (more valuable) total return index,” the lawsuit states .
The refiled complaint also alleges National Life promised 20 years of historical performance when the indices existed for only a fraction of that time. The performance data was based on a “highly speculative back-cast model” with less than a 1 in 1,000 chance of repeating, according to the filing .
Virani’s policy had a face amount of $2,767,336. She allocated 100% of her accumulated value to the US Pacesetter Index. Her 2024 annual statement showed 0% interest credited for the period September 2023 to September 2024 .
The new complaint adds a claim under the Massachusetts Consumer Protection Act and similar statutes in other states .
What is the Pennsylvania premium financing lawsuit about?
A separate lawsuit filed in Allegheny County, Pennsylvania, alleges that a high-dollar IUL policy issued by Life Insurance Company of the Southwest (a National Life affiliate) was sold in a fraudulent and deceptive manner .
The plaintiff’s complaint alleges the illustrations used by financial advisors ignored or downplayed the risks of premium financing. Specifically, it claims the defendants failed to disclose interest rate risk: the risk that rising rates would increase financing costs and require additional collateral .
That is exactly what happened. Rates spiked dramatically shortly after the policy was issued in August 2021, requiring substantially larger interest payments and additional collateral .
The six-count complaint asserts claims under the Pennsylvania Unfair Trade Practices and Consumer Protection Law, common law fraud, negligent misrepresentation, negligence, negligent supervision, and civil conspiracy. The plaintiff seeks rescission of the transaction and treble damages .
Reality Check
If you bought an IUL policy from National Life or Life Insurance Company of the Southwest and you’re unhappy with the returns, you likely cannot join a class action because none exists. These are individual lawsuits. Your options are to negotiate with the company, surrender the policy (which may trigger significant charges), or consult an attorney about your own claim. Surrender charges can be substantial: Virani’s policy had a $49,618.33 first-year surrender charge . Do not sign anything or accept a buyout without understanding the tax and legal consequences.
What is an “excess return” index and why does it matter?
An excess return index tracks the return of components net of the cost of funding a hypothetical investment in them. A total return index reflects the full return, including collateral returns .
For IUL policyholders, the difference is significant. An excess return index will underperform a total return index because the cost of funding is subtracted. If the underlying assets earn 5% but the funding cost is 2%, the excess return index credits only 3% .
National Life disclosed that the Balanced Trend Index was an excess return index. The lawsuit alleges it did not make the same disclosure for the Pacesetter Index, misleading consumers into believing they were getting a more valuable total return benchmark .
The Pacesetter Index is a volatility-controlled index hedged by Société Générale. It has a 0.50% per annum maintenance fee and fixed transaction and replication costs deducted daily. The index’s leverage may be as high as 200%, which amplifies both gains and losses .
What happened in the National Life v. Korsh case?
National Life Insurance Company filed a lawsuit against Dr. Korsh in 2024 (Case No. 3:24-cv-01263). The case was dismissed in October 2025 after a settlement conference in July 2025 .
Court records show the case was terminated on October 10, 2025. A settlement conference was held on July 29, 2025 .
The dismissal suggests the parties reached an agreement. Terms were not disclosed in the public docket.
What is the Del Franco case about?
National Life Distribution LLC filed an interpleader action in Arizona federal court against Vincent Del Franco, Charles Pettit, and LifeTyme Financial Group LLC in September 2024 .
An interpleader is a legal procedure where a party holding money or property asks the court to determine who is entitled to it. National Life filed this action, suggesting a dispute over commissions or compensation related to insurance sales.
The court ordered National Life to file an amended complaint properly alleging the defendants’ citizenship by December 6, 2024, or face dismissal for lack of subject matter jurisdiction .
How do you file a claim in a National Life lawsuit?
You can’t file a claim in a class action because none exists. The National Life litigation consists of individual lawsuits, not a consolidated class action with a claims process.
If you believe you have a claim against National Life, the path is:
- Gather your policy documents and illustrations.
- Document your returns and any communications with agents or National Life.
- Consult an attorney who handles insurance fraud or IUL litigation.
- Evaluate your options: rescission, damages, or negotiated resolution.
- File your own lawsuit if you and your attorney decide that’s the right path.
There is no claim deadline, no administrator, and no settlement fund to file against .
What happens next
Ongoing: Virani’s amended complaint in Vermont awaits National Life’s response and possible second motion to dismiss .
Ongoing: Pennsylvania premium financing case proceeds in Allegheny County .
Ongoing: Tsaturyan case continues in California federal court .
TBD: Any settlement or trial outcomes in any of the pending cases.
Ongoing: NAIC continues reviewing IUL illustration regulations that could affect future sales practices .
Frequently Asked Questions
Is there a National Life Group class action settlement?
No. The National Life litigation consists of individual lawsuits, not a class action. No settlement fund or claim process exists .
What was the Vermont judge’s ruling in the National Life IUL case?
The judge granted summary judgment for National Life on breach of contract, deception, and racketeering claims in January 2026 .
Can I still sue National Life over my IUL policy?
Yes, if you have grounds. The Vermont case was dismissed but refiled. Other cases are pending. Consult an attorney about your specific situation .
What is an excess return index?
An index that reflects returns net of funding costs, as opposed to a total return index that reflects full returns .
What is premium financing in life insurance?
A strategy where a third party lends money to pay policy premiums, with the policy as collateral. It carries interest rate risk that can increase costs substantially .
How much did the plaintiff in the Vermont case pay in premiums?
The complaint states Virani paid “tens of thousands of dollars” in premiums and faced a $49,618.33 surrender charge in the first year .
What is the National Life v. Korsh case about?
National Life filed suit against Dr. Korsh in 2024. The case was dismissed in October 2025 after a settlement conference .
Do I need a lawyer to sue National Life?
You can file pro se, but insurance litigation is complex. An attorney experienced in IUL and insurance fraud cases can evaluate whether you have a viable claim.
Closing
The National Life Group litigation is a patchwork of individual cases, not a class action with a payout. The Vermont ruling was a setback for one plaintiff, but the refiled complaint and the Pennsylvania premium financing case show the legal fight is far from over. If you own an underperforming IUL policy from National Life, gather your documents and consult an attorney before surrendering or accepting any buyout.