Lexington Law Settlement 2026: Status, Payouts, and Eligibility
Quick Answer
- This is real. The Consumer Financial Protection Bureau (CFPB) won a $2.66 billion judgment against Lexington Law and CreditRepair.com in 2023.
- The CFPB already sent $1.8 billion to 4.3 million consumers. Amounts varied based on fees paid.
- There is no claim deadline because there is no open claims process. Eligible consumers were identified automatically.
Yes, the Lexington Law settlement is real, and it is one of the largest consumer refund actions in CFPB history. A federal court ruled in 2023 that Lexington Law, CreditRepair.com, and their parent companies illegally charged upfront fees for credit repair services.
That ruling led to a $2.66 billion redress judgment. Roughly $1.8 billion of it has already reached 4.3 million harmed consumers as refund checks.
This article breaks down what’s confirmed, what’s still pending, and how to check your own status. One detail surprises most people: you cannot file a new claim. If you weren’t already flagged as a victim in company records, this settlement won’t pay you.
The Facts
| Category | Details |
|---|---|
| Case | Bureau of Consumer Financial Protection v. Progrexion Marketing, Inc. et al. (“Lexington Law Matter”) |
| Status | Judgment final since August 2023. Distribution ongoing. No new claims accepted. |
| Fund Size | $2.66 billion judgment. $1.8 billion approved for direct consumer refunds. |
| Est. Per Person | Pro-rata share of fees paid. AARP reported amounts commonly reaching into the hundreds of dollars. |
| Claim Deadline | None. There is no open claims window in this matter. |
| Administrator | JND Legal Administration |
| Proof Needed | None for your original check. ID verification only if requesting a reissue. |
Is the Lexington Law Settlement Real or a Scam?
It’s real. The CFPB confirmed the distribution directly, and the money came from a federal court judgment, not a private company promise.
Lexington Law and CreditRepair.com were found to have violated the Telemarketing Sales Rule by collecting fees before delivering promised results. A U.S. District Court in Utah ruled against them in March 2023.
The court entered a final judgment on August 30, 2023. That judgment ordered $2,660,926,481 in consumer redress, plus separate civil penalties.
Here’s a quick trust check:
- Confirmed by a federal regulator (CFPB), not a marketing company
- Administered by JND Legal Administration, a known court-appointed firm
- No fee, no sign-up, and no personal payment required to receive a check
Key Takeaway: The Lexington Law settlement is a real, court-ordered CFPB redress judgment, not a rumor or a phishing setup.
Is This a Class Action Lawsuit or a CFPB Settlement?
It’s a CFPB enforcement judgment, not a traditional class action. That distinction matters more than most headlines admit.
In a private class action, a law firm sues on behalf of a group, and the court later approves a negotiated settlement. Class members usually file a claim form to get paid.
This case worked differently. The CFPB, a federal agency, sued Lexington Law and CreditRepair.com directly. The court ruled against the companies and ordered redress paid straight to victims identified in company records.
There’s a separate case that does carry the “class action” label: a 2017 Telephone Consumer Protection Act (TCPA) lawsuit accusing Lexington Law of unsolicited calls and texts. That case settled for roughly $11 million and closed years ago. It is a different matter from the CFPB action described here.
How Much Is the Lexington Law Settlement Worth?
The total judgment is $2.66 billion, but the amount actually reaching consumers is $1.8 billion.
| Component | Confirmed Amount |
|---|---|
| Consumer redress judgment | $2,660,926,481 |
| Civil penalty, Progrexion Marketing | $45,817,452 |
| Civil penalty, Lexington Law (Heath firm) | $18,408,726 |
| Distributed to consumers (first round) | $1.8 billion |
| Consumers covered | 4.3 million |
The gap between the $2.66 billion judgment and the $1.8 billion distributed reflects the companies’ bankruptcy. Lexington Law’s parent, PGX Holdings, filed Chapter 11 not long after the ruling, closing about 80 percent of its operations.
The CFPB pulled the $1.8 billion from its victims relief fund, which is financed by civil penalties paid across many enforcement cases, not from taxpayer money.
How Much Money Will I Get From the Lexington Law Settlement?
Your payout, if you already received one, was calculated as a pro-rata share of fees you paid. There is no flat, guaranteed amount for everyone.
The administrator compared your billing history against total funds available. AARP reported that typical checks ranged up to several hundred dollars.
Three factors shaped individual amounts:
- How much you paid Lexington Law or CreditRepair.com
- How many months you were enrolled during the covered period
- The overall size of the distribution pool relative to total harm
Not yet determined: whether any additional distribution round will happen in 2026, and if so, how it would be calculated. The administrator has said only that leftover funds “may” fund additional checks to people who already cashed their first one.
Reality Check
No government agency or law firm will ever text or call you first asking for banking details to “release” your Lexington Law refund. Real checks arrive by mail with no fee attached. If someone offers to speed up your payment for a charge, that is a scam, not a shortcut.
How Do I File a Lexington Law Settlement Claim?
You can’t file a new claim in this matter. The CFPB already identified every eligible consumer through company records.
That single fact trips up more searchers than anything else about this case. Most settlement guides assume a claim form exists. Here, it doesn’t.
What actually happened instead:
- The CFPB obtained Lexington Law and CreditRepair.com’s billing records during litigation.
- The agency cross-checked those records against the court’s eligibility window.
- JND Legal Administration mailed checks directly to identified consumers.
- No submission, application, or portal was ever opened to the public.
If you paid for credit repair services during the covered window and never received anything, your next step isn’t filing a claim. It’s contacting the administrator to check your status.
What If I Never Got My Lexington Law Refund Check?
You may not be listed in the eligible consumer records, or your check may have gone to an old address. Contact JND Legal Administration directly to check.
Call 1-855-680-8991 (toll-free) or write to the mailing address below. Have your name and the address you used with Lexington Law or CreditRepair.com ready.
Lexington Law Matter
c/o JND Legal Administration
P.O. Box 91015
Seattle, WA 98111
Important: there is no appeals process to add yourself if you were never included in the original records. The administrator can only confirm status or process a reissue for consumers already identified.
How Do I Request a Check Reissue?
You can request a reissue online, by email, or by mail if your original check was lost, expired, or sent to the wrong address. Reissues go out in scheduled batches roughly every two months.
Steps to request a reissue:
- Locate your Unique ID from your original check or letter.
- Visit the Contact Us page on the official settlement site, or email [email protected].
- Provide your name, current address, and prior address if it changed.
- Wait for a scheduled reissue run, not an instant reprocessing.
- Allow three weeks for USPS delivery before following up again.
If you don’t have your Unique ID, call the administrator’s toll-free line and a representative can retrieve it for you.
Key Takeaway: There’s no live claims window, so your only path to payment is confirming your existing status or requesting a reissue of a check already sent in your name.
What Is the Latest Lexington Law Lawsuit Update in 2026?
As of this writing, the case remains in its distribution phase, with no newly announced mass mailing confirmed for 2026. Reissue requests continue to be processed on a rolling basis.
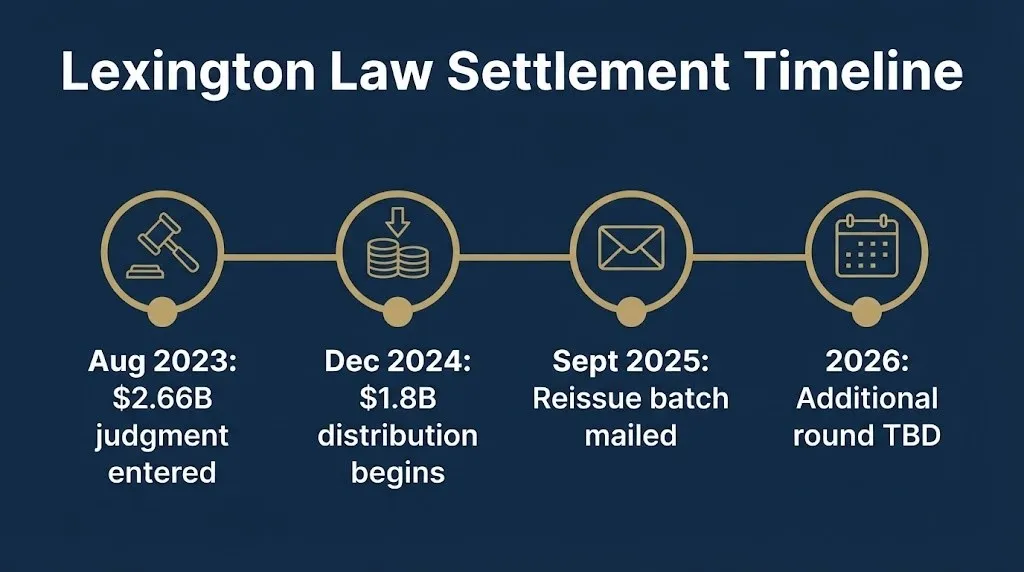
The most recent confirmed batch of reissued checks went out September 9 through 12, 2025, with an expiration date of December 11, 2025. No new bulk-distribution date beyond that has been publicly confirmed by the CFPB or JND as of this writing.
Some independent sites have referenced a “second round” or “2026 catch-up round” of payments. That claim is not yet confirmed by the CFPB or the official settlement site. Treat those reports as unverified until the administrator or CFPB posts an update.
When Will Lexington Law Settlement Checks Be Mailed in 2026?
There is no confirmed mass-mailing date for 2026. The only ongoing mailings are individual reissues tied to specific consumer requests.
Think of it the way you’d think about a delayed tax refund reissue: the government isn’t sending a new wave to everyone, it’s just processing individual replacement requests as they come in.
If a broader 2026 distribution is announced, it would most likely appear first at cfpb.gov/payments/lexlaw or on the official cfpb-lexlaw.org site.
Is There a New Round of Lexington Law Payments in 2026?
Not confirmed. The administrator has said only that leftover funds “may” support additional checks to consumers who already cashed a prior payment, with no set schedule.
That means two groups exist right now:
- Consumers still waiting on a reissue of an already-approved payment
- Consumers hoping for a brand-new distribution round, which has no confirmed date
If you fall into the second group, there is currently no action to take. This matter has no open claims process to join.
Who Is Eligible for the Lexington Law Settlement?
You were eligible if you paid Lexington Law or CreditRepair.com for credit repair services during a defined window and were subject to telemarketing or a deceptive marketing affiliate transfer.
| Eligibility Path | Covered Dates |
|---|---|
| Paid after direct telemarketing contact | March 8, 2016, through August 30, 2023 |
| Paid after being live-transferred by a marketing affiliate | July 21, 2011, through August 30, 2023 |
You do not need to apply to become eligible. The CFPB already identified qualifying consumers using company billing and marketing records collected during the investigation.
If you paid for services in these windows but never received a check or a letter, that most likely means the records didn’t flag you, not that you’re ineligible outright. Confirming your status with the administrator is the only way to know for sure.
What Did Lexington Law Do Wrong?
Lexington Law and CreditRepair.com collected fees before delivering the credit repair results they had promised, violating the Telemarketing Sales Rule’s advance-fee ban.
The CFPB’s case also alleged deceptive, bait-and-switch advertising tied to how the companies marketed guaranteed results. A federal court agreed with the CFPB’s core claims in March 2023.
The companies operated under a web of related entities based in Salt Lake City, including PGX Holdings, Progrexion Marketing, Progrexion Teleservices, eFolks, and the John C. Heath law firm doing business as Lexington Law. Combined, these entities reported around $388 million in annual revenue in 2022, drawing in more than 4 million customers nationwide.
What Happened to Lexington Law After the Lawsuit?
Lexington Law’s parent company filed for Chapter 11 bankruptcy protection shortly after the 2023 judgment, shutting down roughly 80 percent of its operations, including call centers.
That bankruptcy is part of why the $2.66 billion judgment didn’t translate into a $2.66 billion payout. Insolvent defendants can’t pay a judgment they don’t have assets to cover.
The CFPB instead used its own victims relief fund, financed by penalties from other enforcement cases, to cover the $1.8 billion distributed so far. That’s a separate pool of money from what Lexington Law itself could pay.
Key Takeaway: Lexington Law’s bankruptcy limited direct recovery from the company, so most of the $1.8 billion already paid came from the CFPB’s own penalty fund, not from Lexington Law’s remaining assets.
Is the Lexington Law TCPA Settlement the Same as This One?
No. The TCPA settlement is a separate, older, and already closed case worth about $11 million, unrelated to the CFPB’s $2.66 billion judgment.
That 2017 case accused Lexington Law of sending unsolicited calls and texts in violation of the Telephone Consumer Protection Act. It resolved years before the CFPB’s advance-fee case went to trial.
If you’re searching for “Lexington Law class action lawsuit” hoping to file something new, be aware: both the TCPA case and the CFPB matter are closed to new claims. Neither currently accepts new filers.
What Happens Next
Late 2025: Final reissue batch from the September 2025 run expired December 11, 2025, closing that reissue window.
Ongoing through 2026: Individual reissue requests continue processing roughly every two months for consumers with lost, expired, or misdirected checks.
Pending, no confirmed date: Any additional bulk distribution from remaining settlement funds. Not yet confirmed by the CFPB or JND.
Watch for updates: Check cfpb.gov/payments/lexlaw or cfpb-lexlaw.org periodically for any new distribution announcement.
Frequently Asked Questions
Is the Lexington Law settlement legit?
Yes. It’s a federal court judgment secured by the CFPB, administered by JND Legal Administration.
No fee or personal information request is required to receive a legitimate check.
How do I check if I’m eligible for a Lexington Law refund?
You can’t apply, but you can confirm your status by calling JND Legal Administration at 1-855-680-8991.
Have your name and prior Lexington Law or CreditRepair.com account details ready.
Can I still file a claim for the Lexington Law settlement?
No. All eligible consumers were identified automatically through company records.
There is no application or claims process open to the public.
How much was the average Lexington Law settlement check?
Amounts varied based on fees paid and were calculated on a pro-rata basis.
AARP reported typical checks reaching into the hundreds of dollars, though this isn’t a fixed figure.
What if my Lexington Law check expired before I cashed it?
Request a reissue through the official settlement site or by mailing JND Legal Administration.
Reissues are sent in scheduled batches roughly every two months.
Is there a deadline to claim Lexington Law settlement money?
There is no claim deadline because there is no open claims process in this matter.
Reissue requests for already-approved checks remain ongoing.
Why did I never receive a Lexington Law settlement check?
You may not have been flagged as an eligible consumer in company billing records.
Contact the administrator directly to confirm your status rather than assuming eligibility.
Is the Lexington Law lawsuit the same as the CreditRepair.com lawsuit?
Yes, largely. Both brands were named together in the same CFPB enforcement action and judgment.
They share the same administrator, eligibility windows, and distribution process.
If you paid Lexington Law or CreditRepair.com for credit repair services between 2011 and 2023, check your mail carefully and confirm your status directly with JND Legal Administration. Save any records of what you paid in case a reissue or future distribution requires them. The most important number to remember: $1.8 billion already mailed to 4.3 million consumers, with no new claims window open.