WithU Loans Lawsuit 2026: The 498% Interest Case, the Supreme Court Petition, and Why No Payout Exists
Quick Answer
- Is it legit: Yes. A proposed class action in Illinois federal court alleges WithU charged nearly 500% APR on $600 loans, violating state and federal law.
- How much: Not yet determined. No settlement has been reached. The case is still fighting over whether it goes to arbitration or stays in court.
- Deadline: No claim deadline exists. The Supreme Court petition is pending, with a response due November 6, 2026.
If you searched for “WithU Loans lawsuit,” you probably borrowed money from an online lender, saw an interest rate that looked impossible, and want to know whether anyone is paying for it. The short answer is that a real lawsuit exists, but it has not produced a settlement, a claim form, or a dime for borrowers yet.
The case is Harris v. W6LS, Inc., filed in the Northern District of Illinois. Two borrowers, Joshua Harris and Donita Olds, each took out $600 loans from WithU with annual percentage rates of 498.63% and 497.25% respectively . They sued on behalf of a proposed Illinois class, alleging the loans violate the Illinois Interest Act, the Illinois Predatory Loan Prevention Act, RICO, and the Electronic Fund Transfer Act .
WithU has fought the case at every turn, arguing the loans are tribal business and the borrowers agreed to arbitration. The Seventh Circuit rejected that argument in March 2026. WithU has now asked the Supreme Court to step in.
The Facts
| Item | Verified Detail |
|---|---|
| Case Name | Joshua Harris and Donita Olds v. W6LS, Inc. d/b/a WithU and WithU Loans, and Caliber Financial Services, Inc. |
| Court | U.S. District Court, Northern District of Illinois, Eastern Division |
| Case Number | 1:23-cv-16429 |
| Current Status | Active. WithU filed a Supreme Court cert petition on October 5, 2026 |
| Settlement Fund | None. No settlement has been reached. |
| Est. Per Person | Not yet determined. No class has been certified and no fund exists. |
| Claim Deadline | None. No claims process exists. |
| Administrator | Not yet appointed. No settlement administrator exists. |
| Proof Needed | Not applicable. No claim form exists. |
Is the WithU Loans Lawsuit Real or a Scam?
The WithU Loans lawsuit is real, filed in federal court, and still active. It is not a scam, but it is also not a settlement program, and no one is sending checks.
The case began when Harris and Olds sued W6LS, Inc. and Caliber Financial Services in 2023 . They alleged that WithU, an online lender claiming tribal affiliation with the Otoe-Missouria Tribe, charged interest rates near 500% on small loans to Illinois residents . Illinois law caps interest at much lower rates, and the borrowers argued WithU was evading those caps by claiming tribal immunity.
WithU’s defense has focused on arbitration. The loan agreements contained clauses requiring borrowers to arbitrate disputes individually, with a delegation provision sending even the question of arbitrability to the arbitrator . The district court refused to compel arbitration, the Seventh Circuit affirmed, and WithU is now asking the Supreme Court to reverse that decision.
Scam risk exists around this case. Any website or message claiming a “WithU settlement payout” is false. No court has approved a fund, no class has been certified, and no claim deadline exists.
Key Takeaway: The WithU Loans lawsuit is real and active, but it has not produced a settlement. No borrower is owed money from it yet, and any claim form you see is fake.
How Much Could WithU Loans Borrowers Get?
Not yet determined. No settlement fund exists, no class has been certified, and no court has approved any payout amount. Any specific dollar figure circulating online is speculation.
What the complaint does establish is the scale of the alleged harm. Harris borrowed $600 at 498.63% APR. Olds borrowed $600 at 497.25% APR . Those rates are the core of the case. If the class is certified and prevails or settles, damages would be calculated based on the interest and fees borrowers paid above what Illinois law allows.
A separate Washington case, Oftedahl v. W6LS Inc., involves a borrower who claims he was pushed into a loan with a nearly 568% interest rate to pay for his cat’s cancer treatment . That case is at the motion-to-compel-arbitration stage, not settlement.
| Financial Item | Verified Detail |
|---|---|
| Settlement fund | None |
| Class certification | Not yet granted |
| Representative loan amounts | $600 each for Harris and Olds |
| Representative APRs | 498.63% and 497.25% |
| Payout estimate | Not yet determined |
Reality Check: No one texts you settlement money first. WithU has not settled, and no claims administrator has been appointed. If a message asks for your bank details to “release your WithU refund,” it is a scam.
Can You File a Claim in the WithU Loans Lawsuit?
You cannot file a claim because no claim process exists. The case is still in the pre-trial phase, fighting over whether it belongs in arbitration or court.
Class actions create claim forms only after a settlement is approved or a judgment is final. Neither has happened here. The Seventh Circuit ruled on arbitration in March 2026. WithU filed a Supreme Court petition in October 2026 . Until that petition is resolved, the case cannot move toward class certification, let alone settlement.
If you borrowed from WithU and want to preserve your rights, the practical step is to keep your loan documents, bank statements showing payments, and any communication from WithU. Do not send money or personal information to anyone claiming to process a WithU claim. There is no legitimate processor because there is no claim process.
What Is the WithU Loans Lawsuit About?
The WithU Loans lawsuit is about whether an online lender can use a tribal affiliation to charge interest rates that state law would otherwise prohibit. The borrowers allege WithU is a “rent-a-tribe” operation that uses the Otoe-Missouria Tribe as a legal shield.
The complaint details the structure. W6LS, Inc. claims to be a corporation organized under tribal law and owned by the Tribe . Its listed address is a rented private mailbox at a UPS store in Oklahoma City. The plaintiffs allege the actual principal place of business is in Mission, Kansas . The loans are originated online, funded electronically, and repaid by ACH debit from borrowers’ bank accounts, all without any borrower ever setting foot on tribal land.
The legal theory is that tribal sovereign immunity does not extend to this arrangement because the Tribe is a nominal owner, not the real operator. If that theory holds, Illinois consumer protection statutes apply, and the interest rates violate them.
The Seventh Circuit did not decide the merits of that theory. It decided only that the arbitration agreement could not be enforced because it required the arbitrator to apply tribal law that did not exist when the loans were made . That is a procedural win for the borrowers, not a final ruling on whether WithU broke the law.
Why Did the Seventh Circuit Reject WithU’s Arbitration Clause?
The Seventh Circuit rejected WithU’s arbitration clause because the agreement directed the arbitrator to apply a body of tribal law that did not exist at the time the loans were signed. Without a valid body of governing law, the court found no mutual assent to arbitrate.
The loan agreements stated that disputes would be governed by “Tribal law and applicable federal law” . But the Otoe-Missouria Tribe did not adopt its Contract Code until May 2, 2024. Harris took out his loan in 2023, and Olds in 2022 . The tribe later said the code applied retroactively, but the Seventh Circuit was not persuaded that parties can designate a nonexistent body of law and then have it supplied after the fact.
The court’s March 31, 2026 opinion framed it plainly: the defendants “drafted an arbitration agreement directing an arbitrator to apply a body of law that did not exist, which they maintained a unilateral ability to invent” . That lack of mutual assent doomed the arbitration clause.
The district court had relied on a different theory, the prospective waiver doctrine, finding the arbitration agreement would strip borrowers of their Illinois statutory rights. The Seventh Circuit affirmed on the mutual assent ground and discussed prospective waiver as an alternative basis . Either way, WithU lost the arbitration fight at the appellate level.
Key Takeaway: WithU’s arbitration clause failed because it pointed to tribal law that did not exist when the loans were signed. That procedural loss is why the case is still alive in federal court.
Where Does the WithU Loans Lawsuit Stand Now?
The WithU Loans lawsuit is before the U.S. Supreme Court on a petition for certiorari, filed October 5, 2026. The case is paused at the appellate stage while the justices decide whether to hear WithU’s appeal.
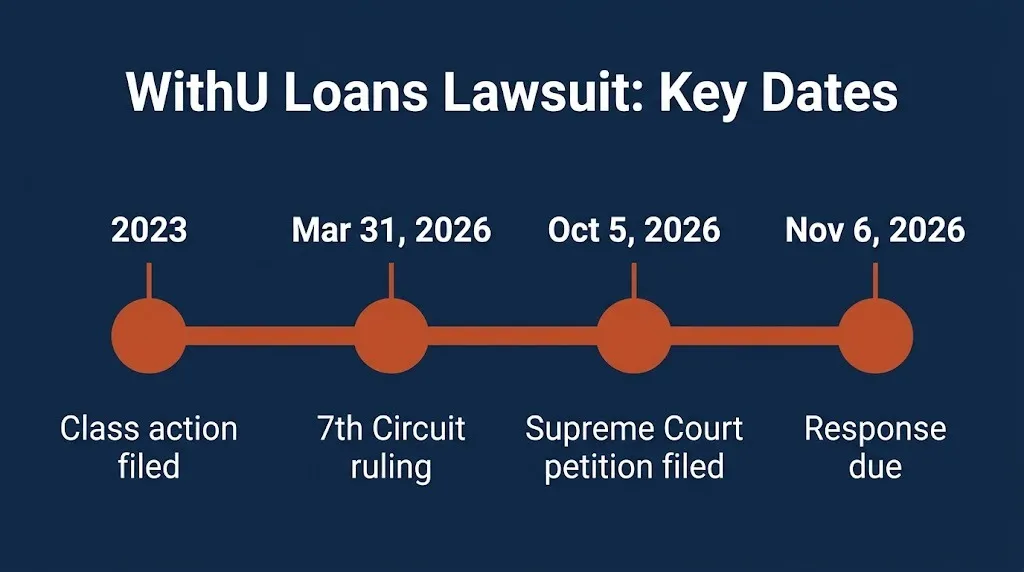
WithU’s petition asks the Supreme Court to review the Seventh Circuit’s decision. The docket shows the petition was filed after two extension requests. Justice Barrett granted one extension to October 5, then denied a second request to push the deadline to November 2 . The petition was filed on the final extended deadline.
The response from the borrowers is due November 6, 2026 . After that, the justices will decide whether to grant certiorari. Most petitions are denied. If this one is denied, the case returns to the district court, where the borrowers will seek class certification and the litigation will proceed on the merits.
If the Supreme Court grants the petition, the case could be tied up for another year or more. Either way, no settlement is imminent, and no consumer payout is on the horizon.
What Happens Next in the WithU Loans Lawsuit?
The next stages in the WithU Loans lawsuit depend on the Supreme Court’s decision on the cert petition. The timeline below reflects the verified dates and the expected sequence if the petition is denied.
November 6, 2026: Borrowers’ response to the cert petition is due .
Expected late 2026 to early 2027: Supreme Court decides whether to grant or deny certiorari. Most petitions are denied.
If denied, expected 2027: Case returns to the Northern District of Illinois. Plaintiffs move for class certification.
If certified, expected 2027 to 2028: Discovery on the merits, including WithU’s tribal ownership structure and lending practices.
No settlement date: No settlement talks have been confirmed, and no claim process exists.
Frequently Asked Questions
Is the WithU Loans lawsuit a class action?
Yes. It is a proposed class action filed on behalf of Illinois borrowers who took out loans from WithU. The class has not yet been certified.
How much will WithU borrowers get?
Not yet determined. No settlement exists, no class has been certified, and no payout amount has been approved.
Did WithU Loans settle?
No. WithU is fighting the case at the Supreme Court level. No settlement has been announced.
What interest rate did WithU charge?
The named plaintiffs borrowed $600 at APRs of 498.63% and 497.25%. A separate Washington case alleges a rate near 568%.
Is WithU Loans a tribal lender?
WithU claims affiliation with the Otoe-Missouria Tribe. The plaintiffs dispute that the tribe actually operates the business.
Can I join the WithU Loans lawsuit?
Not yet. No class has been certified and no claim process exists. If a class is certified, eligible borrowers will be notified through court-approved channels.
Where can I check for WithU lawsuit updates?
The federal court docket in the Northern District of Illinois and the Supreme Court docket for Case No. 26-467 are the authoritative sources. Social media and third-party claim sites are not.
The WithU Loans lawsuit is real, but it is not a payout program. No settlement exists, no claim form is open, and the case is still fighting over whether it belongs in arbitration or court.
The date that matters right now is November 6, 2026, when the borrowers respond to WithU’s Supreme Court petition. Until the justices decide, nothing moves toward a settlement. Keep your loan documents, watch the court dockets, and ignore anyone who says money is waiting.