Are Class Action Settlements Taxable in 2026? What the IRS Actually Says
Quick Answer
- Most class action settlement money is taxable unless it compensates a physical injury or physical sickness.
- There is no flat “settlement tax rate.” Taxable portions get added to your income and taxed at your regular bracket, 10% to 37% for 2026.
- Payments over $600 often trigger a Form 1099, and you must report taxable settlement income on the return you file for the year you received it.
You got a check, or a text about one, and now you’re wondering what the IRS wants from it. Here’s the direct answer: it depends on what the lawsuit was actually about, not what the check says on the memo line.
The IRS calls this the “origin of the claim” test. A settlement tied to a broken bone or a car accident injury usually stays untaxed. A settlement for lost wages, discrimination, or a data breach usually doesn’t.
This article walks through every category, physical injury, emotional distress, punitive damages, employment claims, and shows you exactly how to report what you owe. One detail catches people off guard: even a completely tax-free settlement can still trigger a 1099 form, and that mismatch is one of the top reasons people get an IRS notice.
The Facts
| Category | What the IRS Says |
|---|---|
| General rule | All income is taxable unless a specific tax code section excludes it (IRC Section 61) |
| Physical injury exclusion | Damages for personal physical injury or physical sickness are excluded under IRC Section 104(a)(2) |
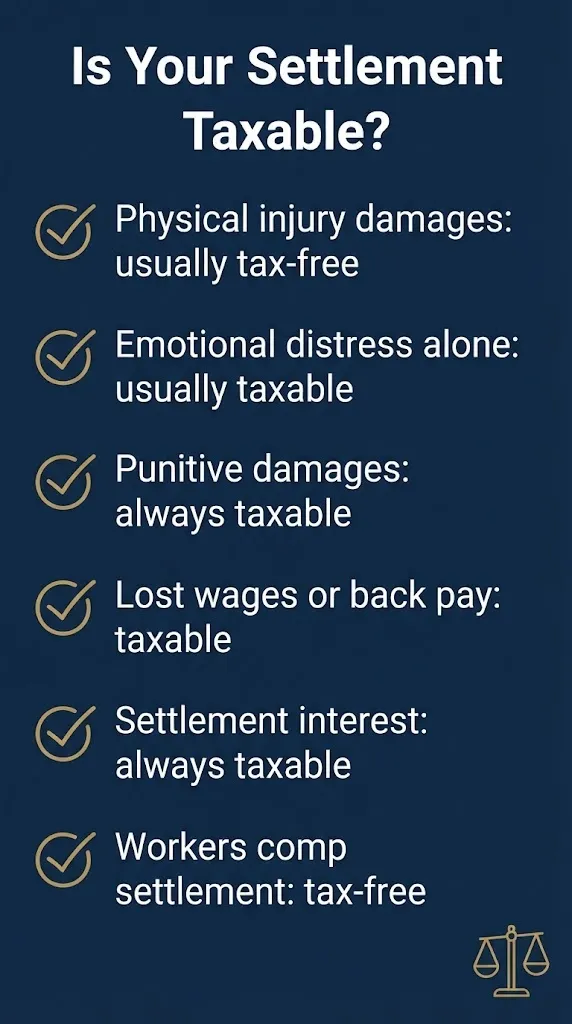
| Emotional distress alone | Taxable, unless it flows directly from a physical injury |
| Punitive damages | Always taxable, even in physical injury cases |
| Lost wages in employment cases | Taxable as wages, subject to income tax and payroll tax |
| Interest on a settlement | Always taxable, regardless of case type |
| 1099 reporting threshold | Generally $600 or more, per IRS Form 1099 instructions |
| 2026 marginal tax rates | 10% to 37%, based on your total income and filing status |
Not every settlement fits neatly into one box. Many payouts blend taxable and nontaxable pieces, and the settlement agreement’s language on how the money is allocated matters more than most people realize.
Are class action settlements taxable in 2026?
Most class action settlement payments are taxable in 2026 unless the underlying claim involves a personal physical injury or physical sickness. The IRS does not look at the word “settlement.” It looks at what the lawsuit claimed happened to you.
If the class action alleged a data breach, defective product, or overcharge, the payout usually replaces money you lost or compensates for a nonphysical harm, so it counts as taxable income. If the class action stemmed from a physical injury, like a defective device that caused bodily harm, that portion can qualify for the exclusion.
Quick rule of thumb:
- Consumer, privacy, and financial class actions: usually taxable.
- Product defect settlements tied to bodily injury: often excluded.
- Employment class actions: mostly taxable, including back pay.
Every class action settlement notice should state what the payment is for. Read that section before you assume either way.
Is lawsuit money taxable no matter the type of case?
No, lawsuit money is not automatically taxable, the type of claim decides it. Section 61 of the tax code makes all income taxable by default, but Section 104 carves out an exception for personal physical injury and physical sickness.
That means two people with identical dollar amounts can owe completely different taxes. One person’s $50,000 settlement for a broken leg is tax-free. Another person’s $50,000 settlement for wrongful termination is fully taxable as wages.
The origin of the claim test looks at the complaint you filed, not the eventual outcome. Courts and the IRS both examine what you actually sued for.
Key Takeaway: Whether lawsuit money is taxable comes down to one question: was the claim rooted in a physical injury or physical sickness, or something else.
Do you pay taxes on a settlement for physical injury?
Generally, no, you do not pay federal income tax on a settlement for a physical injury or physical sickness. This is the clearest exclusion in the entire tax code section covering lawsuits.
IRS Publication 4345 confirms that damages for personal physical injuries, including related medical expenses, pain and suffering, and even lost wages that stem directly from the physical harm, fall under this exclusion. A car accident settlement, a slip-and-fall payout, or a medical malpractice recovery tied to bodily injury generally stays out of your gross income.
There are two exceptions inside an otherwise tax-free injury settlement:
- Punitive damages are always taxable, even in a physical injury case.
- Prior medical deductions you already claimed and got a tax benefit from must be reported if the settlement reimburses those same expenses.
If you didn’t itemize those medical costs before, this exception won’t apply to you.
How much of a lawsuit settlement is taxable?
The taxable portion of a lawsuit settlement equals whatever part does not qualify for a specific exclusion, there is no single percentage that applies to everyone. A settlement agreement that breaks out compensatory damages, punitive damages, and interest separately makes this calculation much easier.
Here’s a simplified breakdown of how a mixed settlement often gets split:
| Settlement Component | Typically Taxable? |
|---|---|
| Physical injury compensatory damages | No |
| Medical expenses (not previously deducted) | No |
| Emotional distress from a physical injury | No |
| Emotional distress alone, no physical injury | Yes |
| Lost wages or back pay | Yes |
| Punitive damages | Yes |
| Interest on the award | Yes |
| Property damage, up to adjusted basis | No |
If your settlement agreement lumps everything into one number with no breakdown, that ambiguity works against you at tax time. Ask for an itemized allocation whenever a case involves both physical and nonphysical claims.
Personal injury settlement taxable: what’s excluded and what’s not
A personal injury settlement is taxable only for the pieces that don’t stem from a physical injury or physical sickness, the core injury compensation itself stays excluded. This applies whether you settled out of court or won at trial, and whether you got a lump sum or structured payments.
Compensation that typically stays untaxed in a personal injury case:
- Medical bills and future medical care tied to the injury
- Pain and suffering connected to the physical harm
- Lost wages, when they flow directly from the physical injury itself
- Loss of consortium claims filed by a spouse
Compensation that typically gets taxed even in a personal injury settlement:
- Punitive damages
- Interest that accrued on the award
- Emotional distress with no underlying physical injury
Reality Check: No legitimate settlement administrator or law firm will ask you to pay a fee upfront to “release” your tax-free settlement money. Filing a claim is always free, and physical injury settlements do not require special tax paperwork to stay excluded. Third-party companies that offer to “unlock” your settlement for a fee are not part of the legitimate claims process.
Are lawsuit winnings taxable the same as a settlement?
Yes, a jury verdict is taxed the same way a negotiated settlement is, the IRS applies the identical origin-of-claim test to both. Whether you won at trial or settled before trial changes nothing about how the money gets categorized for tax purposes.
The court’s judgment or the settlement agreement should specify what the damages compensate for. If a jury awards punitive damages as a separate line item, that portion is taxable regardless of how sympathetic your underlying injury claim was.
Key Takeaway: A trial verdict and an out-of-court settlement get the same tax treatment, what matters is the nature of the claim, not how the case ended.
Do you pay taxes on lawsuit money paid directly to your attorney?
You generally still owe tax on the full settlement amount, even the portion your attorney keeps as a fee, in most non-physical-injury cases. This surprises a lot of people, but under current law, plaintiffs in many taxable cases must report gross settlement proceeds, not just their net check.
Here’s how it typically works in a taxable case with contingency fees:
- The total settlement is $100,000.
- Your attorney’s fee is $40,000.
- You receive a net check of $60,000.
- In many taxable cases, you must report the full $100,000 as income.
- You may then be able to deduct or offset attorney fees depending on the case type.
Physical injury settlements avoid this problem entirely because the whole amount, including the attorney’s cut, is typically excluded from income in the first place. Employment cases and certain other claims may allow an above-the-line deduction for attorney fees, which reduces the sting.
How to report settlement income on your 2026 tax return
You report taxable settlement income as “Other Income” on Schedule 1, Line 8z of Form 1040, and taxable back pay as wages if you received a W-2. The reporting location depends entirely on what kind of payment you got.
Steps to report a taxable settlement correctly:
- Locate the settlement agreement’s damage allocation.
- Separate taxable pieces from excluded pieces.
- Check any 1099 forms you received against the settlement agreement.
- Report taxable non-wage amounts on Schedule 1, Line 8z.
- Report taxable back pay or front pay as wages if a W-2 was issued.
- Keep the settlement agreement and correspondence for your records.
- Consult a tax professional if the allocation is unclear or disputed.
If part of your settlement reimburses medical expenses you deducted in a prior year and got a tax benefit from, that portion becomes taxable too, and it also goes on Line 8z.
What happens if you get a 1099 for a nontaxable settlement?
Getting a 1099 does not automatically mean the money is taxable, it means the payer reported the payment to the IRS, and you may need to correct the record. This mismatch happens more often than people expect, especially when a settlement check is made jointly payable to you and your attorney.
Under IRC Section 6045, a defendant or insurer paying an attorney “in connection with legal services” often must issue a 1099, sometimes to both the attorney and the plaintiff, even when the underlying claim is fully excluded from income. If your physical injury settlement generated a 1099, you’re not necessarily on the hook for tax on it.
What to do if this happens to you:
- Keep a copy of the settlement agreement showing the physical injury basis.
- Attach an explanatory statement to your tax return if needed.
- Talk to a tax preparer before you assume you owe tax you don’t.
Taxation settlement: emotional distress, punitive damages and interest
Emotional distress damages, punitive damages, and settlement interest are the three components most likely to be taxed even inside an otherwise excluded personal injury case. Treasury Regulation 1.104-1(c)(1) draws a hard line here.
Emotional distress: Only excluded when it’s attributable to a physical injury or physical sickness. Standalone emotional distress, even if it’s severe, is taxable on its own. Courts have repeatedly ruled that physical symptoms of stress, like headaches or insomnia, do not count as a physical injury for this purpose.
Punitive damages: Always taxable, no exceptions, even in wrongful death or catastrophic injury cases where the underlying compensatory damages are excluded.
Interest: Any interest that accrues on a settlement or judgment, whether pre-judgment or post-judgment, is taxable as interest income, separate from the underlying damages.
Are employment lawsuit settlements taxed differently?
Yes, employment settlements carry the heaviest tax burden of any settlement category because back pay is treated as wages, subject to both income tax and payroll tax. This is different from most personal injury or product liability settlements.
| Employment Settlement Component | Tax Treatment |
|---|---|
| Back pay or front pay | Taxable as wages, subject to Social Security and Medicare tax |
| Emotional distress from discrimination claim | Taxable, per Revenue Ruling 96-65 |
| Attorney fees in employment cases | Taxable to plaintiff, but often deductible above the line |
| Severance pay | Taxable as wages |
Key Takeaway: Employment settlements almost always generate taxable income, and back pay specifically triggers payroll taxes on top of ordinary income tax, unlike most physical injury payouts.
Do you pay taxes on workers’ compensation settlements?
No, workers’ compensation settlements are excluded from federal income tax under IRC Section 104(a)(1), regardless of whether you received weekly benefits or a lump sum. This is one of the more clear-cut rules in this entire area of tax law.
The exclusion covers workers comp payments received under a workers compensation act or similar statute, full stop. It doesn’t matter whether the injury was minor or catastrophic.
One exception to know: If you also receive Social Security Disability Insurance and your workers comp settlement causes an SSDI offset, that offset amount can become taxable. This is a narrow situation, but it trips people up who receive both benefits at once.
What about attorney fees, are they taxed to you too?
In taxable, non-physical-injury cases, attorney fees are frequently included in your gross income even though the money never touched your bank account. The American Jobs Creation Act created an above-the-line deduction for attorney fees in certain unlawful discrimination and whistleblower cases, which helps offset this.
Without that specific deduction, you could face the strange result of paying tax on money your attorney kept as a contingency fee. This is one reason employment and discrimination settlements often carry a higher effective tax burden than the settlement amount alone suggests.
Physical injury settlements sidestep this entirely, since the whole recovery, attorney fees included, is typically excluded from income from the start.
Settlement tax rate: what bracket applies to your payout
There is no separate “settlement tax rate,” taxable settlement income gets added to your other income for the year and taxed at your regular marginal bracket, which ranges from 10% to 37% for 2026. The IRS does not carve settlements into their own tax category.
A practical example: if you normally earn $60,000 a year and receive a $30,000 taxable settlement, that $30,000 stacks on top of your existing income. It can push part of your income into a higher bracket for that year only.
Ways this affects your filing:
- A large settlement received mid-year can trigger estimated tax obligations.
- You may need to make quarterly estimated payments to avoid an underpayment penalty.
- 2026 estimated payment deadlines fall on April 15, June 15, September 15, and January 15, 2027.
If a big settlement lands mid-year, the annualized income installment method on Form 2210 can concentrate your estimated payments in the quarters after you actually received the money.
Do state taxes apply to lawsuit settlements too?
In most states, state income tax generally follows the federal exclusion rules, so a settlement excluded from federal income is usually excluded at the state level too. This is not guaranteed everywhere, since state tax codes can diverge from federal law.
States with no income tax, like Texas and Florida, make this question moot for their residents. States that do tax income typically start their calculation from your federal adjusted gross income, which means a properly excluded federal settlement generally doesn’t get pulled back into state taxable income.
This is not a substitute for checking your specific state’s rules. Not yet confirmed for every state: whether your specific state has any settlement-specific exceptions, since state tax codes vary and change year to year.
What happens next
Now through year end 2026: If you received a settlement this year, gather the settlement agreement and any 1099 forms before tax season starts.
January 2027: Watch for 1099 forms from any payer that issued one, due to recipients by the end of January.
April 15, 2027 (expected): File your 2026 tax return, reporting any taxable settlement income received during 2026.
Ongoing: If you disagree with a 1099 you received for a settlement you believe was tax-free, address it with a tax professional before filing, not after.
Frequently Asked Questions
Do you pay taxes on a settlement for a car accident?
Generally no, if the settlement compensates for physical injuries from the accident.
Punitive damages and interest on the award remain taxable even in a car accident case.
Property damage reimbursement up to your vehicle’s adjusted value is also typically excluded.
Is lawsuit money taxable if it’s for property damage only?
Usually not, up to the adjusted basis of the damaged property.
Any amount paid beyond the property’s adjusted value can become taxable as a gain.
Keep records of the property’s value before the damage occurred.
Do you pay taxes on settlement money from a data breach class action?
Yes, in most cases, since data breach settlements typically compensate for financial harm, not physical injury.
These payouts are usually treated as taxable income and may generate a 1099.
Check the specific settlement notice for how your state or category was classified.
Are lawsuit winnings taxable if paid in installments instead of a lump sum?
Yes, the same tax rules apply whether you receive one lump sum or structured periodic payments.
Each payment is taxed in the year you actually receive it.
A structured settlement doesn’t change whether the underlying claim was physical injury or not.
Do I need to report a personal injury settlement on my taxes at all?
No, if it’s fully excluded, you generally don’t need to report physical injury settlement income on Form 1040.
You should still keep the settlement agreement in your records in case of an IRS inquiry.
Report only the taxable slices, like punitive damages or interest, if any exist.
What if my settlement agreement doesn’t specify what the money is for?
The IRS will look at the underlying complaint and the facts of your case instead.
An unallocated settlement is harder to defend as tax-free if audited.
Ask your attorney to request a clear allocation before you sign, when possible.
Are class action settlements under $600 still taxable?
Yes, taxability does not depend on the size of the payment, small or large.
The $600 figure is only a 1099 reporting threshold for payers, not a tax-free minimum for recipients.
Even a $50 taxable settlement is technically reportable income.
Do you pay taxes on interest earned while a settlement waited to be paid?
Yes, any interest that accrued on your award or settlement is always taxable.
This applies even when the underlying settlement itself is completely excluded from income.
The interest portion typically gets reported separately as interest income.
Check your settlement agreement for how the payment is categorized before you file. If a 1099 doesn’t match what you believe is a tax-free physical injury settlement, get that sorted out with a tax professional before the filing deadline, not after. The single number to calendar: 2026 estimated tax payments are due April 15, June 15, September 15, and January 15, 2027.