409A Deferred Compensation: The 2026 Guide to Nonqualified Plans, Taxes, and Rules
Quick Answer
- 409A deferred compensation means nonqualified plans that let you delay receiving income until a later date, usually retirement.
- If a plan violates 409A rules, you owe income tax on all vested deferrals plus a 20% penalty and interest.
- Deferral elections generally must be made in the tax year before you earn the compensation.
Section 409A of the Internal Revenue Code is the federal law that sets the rules for nonqualified deferred compensation plans. It was added by the American Jobs Creation Act of 2004 and applies to compensation deferred on or after January 1, 2005 . If you are a highly compensated employee participating in an executive retirement plan, a supplemental retirement plan, or a deferred bonus arrangement, 409A likely governs your plan.
The stakes are high. A plan that fails to meet 409A requirements causes immediate income inclusion on all vested deferrals. That means you pay tax now, even though you have not received the money. On top of that, you owe a 20% additional tax and premium interest .
This article explains what 409A covers, the four basic requirements, the six permissible distribution triggers, and what happens if a plan fails. One number that matters: the premium interest rate is the underpayment rate plus one percentage point, calculated as if the deferred amount had been included in income in the year it was first deferred and vested .
The Facts
| Case | Section 409A Deferred Compensation (tax law) |
|---|---|
| Status | Active federal tax law, applies to all nonqualified deferred compensation |
| Fund Size | Not applicable |
| Est. Per Person | Not applicable |
| Claim Deadline | Not applicable |
| Administrator | IRS and Treasury Department |
| Proof Needed | Plan documents, deferral elections, and distribution records |
Is 409A Deferred Compensation Legit or a Scam Risk?
Section 409A is real federal tax law, not a scam. It applies to nonqualified deferred compensation arrangements that private employers, public companies, and tax-exempt organizations use to supplement regular retirement plans.
The scam risk runs in the opposite direction. Some promoters market “409A plans” as tax-free retirement vehicles when they are not. A nonqualified deferred compensation plan is not tax-free. It is tax-deferred. You pay ordinary income tax when the money is distributed.
Another risk is employers that operate plans in violation of 409A. If the plan is written or operated in a way that does not comply, all participants can be affected . That means immediate taxation for everyone in the plan, not just the person who triggered the failure.
You should always verify that your plan has a written document and that deferral elections are properly timed. A plan without a written agreement is not 409A compliant.
Key Takeaway: 409A is legitimate federal law. The real risk is noncompliant plans that trigger immediate taxation and penalties for all participants.
How Much Can You Defer Under 409A?
There is no statutory dollar limit on how much you can defer under a 409A nonqualified deferred compensation plan. Unlike 401(k) plans, which have annual contribution limits, NQDC plans allow deferrals of a percentage of your salary, bonus, or both, with no cap .
The Chicago Deferred Compensation Plan explains that NQDC plans “often supplement an employer’s tax-qualified plan, particularly if highly paid employees are unable to defer the maximum allowed by law into their qualified retirement plan due to nondiscrimination testing failures” .
The amount you can defer is set by the plan document. Some plans allow 1% to 100% of base compensation to be deferred. At YUM! Brands, for example, eligible executives can defer portions of base compensation, bonus compensation, and signing bonus through the company’s deferred compensation plan .
Not applicable: There is no “payout” in the settlement sense. The amount you receive depends on what you defer and how the plan’s investment options perform.
Key Takeaway: There is no dollar cap on 409A deferrals. The limit is set by your employer’s plan document, and you can often defer a large percentage of your compensation.
How Do You Comply With 409A Requirements?
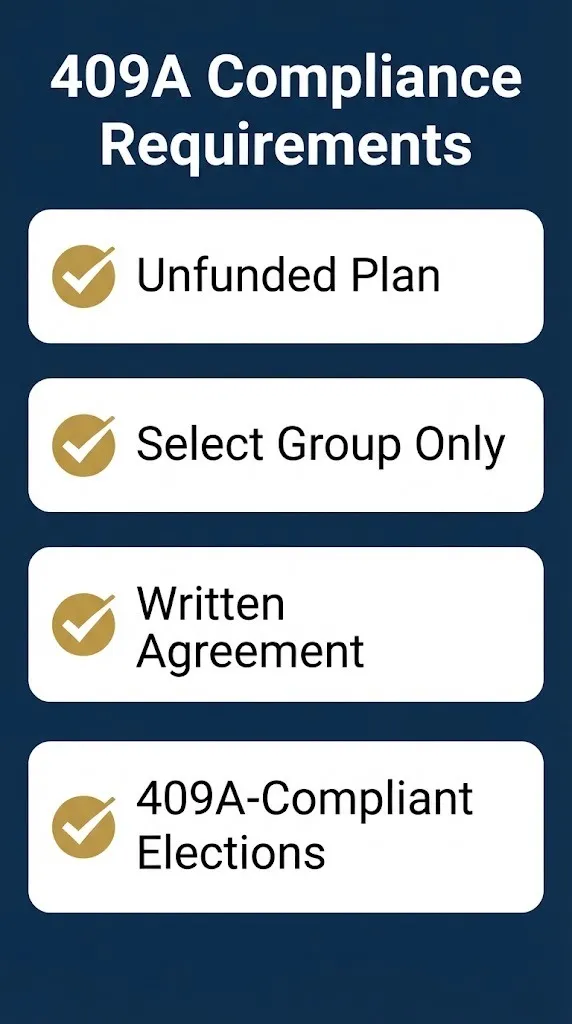
To comply with 409A, a plan must meet four basic requirements: the plan must be unfunded, it must be maintained primarily for a select group of management or highly compensated employees, it must have a written agreement, and it must comply with 409A’s deferral election and distribution rules .
Here is what each requirement means for you:
- Unfunded plan. Assets remain the employer’s property and are subject to creditor claims. You have a contractual promise, not a segregated account .
- Select group. The plan covers only management or highly compensated employees. It is not a broad-based retirement plan.
- Written agreement. The plan must be documented in writing. A handshake deal does not comply .
- 409A compliance. Deferral elections and distributions must follow the rules in the statute and regulations.
Failing the “unfunded” requirement is a common trap. If the employer sets aside assets in your name, those amounts become taxable immediately. Rabbi trusts are permitted, but assets remain subject to employer creditors .
When Can You Elect to Defer Under 409A?
You must make your initial deferral election in the tax year before the year you earn the compensation . For example, to defer a portion of your 2027 salary, you must submit your election by December 31, 2026.
There is one important exception. For “performance-based compensation,” you can make the election no later than six months before the end of the performance period . This exception applies if the compensation is contingent on satisfying organizational or individual performance criteria and the outcome is substantially uncertain at the time the election is made.
The timing rules are strict. A late election is a 409A violation. The plan can be treated as noncompliant, triggering immediate taxation on all vested deferrals.
If you are a nonresident alien participating in a foreign plan, there is a small deferral exception. Amounts deferred up to the section 402(g) limit are excluded from the 409A definition .
Key Takeaway: Deferral elections must generally be made in the prior tax year. Performance-based compensation allows a later election, but only up to six months before the performance period ends.
Reality Check: A 409A deferred compensation plan is not a tax-free retirement account. You defer taxes, not eliminate them. When the money is distributed, you pay ordinary income tax at your then-current rate. If tax rates rise before you take distributions, you could pay more than if you had taken the income earlier. A 409A plan is a tax-timing tool, not a tax-avoidance tool.
What Are the Six Permissible Distribution Triggers Under 409A?
Section 409A permits distributions only upon six specific events: death, disability, separation from service, a change in control, an unforeseeable emergency, or a specified date or event . No other distribution triggers are allowed.
Here is what each trigger means:
| Trigger | Definition |
|---|---|
| Death | Distribution to beneficiary or estate |
| Disability | Unable to engage in substantial gainful activity for 12+ months |
| Separation from Service | Termination of employment, subject to 6-month delay for specified employees |
| Change in Control | Ownership change of 40%+ or change in majority of board |
| Unforeseeable Emergency | Severe financial hardship beyond your control |
| Specified Date/Event | A fixed date or schedule chosen in advance |
The “separation from service” trigger is the most common. But if you are a “specified employee” (generally a key employee or highly compensated executive), distribution cannot begin until at least six months after separation .
The change in control definition is technical. It generally requires a 40% ownership change, a change in majority of the board, or a change in ownership of a substantial portion of assets.
Key Takeaway: 409A permits only six distribution triggers. Any other trigger, such as a “haircut” provision that allows early withdrawal with a penalty, violates the law.
What Happens If a 409A Plan Fails?
If a 409A plan fails to comply with the requirements, all vested deferrals become immediately includible in your gross income. You owe ordinary income tax on amounts you have not received. On top of that, you owe a 20% additional tax on the amount included in income.
You also owe premium interest tax. This is calculated at the underpayment rate plus one percentage point, applied as if the deferred amount had been included in income in the year it was first deferred and vested . The premium interest tax is an additional income tax, not an excise tax or interest on an underpayment .
The penalties can be severe. If a plan is operated in a manner that does not comply, all participants can be affected, not just the one who triggered the failure .
There is a correction program. IRS Notice 2008-113 provides limited relief for certain operational failures, allowing excess amounts to be paid out in the following year without triggering 409A penalties, provided specific conditions are met .
What Happens Next
Annually: Review your 409A plan document and deferral elections. Make sure elections are timely and distribution triggers are properly defined.
Before year-end: Submit deferral elections for the following tax year by December 31. Performance-based compensation elections have different deadlines.
At separation: If you are a specified employee, expect a six-month delay before distributions begin.
Ongoing: Monitor the plan for compliance. Operational failures can trigger penalties for all participants.
Frequently Asked Questions
What is 409A deferred compensation?
Section 409A is a federal tax law governing nonqualified deferred compensation plans. It sets rules for deferral elections, distribution triggers, and penalties for noncompliance.
How much can I defer under a 409A plan?
There is no statutory dollar limit. The amount you can defer is set by your employer’s plan document, often a percentage of salary or bonus.
When must I make a 409A deferral election?
You must generally make the election in the tax year before you earn the compensation. Performance-based compensation allows an election up to six months before the performance period ends.
What happens if a 409A plan is violated?
All vested deferrals become immediately taxable, plus a 20% penalty tax and premium interest. All plan participants can be affected by a plan-level failure.
Can I take an early distribution from a 409A plan?
Only upon the six permissible triggers: death, disability, separation from service, change in control, unforeseeable emergency, or a specified date. “Haircut” provisions are prohibited.
What is a specified employee under 409A?
A specified employee is generally a key employee or highly compensated executive. Distribution to specified employees upon separation must be delayed six months.
Is 409A deferred compensation tax-free?
No. It is tax-deferred. You pay ordinary income tax when the money is distributed, plus any applicable state taxes.
What is a rabbi trust?
A rabbi trust is a funding vehicle for NQDC plans. Assets remain subject to employer creditors, preserving the unfunded status required by 409A.