NY Workers Compensation Insurance 2026: Rates, Requirements, and What Employers Need to Know
Quick Answer
- NY workers’ compensation insurance is mandatory for most employers, covering medical care and lost wages for job-related injuries .
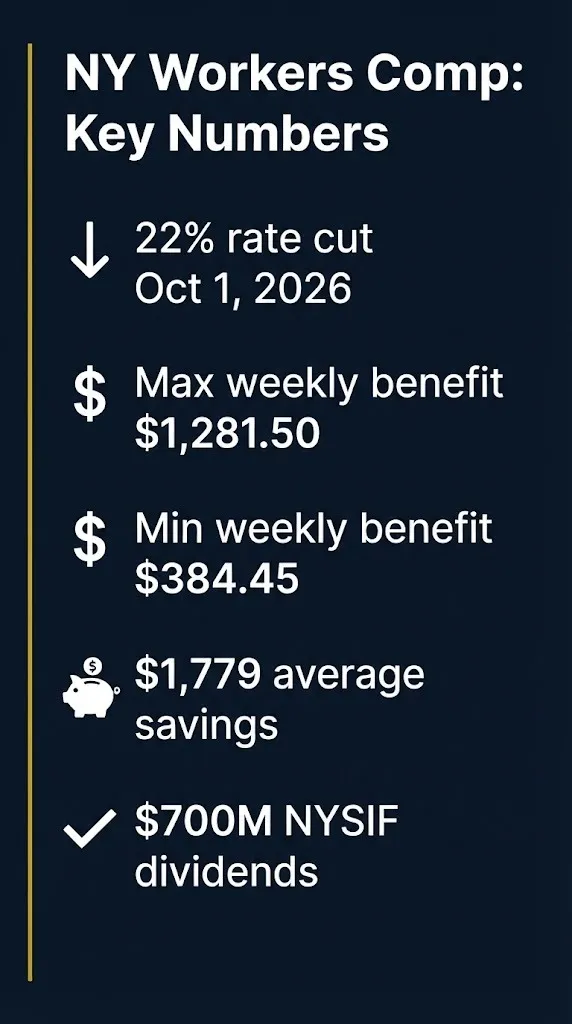
- Premium rates will drop 22% on October 1, 2026, following six years of average annual decreases of 10.3% .
- The maximum weekly benefit for injured workers is $1,281.50 for accidents from July 1, 2026 through June 30, 2027 .
New York workers’ compensation insurance is a state-mandated program that pays for medical treatment and partial wage replacement when employees get hurt or sick because of their job. It’s not optional for most employers. It’s the cost of doing business in New York.
The system is administered by the New York State Workers’ Compensation Board, with insurance policies provided by private carriers, the New York State Insurance Fund, or through self-insurance . Premium rates have been falling steadily since 2020, and a major 22% reduction takes effect October 1, 2026 .
This article breaks down what the insurance covers, what it costs, who needs it, and how the 2026 changes affect both employers and injured workers.
The Facts
| Item | Detail |
|---|---|
| Program | New York State Workers’ Compensation Insurance |
| Administrator | NYS Workers’ Compensation Board |
| Premium Rate Change | 22% average reduction, effective October 1, 2026 |
| Estimated Savings | $1 billion statewide, $1,779 per policyholder average |
| Maximum Weekly Benefit | $1,281.50 (July 1, 2026 – June 30, 2027) |
| Minimum Weekly Benefit | $384.45 |
| Coverage Required | Most employers with employees in New York |
Is NY Workers Compensation Insurance Required for All Employers?
NY workers’ compensation insurance is required for nearly all employers with employees working in New York State. There is no minimum employee count for most businesses .
The law requires coverage from day one of employment. Full-time, part-time, and seasonal workers all count. Even family members working for a business may need coverage unless a specific exemption applies.
Key Employer Requirements:
- Carry insurance through a private carrier, NYSIF, or approved self-insurance
- Post notices about workers’ compensation rights in the workplace
- Report injuries to the insurance carrier within required timeframes
- Maintain records of workplace injuries
Failure to carry coverage can result in criminal penalties, civil fines, and personal liability for workplace injuries. The Workers’ Compensation Board actively investigates non-compliance .
Key Takeaway: Workers’ compensation insurance is not optional in New York. If you have employees, you almost certainly need coverage.
How Much Does NY Workers Compensation Insurance Cost in 2026?
NY workers’ compensation insurance costs vary by industry, payroll, and claims history. The good news for 2026: rates are dropping significantly.
Effective October 1, 2026, the average premium rate will decrease by 22%. That translates to an estimated $1 billion in savings for New York businesses, or about $1,779 per policyholder .
Premium Rate History:
| Period | Average Annual Change |
|---|---|
| 2020-2026 (six years) | 10.3% decrease per year |
| October 1, 2026 | 22% decrease |
The rate reduction is driven by lower claim frequency, improved workplace safety, and a stable loss environment . The Workers’ Compensation Board noted that employer assessment rates have also declined by 37.5% since 2021 .
Actual premiums depend on your classification code, payroll, and experience modification factor. Higher-risk industries like construction pay more than office-based businesses.
How Much Are Workers Compensation Benefits in New York for 2026?
Workers’ compensation benefits pay two-thirds of your average weekly wage, subject to state maximum and minimum limits .
For injuries occurring July 1, 2026 through June 30, 2027, the rates are:
| Benefit Type | Amount |
|---|---|
| Maximum Weekly Benefit | $1,281.50 |
| Minimum Weekly Benefit | $384.45 |
| NYS Average Weekly Wage (2025) | $1,922.25 |
The maximum is calculated as two-thirds of the NYSAWW. The minimum is one-fifth of the NYSAWW or the employee’s actual wages, whichever is less .
Important: The benefit rate is locked in based on your date of injury. If new rates take effect later, your rate doesn’t automatically increase .
What Does NY Workers Compensation Insurance Cover?
NY workers’ compensation insurance covers medical treatment, wage replacement, and rehabilitation for work-related injuries and illnesses.
Covered Benefits:
- Medical care: Doctor visits, surgery, hospitalization, prescriptions, physical therapy, and medical equipment
- Wage replacement: Partial pay for time lost from work, based on two-thirds of average weekly wage
- Permanent disability: Additional compensation for lasting impairments
- Death benefits: Support for surviving dependents and funeral expenses
- Vocational rehabilitation: Retraining if you cannot return to your previous job
Mental health coverage is also included for certain work-related conditions. A 2026 bill passed by the Assembly would expand telehealth access for mental and behavioral health services under workers’ compensation .
Who Can Treat Injured Workers Under NY Workers Compensation?
Currently, most healthcare providers must be specifically authorized by the Workers’ Compensation Board to treat injured workers. That limits options for patients.
Only about 10% of the more than 200,000 eligible providers statewide have completed the authorization process . This creates access problems, especially in rural areas.
Pending Reform: Governor Hochul has proposed universal authorization, which would allow any eligible, licensed healthcare provider in good standing to treat injured workers without separate Board approval. The proposal has broad support from the Board, providers, and injured workers .
If enacted, injured workers could see their own primary care physician or any willing provider for treatment.
What Happens If an Employer Doesn’t Have Workers Compensation Insurance?
Employers without workers’ compensation insurance face serious consequences, and injured workers still have rights.
Penalties for Non-Compliance:
- Criminal misdemeanor charges
- Civil fines and penalties
- Personal liability for medical costs and lost wages
- Potential lawsuits outside the workers’ compensation system
For Injured Workers: If your employer is uninsured, you can still file a claim with the Workers’ Compensation Board. The Board has procedures to handle uninsured employer claims, and benefits may be paid from a special fund.
Reality Check: No one calls you to “process” workers’ compensation benefits for a fee. Filing a claim with the Workers’ Compensation Board is free. The Board does not charge workers to file or pursue claims. Anyone demanding payment to help you get benefits is running a scam.
How Do Employers Get NY Workers Compensation Insurance?
Employers have three main options for obtaining coverage.
Coverage Options:
- Private Insurance Carrier: Shop through a licensed broker or directly with carriers. Rates are filed with the state and subject to approval.
- New York State Insurance Fund (NYSIF): The state’s largest workers’ compensation insurer. NYSIF has distributed more than $700 million in dividends and discounts to policyholders over the past year .
- Self-Insurance: Large employers with sufficient financial resources can apply to self-insure. This requires approval from the Workers’ Compensation Board and posting of security deposits .
Self-insured employers must comply with strict requirements, including excess insurance policies and annual security deposit recalculations .
What Are the 2026 Changes to NY Workers Compensation?
Several significant changes affect the system in 2026.
Key Changes:
- 22% premium rate reduction effective October 1, 2026
- New benefit rates for injuries July 1, 2026 – June 30, 2027: max $1,281.50, min $384.45
- Universal authorization proposal to expand provider access
- Telehealth expansion for mental health services pending in the Senate
- $700 million in NYSIF dividends distributed to policyholders
The Workers’ Compensation Board has also implemented efficiency measures, including mandatory electronic filing for certain forms and expanded virtual hearing options .
Frequently Asked Questions
Is workers compensation insurance required in NY?
Yes. Nearly all employers with employees working in New York must carry workers’ compensation insurance .
How much does NY workers compensation insurance cost in 2026?
Rates will drop an average of 22% on October 1, 2026, saving employers about $1,779 each on average .
What is the maximum weekly benefit for NY workers compensation in 2026?
The maximum is $1,281.50 for injuries occurring July 1, 2026 through June 30, 2027 .
Can I choose my own doctor for workers compensation in NY?
Currently, most providers need Board authorization. Governor Hochul has proposed universal authorization to allow any eligible provider to treat injured workers .
What happens if my employer doesn’t have workers compensation insurance?
You can still file a claim with the Workers’ Compensation Board. Your employer faces penalties, and you may have additional legal options.
Who is the largest workers compensation insurer in NY?
The New York State Insurance Fund (NYSIF) is the state’s largest workers’ compensation insurer .
Does NY workers compensation cover mental health?
Yes, for certain work-related mental health conditions. Pending legislation would expand telehealth access for these services .
How do I apply for workers compensation insurance in NY?
Contact a licensed insurance broker, apply directly to NYSIF, or explore self-insurance if you qualify .
What Should Employers Do About NY Workers Compensation Insurance?
Review your policy before October 1, 2026. The 22% rate reduction should lower your premiums. Confirm your carrier is applying the new rates correctly.
If you’re uninsured, get covered immediately. The penalties for non-compliance are severe, and a single workplace injury could create personal liability.
The most important fact to remember: NY workers’ compensation insurance is mandatory, and rates are dropping significantly on October 1, 2026.