Auto Accident Settlement Loans in 2026: New State Caps, Real Costs, and the Case Cash Lawsuit
Quick Answer
- An auto accident settlement loan is a non-recourse cash advance against a pending car crash claim.
- There is no per-person payout; the cost depends on your contract and your state’s rules.
- The key date is June 17, 2026, when New York’s 25% cap and 10-day cancellation right began.
An auto accident settlement loan is a cash advance against your future car crash settlement, repaid only if you win. The money comes from a private funding company, not a court, and the amount you owe is deducted from your settlement before you see a check .
This affects injured drivers and passengers with active claims, not the general public. The number that matters most is the total repayment figure in your contract, which can climb fast if your case drags on.
This article covers what changed in 2026, the New York cap, the pending Case Cash racketeering suit, real cost ranges, and how to spot a scam. One detail most competitors skip: the New York Times reported in August 2026 that funders bundled these advances into more than two dozen asset-backed securities deals since 2020, raising $2.8 billion .
The Facts
| Item | Verified Detail |
|---|---|
| Product type | Non-recourse advance against a pending injury claim |
| Regulator (New York) | New York Department of Financial Services |
| New York cap | Funded amount plus 25% of proceeds, effective June 17, 2026 |
| New York cancellation | 10 business days after receiving funds, if fully returned |
| Case Cash lawsuit | New York Marine v. Case Cash Funding, No. 1:26-cv-05006 (S.D.N.Y.) |
| Case Cash status | Pending; defense appeared July 9, 2026 |
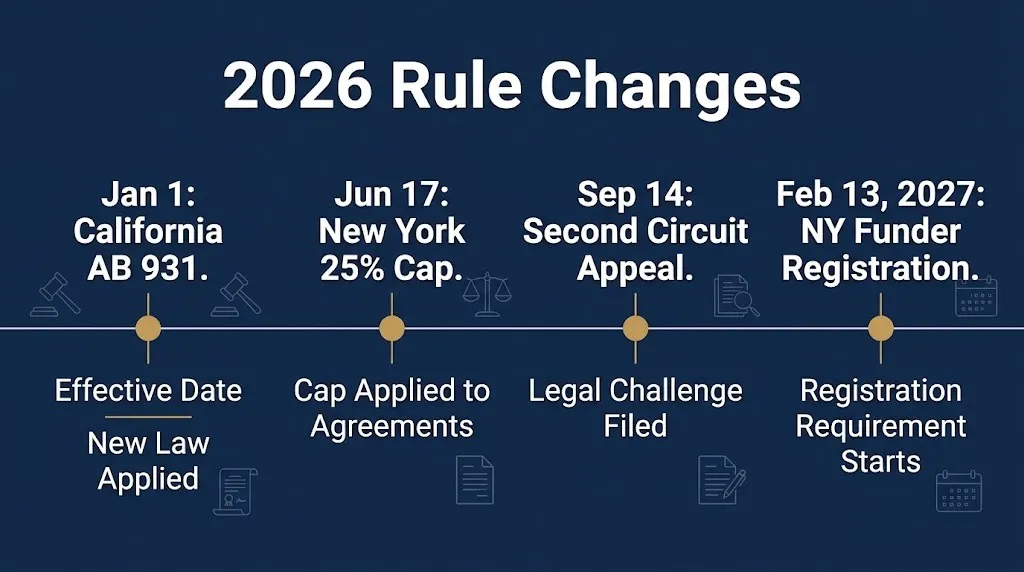
| California law | AB 931, effective January 1, 2026 |
| Kansas law | HB 2518, signed in 2026 |
| Ohio law | HB 105, funder registration requirement |
| Settlement fund | Not applicable; no class settlement exists |
| Claim deadline | Not applicable; this is not a claims process |
Is an auto accident settlement loan legit or a scam?
An auto accident settlement loan is a legitimate financial product in most states, but the industry has a documented scam problem and a pending racketeering lawsuit. The legitimate version is a non-recourse advance from a licensed funder, repaid only from your settlement proceeds .
The scam version looks different. The Better Business Bureau logged a 2025 report of a caller claiming to have a car repair estimate, then pushing a loan and asking for banking information . That is an advance-fee scam, not legal funding.
Real legal funding has a paper trail. You sign a contract, your attorney reviews it, and the funder coordinates with your lawyer . No legitimate funder cold-calls you with a repair estimate and asks for your bank routing number.
The pending Case Cash suit adds a second layer of doubt. New York Marine & General Insurance alleges the company falsely advertised non-recourse advances while controlling medical treatment and lawyer choice, and made usurious loans disguised as advances . Those are allegations, not findings. The case is still open.
How much does an auto accident settlement loan cost in 2026?
An auto accident settlement loan costs whatever your contract says, and in 2026 the range runs from a 25% cap in New York to reported annual fees of 35 to 45 percent elsewhere. There is no standard national rate.
In New York, the law now limits what a funder can collect. For contracts signed on or after June 17, 2026, the funder can take no more than the amount advanced plus 25% of the gross recovery, and never more than the recovery itself .
Outside New York, pricing varies widely. The New York Times investigation, as summarized by the industry-critical group PACT, reported advances carrying 35 to 45 percent annual fees and interest . Funders dispute the predatory label and point to the non-recourse structure.
Not yet determined: There is no public database of average repayment totals for 2026. Your cost depends on your contract, your state, and how long your case runs.
A Canadian case shows how bad the math can get. In McCourt Law Offices v Downes, a plaintiff borrowed $4,000, and by the time her case settled in 2024 she owed $47,007.76, nearly 12 times the principal, because of compounding interest . The court reduced the interest, but the original contract was the problem.
Key Takeaway: The only number that matters in an auto accident settlement loan is the total repayment figure, and in New York that figure is now capped by law.
Who qualifies for an auto accident settlement loan?
You may qualify for an auto accident settlement loan if you have an active injury claim, an attorney representing you, and a case strong enough for a funder to underwrite. Credit score and income do not decide approval .
The core requirements are consistent across funders. You need a pending personal injury claim from a car crash. You need a lawyer, because the funder will not advance money without one reviewing the case . Your claim needs clear liability and enough available insurance coverage to make repayment likely .
Funding companies evaluate the case like an investment. They look at fault, injury severity, medical documentation, and the defendant’s ability to pay . A strong claim with clear fault and solid coverage is more likely to get approved.
Not yet confirmed: Approval rates by funder are not publicly reported. No national data shows what percentage of applicants get funded.
If you do not have a lawyer, you cannot get this product from a reputable funder. That is not a technicality. The attorney review is the main protection you have.
How do you apply for an auto accident settlement loan?
Applying for an auto accident settlement loan takes five steps, starting with a conversation with your attorney and ending with funds deposited after the funder approves your case. Most applications move quickly once the paperwork is in.
- Ask your attorney whether funding makes sense for your case and your finances.
- Gather basic accident information, medical records, and expense documentation.
- Choose a funder and read the contract before signing anything.
- Have your attorney review the contract terms, including the repayment formula.
- Submit the application and let the funder coordinate with your lawyer.
- Receive funds, often within days of approval, and keep a copy of every document.
Your lawyer must confirm in writing that they reviewed the terms with you under New York’s law, and that they received no referral fee from the funder . If a funder will not let your lawyer see the contract, walk away.
What is the Case Cash lawsuit and does it affect borrowers?
The Case Cash lawsuit is a pending federal racketeering case in New York, and it does not currently pay anything to borrowers. It is a business-against-business suit filed by an insurer, not a class action .
New York Marine & General Insurance Company filed the case on June 12, 2026, in the Southern District of New York. The case number is 1:26-cv-05006, before Judge P. Kevin Castel. The complaint alleges that Case Cash falsely advertised non-recourse advances, controlled medical treatment and lawyer choice, and charged usurious rates .
A related case, Union Mutual Fire Insurance Company v. Subin Associates, also named Case Cash as a defendant. The district court docket closed on August 14, 2026, and an appeal opened at the Second Circuit on September 14, 2026 .
Reality Check: No one texts you settlement money from a lawsuit loan. There is no fund, no administrator, and no claim form for people who took an auto accident settlement loan. If someone contacts you offering to “release your Case Cash settlement funds,” it is a scam. The Case Cash case is between insurers and funders, and any money recovered would go to the insurers, not to borrowers.
What new state laws changed auto accident settlement loans in 2026?
New York, California, Kansas, and Ohio all changed their rules for auto accident settlement loans in 2026, and the changes mostly add consumer protections. The rules vary by state, so your contract depends on where you live.
| State | Law | Key Change | Effective Date |
|---|---|---|---|
| New York | Consumer Litigation Funding Act | 25% cap on proceeds, 10-day cancellation, DFS registration | June 17, 2026 |
| California | AB 931 | Consumer Legal Funding Act protections | January 1, 2026 |
| Kansas | HB 2518 | Time-based charges, 10-business-day cancellation | 2026 |
| Ohio | HB 105 | Funder registration with the state | 2026 |
In New York, funders must apply for registration with the Department of Financial Services by February 13, 2027. As of the latest reporting, the DFS registration portal was not yet available .
The New York law covers anyone receiving funding up to $500,000 as a New Yorker . That includes most car accident borrowers. The 10-day cancellation right lets you return the money and cancel the contract if you change your mind.
Key Takeaway: New York’s June 17, 2026 cap is the strongest borrower protection in the country right now, and it applies to contracts signed on or after that date.
How much of your settlement do you actually keep?
The amount you keep from your settlement depends on your loan contract, your attorney fees, medical liens, and case costs, and the loan repayment comes off the top. In a bad outcome, the loan can consume most of your recovery.
Here is the order money leaves a settlement:
- Attorney fees and case costs come first.
- Medical liens and letters of protection get paid next.
- The funding company collects its repayment.
- You receive what remains.
That order is why the loan amount matters so much. A $5,000 advance with 40% annual fees can turn into a $15,000 or $20,000 repayment if your case runs two years. The funder gets paid before you do.
A simple comparison: it is like a store return where the store takes its restocking fee, the manufacturer takes its cut, and you get the remainder. The difference is that your settlement is the only money in the transaction.
Before signing, ask the funder for a table showing what you would owe at three, six, twelve, and twenty-four months. If they will not provide it, that is your answer.
What happens next for auto accident settlement loan borrowers in 2026?
The next stages for auto accident settlement loan borrowers in 2026 are regulatory and legal, not a payout event. No settlement fund exists, and no claim form is coming for people who took these advances.
Expected late 2026: The Case Cash case continues in the Southern District of New York, with a response in opposition to a motion filed October 21, 2026 .
Expected early 2027: New York funders face the February 13, 2027 registration deadline with the Department of Financial Services .
Expected 2027: The Second Circuit appeal in the related Union Mutual case, No. 26-2558, moves forward after the September 14, 2026 notice of appeal .
Ongoing: More than 200 companies asked the federal civil-rules committee in September 2026 to require litigation funding disclosure, and the Western District of Louisiana now requires parties to name their funders .
None of these stages creates money for borrowers. They change the rules funders operate under.
Frequently Asked Questions
Is an auto accident settlement loan a real loan?
No, in most states it is a non-recourse cash advance, not a traditional loan.
Repayment depends on your case outcome, and you owe nothing if you lose .
That structure is why it escapes some state interest-rate caps.
Do I have to pay back an auto accident settlement loan if I lose my case?
No, you generally owe nothing if your case does not produce a settlement or judgment.
The non-recourse structure means the funder takes the risk .
Read your contract to confirm the non-recourse clause before signing.
How much money can I get from an auto accident settlement loan?
Most funders advance a percentage of your expected settlement, often cited as 10% to 20% .
The exact amount depends on your case strength, injuries, and insurance coverage.
There is no guaranteed amount.
Can I get an auto accident settlement loan without a lawyer?
No, reputable funders require an attorney to be involved.
The funder needs your lawyer to review the case and the contract .
A funder willing to skip your lawyer is a red flag.
Does New York’s 25% cap apply to my loan?
It applies to contracts signed on or after June 17, 2026, if you are a New Yorker receiving up to $500,000 in funding .
Contracts signed before that date fall under the old rules.
Check your contract date before assuming the cap protects you.
Is there a class action settlement for people who took auto accident settlement loans?
No, there is no class action settlement and no claim form.
The Case Cash case is an insurer-versus-funder racketeering suit, not a consumer class action .
Anyone offering to file a claim for you is not connected to a real settlement.
What happens if I want to cancel my auto accident settlement loan?
In New York, you have 10 business days after receiving the money to cancel, if you return the full amount .
Kansas gives 10 business days under its law .
Other states vary, so check your contract for the cancellation window.
How long does it take to get funds from an auto accident settlement loan?
Many funders advertise funding within days of approval, and some cite 24 to 48 hours after paperwork is complete .
The timeline depends on how fast your attorney responds and how complex your case is.
No funder can guarantee same-day funding before reviewing your file.
The date to put on your calendar
If you signed a New York contract on or after June 17, 2026, the 25% cap applies, and you have 10 business days to cancel if you change your mind. Outside New York, read the repayment formula before you sign anything, because that number decides how much of your settlement you keep. If a funder will not let your lawyer review the contract, walk away and find another option.