Compensation Math 2026: How Settlement Payouts Are Actually Calculated
Quick Answer
- Compensation math is the calculation method courts and insurers use to turn verified losses into payout amounts.
- Payouts depend on documented damages, liability percentages, policy limits, and the number of approved claimants.
- No universal settlement calculator exists. Each case type has its own formula, tables, and rules.
You probably landed here because a settlement notice promised money and you want to know how they arrived at the number. Or you are negotiating a claim and need to understand what the adjuster is actually doing with your file. Either way, compensation math is not guesswork. It is a system. And once you see the system, you can spot when a number is low, when it is fair, and when you should push back.
This article explains the verified formulas, tables, and methods used in 2026 across class action settlements, workers compensation, and personal injury claims. One fact matters most: every legitimate compensation number traces back to a documented loss, a statutory schedule, or a court-approved formula. If someone cannot show you the math, the number is not real.
What Is Compensation Math in Legal Settlements?
Compensation math is the set of formulas and methods used to calculate how much money a claimant receives in a legal settlement, workers compensation case, or insurance payout. It is the bridge between a loss and a dollar amount.
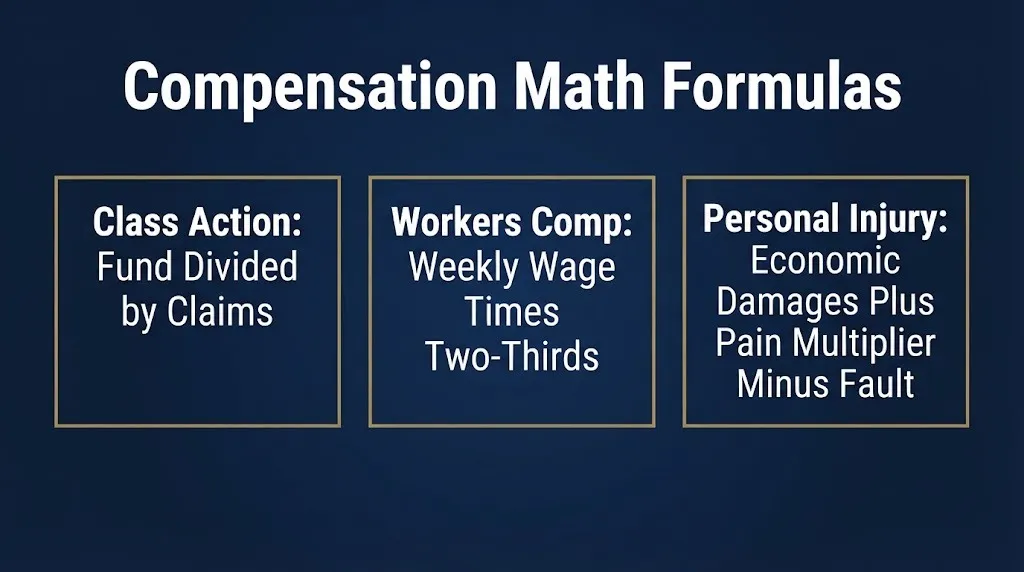
The term is not a single official equation. It is a practice. Different legal areas use different math. A class action settlement divides a fixed fund among approved claimants. Workers compensation uses state-mandated disability schedules. Personal injury settlements multiply medical costs and lost wages, then add pain and suffering.
All compensation math has one thing in common: it starts with a verified loss. Without documentation, there is no calculation. Without a calculation, there is no payout.
Think of compensation math like a recipe. The ingredients are your documented losses. The recipe is the formula your case type requires. The output is the settlement amount.
What Is Compensation in Math Terms for Class Actions?
In class action settlements, compensation math means dividing a fixed settlement fund among every approved claimant. The formula is simple in structure but messy in practice.
The basic class action payout formula is:
Net settlement fund divided by total approved claims equals per-claimant payout.
Here is a verified example. If a settlement fund is $10 million after attorney fees and administration costs, and 100,000 people file valid claims, each claimant gets $100. If 200,000 people file, each gets $50. The pie does not grow. It gets sliced thinner.
That is why class action payouts are often smaller than headlines suggest. The total fund sounds huge. The per-person amount shrinks with every valid claim filed.
Some class actions use tiered systems. Claimants with documented out-of-pocket losses get more than those with no proof. A common structure looks like this:
| Claim Tier | Proof Required | Typical Payout Range |
|---|---|---|
| Tier 1: Documented financial loss | Receipts, police reports, bank statements | $100 to $10,000 or more |
| Tier 2: Time spent dealing with the issue | Time log or sworn statement | $25 to $500 |
| Tier 3: No documented loss | None | $5 to $50 flat payment |
The exact tiers are set in the settlement agreement. They vary by case.
Key Takeaway: In class actions, your payout depends on the fund size, the number of claimants, and your proof tier.
How Do Workers Compensation Payouts Use Compensation Math?
Workers compensation uses state-mandated formulas. The math is not negotiated. It is set by statute.
Most states calculate wage-loss benefits using a simple formula:
Average weekly wage times two-thirds equals weekly benefit amount.
The average weekly wage is usually calculated from your earnings over the 52 weeks before the injury. The two-thirds ratio is common but not universal. Some states use 60 percent or 66.67 percent, depending on the injury type and the worker’s situation.
Permanent impairment awards use a different formula. A doctor assigns an impairment rating. That rating is plugged into a state schedule.
Here is how a permanent partial disability award works in many states:
| Factor | Example |
|---|---|
| Impairment rating | 10 percent of the body as a whole |
| State scheduled weeks for that body part | 300 weeks for an arm |
| Weeks awarded | 10 percent times 300 equals 30 weeks |
| Weekly benefit | $500 |
| Total award | 30 weeks times $500 equals $15,000 |
The numbers vary by state. Some states use a whole-person impairment rating. Others use a body-part schedule. The math is always statutory, not negotiated.
How Do Personal Injury Settlements Calculate Compensation?
Personal injury settlement math starts with economic damages, then adds non-economic damages. Economic damages are documented. Non-economic damages are estimated.
The core formula used by adjusters and attorneys is:
Economic damages plus non-economic damages minus comparative fault equals settlement value.
Economic damages include:
- Medical bills, past and future
- Lost wages and lost earning capacity
- Property damage
- Out-of-pocket costs like prescriptions or travel to appointments
Non-economic damages cover pain, suffering, emotional distress, and loss of enjoyment of life. There is no receipt for pain. Adjusters often estimate it using a multiplier.
The multiplier method looks like this:
| Economic Damages | Multiplier | Non-Economic Estimate | Total Estimate |
|---|---|---|---|
| $20,000 | 1.5 | $30,000 | $50,000 |
| $20,000 | 3.0 | $60,000 | $80,000 |
The multiplier changes based on injury severity, recovery time, and the clarity of liability. A broken arm with a quick recovery might get a 1.5 multiplier. A permanent spinal injury might get a 4 or 5.
Comparative fault then reduces the total. If you are found 20 percent at fault for a car accident, your $100,000 settlement drops to $80,000. Some states use a 50 percent bar rule. If you are 51 percent at fault, you recover nothing.
Key Takeaway: Personal injury math is documented losses plus a pain multiplier, minus your share of fault.
What Is the Difference Between Compensatory and Punitive Damages in Compensation Math?
Compensatory damages make you whole. Punitive damages punish the defendant. They use different math entirely.
Compensatory damages are calculated from your actual losses. Medical bills, lost wages, property damage, and pain and suffering all fall under compensatory damages. The formula is loss-based.
Punitive damages are not tied to your loss. They are tied to the defendant’s conduct. Courts look at how bad the conduct was and how much money the defendant has. The formula is punishment-based.
Punitive damages are rare in settlements. Most cases settle for compensatory damages only. When punitive damages are awarded at trial, they can be large, but appeals often reduce them.
The U.S. Supreme Court has suggested that punitive damages should rarely exceed a single-digit ratio to compensatory damages. A 4-to-1 ratio is often cited as a constitutional guidepost. That means $100,000 in compensatory damages might support up to $400,000 in punitive damages, though lower ratios are more common.
How Are Attorney Fees Factored Into Compensation Math?
Attorney fees come out before you get paid. That changes your net payout, and the math is easy to miss if you are not looking.
In most personal injury cases, the fee is a contingency percentage. The standard is 33 percent if the case settles before trial. It often rises to 40 percent if the case goes to trial or appeal.
Here is how the deduction works:
| Settlement Amount | Attorney Fee (33%) | Net to Client |
|---|---|---|
| $50,000 | $16,500 | $33,500 |
| $100,000 | $33,000 | $67,000 |
| $250,000 | $82,500 | $167,500 |
Costs are deducted separately. Filing fees, expert witness fees, and deposition costs come out of your share in most fee agreements. Always ask for a written breakdown before signing.
In class actions, attorney fees are typically awarded by the court from the settlement fund. The fee request is usually 25 to 33 percent of the total fund. Class members see the fee request in the settlement notice. You have the right to object if you think the fee is too high.
Reality Check: No legitimate settlement asks you to pay a fee upfront to receive your money. Contingency fees come from the settlement itself. Anyone asking for a processing fee, a tax payment, or a “release fee” before paying you is running a scam.
How Do Settlement Calculators Work?
Settlement calculators are online tools that estimate your payout using basic inputs. They are rough guides, not guarantees.
Most personal injury settlement calculators ask for:
- Medical bill total
- Lost wage amount
- Injury type and severity
- State where the injury occurred
- Whether liability is clear or disputed
The calculator then applies a multiplier and a fault adjustment. It produces an estimated range.
The problem is that no calculator knows the specifics of your case. It does not know the insurance policy limits, the defendant’s assets, or your doctor’s credibility. A calculator might estimate $80,000. The actual offer might be $15,000 because the policy limit is $25,000.
Use settlement calculators for education, not decisions. They help you understand the formula. They do not replace a real evaluation of your file.
What Is the Formula for Lost Wages in Compensation Math?
Lost wages are calculated by multiplying your daily or weekly pay by the number of days or weeks you missed work.
Daily wage times missed workdays equals lost wages.
For salaried workers, the formula is:
Annual salary divided by 260 workdays equals daily rate. Daily rate times missed days equals lost wages.
For hourly workers, the formula is:
Hourly rate times hours missed equals lost wages.
If you missed overtime, commissions, or bonuses, those may be included if you can document them. The key is proof. Pay stubs, tax returns, and employer letters all work.
Future lost earning capacity uses a different calculation. An economist or vocational expert estimates your lost future income. That number is then reduced to present value using a discount rate, typically 3 to 5 percent per year.
How Does Comparative Negligence Affect Compensation Math?
Comparative negligence reduces your payout by your percentage of fault. The math is straightforward but painful.
Gross settlement value times your fault percentage equals your deduction. Gross settlement minus deduction equals your net recovery.
Here is a table showing how fault changes a $100,000 gross settlement:
| Your Fault | Deduction | Net Recovery |
|---|---|---|
| 0 percent | $0 | $100,000 |
| 10 percent | $10,000 | $90,000 |
| 25 percent | $25,000 | $75,000 |
| 50 percent | $50,000 | $50,000 |
| 51 percent (in 50 percent bar states) | Full bar | $0 |
Pure comparative fault states allow recovery even at 99 percent fault, but the amount shrinks accordingly. Modified comparative fault states bar recovery at 50 or 51 percent. Contributory negligence states, like Alabama and Maryland as of recent law, can bar recovery at just 1 percent fault.
Key Takeaway: Fault allocation is not a side issue. It can zero out your entire claim in some states.
How Are Pain and Suffering Damages Calculated?
Pain and suffering damages are calculated using one of two methods: the multiplier method or the per diem method. Neither is precise. Both are accepted.
The multiplier method takes your economic damages and multiplies them by a number between 1.5 and 5. More severe injuries get higher multipliers.
The per diem method assigns a daily dollar amount to your pain. It then multiplies that rate by the number of days you experienced pain.
Here is a comparison:
| Method | Formula | Example |
|---|---|---|
| Multiplier | Economic damages times 1.5 to 5 | $30,000 times 3 equals $90,000 total |
| Per diem | Daily rate times pain days | $200 times 180 days equals $36,000 in pain damages |
The per diem method often produces smaller pain awards than the multiplier method. Adjusters like it. Attorneys for injured people often prefer the multiplier.
Insurance companies do not use a fixed formula for pain and suffering. They argue it down. The final number is negotiated, not calculated to the penny.
What Is the Role of Policy Limits in Compensation Math?
Policy limits cap your recovery, no matter how large your documented losses are. This is the hardest reality in compensation math.
If the at-fault driver has a $25,000 bodily injury policy, that is the most the insurer will pay for your injuries. Your medical bills might be $80,000. Your pain and suffering might be worth $60,000. The policy limit is still $25,000.
Your options in that situation are limited. You can seek underinsured motorist coverage from your own policy. You can pursue the defendant’s personal assets, but most people have none. You can accept the policy limit and move on.
A settlement calculator cannot see policy limits. That is why calculated estimates often exceed actual payouts. The math is not wrong. The available money is the constraint.
How Does Compensation Math Work in Wrongful Death Cases?
Wrongful death compensation math combines economic and non-economic damages, with the family as the claimant.
Economic damages include:
- Funeral and burial expenses
- Medical bills before death
- Lost income the deceased would have earned
- Loss of household services
Non-economic damages include:
- Loss of companionship and society
- Mental anguish of surviving family members
- Loss of guidance and support
Many states cap non-economic damages in wrongful death cases. Caps vary widely. Some states have no cap. Others cap non-economic damages at $250,000 to $750,000, depending on the case type and the defendant.
The lost income calculation uses the deceased person’s earnings history, work-life expectancy, and a discount rate to present value. An economist usually provides this calculation.
How Are Structured Settlements Calculated?
A structured settlement pays money over time instead of in one lump sum. The math compares the present value of future payments to the lump sum option.
The insurance company or defendant funds an annuity. The annuity makes scheduled payments. The total of those payments usually exceeds the lump sum offer, because the money earns interest over time.
Here is a simple comparison:
| Option | Total Paid | Timing |
|---|---|---|
| Lump sum | $200,000 | Today |
| Structured | $320,000 | $40,000 per year for 8 years |
The structured option pays more in total. The lump sum pays less but gives you control now. Neither is automatically better. The right choice depends on your age, tax situation, and financial needs.
Key Takeaway: Structured settlements trade a smaller amount now for a larger total over time. The math favors the structured option on paper.
What Is the Most Common Mistake in Compensation Math?
The most common mistake is using the wrong base number. People calculate from the settlement total instead of the net amount after fees and costs.
A $100,000 settlement with a 33 percent attorney fee and $5,000 in costs leaves $62,000. Not $100,000. Then medical liens may reduce it further. A hospital lien, a health insurance subrogation claim, or a workers compensation lien can eat another 20 to 50 percent.
Here is a realistic payout breakdown:
| Item | Amount |
|---|---|
| Gross settlement | $100,000 |
| Attorney fee (33%) | -$33,000 |
| Case costs | -$5,000 |
| Medical liens | -$20,000 |
| Net to client | $42,000 |
That is a big difference from the headline number. Always ask for a written settlement statement before you sign anything.
What Happens Next After a Settlement Is Calculated?
Once the math is done and both sides agree, the settlement moves through a closing process. It is slower than most people expect.
Typical settlement timeline:
- Settlement agreement signed: Day 1
- Release and lien resolution: 2 to 6 weeks
- Court approval (if required): 30 to 90 days
- Check issued by insurer or administrator: 2 to 4 weeks after approval
- Funds deposited in your account: 1 to 2 weeks after check clears
The total process usually takes 30 to 120 days after signing. Complex cases with multiple liens or court approval requirements take longer.
For class action settlements, the process is even slower. After final approval, there may be an appeal period. Payments often go out months after the final hearing.
Frequently Asked Questions
What is compensation math?
Compensation math is the formula-driven method used to calculate legal settlement and insurance payout amounts.
It starts with documented losses and applies case-specific rules.
What is compensation in math terms?
In math terms, compensation is a strategy where you adjust one number to make a calculation easier, then adjust the result back.
In legal settlements, compensation math means converting verified losses into a dollar payout.
How do I calculate my settlement amount?
Start with your documented economic damages.
Add a pain and suffering estimate using a multiplier or per diem method.
Subtract your percentage of fault and any attorney fees, costs, and liens.
What is the average payout for a personal injury settlement?
No verified national average exists because cases vary too widely.
Most personal injury settlements range from a few thousand dollars to six figures depending on injuries, insurance, and liability.
How much do lawyers take from a settlement?
Most personal injury lawyers take 33 percent of the gross settlement before trial.
The percentage often rises to 40 percent if the case goes to trial.
Can I calculate my own workers compensation payout?
Yes, if you know your average weekly wage and your state’s compensation rate.
The basic formula is average weekly wage times two-thirds, capped by state maximums.
What is the difference between gross and net settlement?
Gross settlement is the total amount the defendant pays.
Net settlement is what you receive after attorney fees, costs, and liens are deducted.
Is a settlement calculator accurate?
No calculator is fully accurate for your specific case.
Use calculators to understand the formula, not to set your expectations.
The single most important number in any settlement is not the gross amount. It is the net amount you actually receive after fees, costs, liens, and deductions. Always ask for a written breakdown before you sign.
If a settlement notice promises money, read the math. If the math is not explained, ask for it. Legitimate settlements can show you exactly how your payout was calculated. If they cannot, that is a red flag.