Wells Fargo Settlement 2026: What You Need to Know Before Filing a Claim
Quick Answer
- Is it real? Yes. Wells Fargo reached a verified $3.7 billion settlement with the CFPB covering millions of harmed customers.
- How much could you get? Amounts vary widely by account type and harm. Some customers may receive hundreds to thousands of dollars.
- Key deadline: Eligible customers are contacted directly. No public claim form exists for the CFPB settlement.
Wells Fargo has been at the center of one of the largest consumer banking enforcement actions in American history. The Consumer Financial Protection Bureau ordered the bank to pay $3.7 billion in December 2022. That total includes $2 billion in direct consumer redress and a $1.7 billion civil penalty paid to the CFPB.
If you held a Wells Fargo mortgage, auto loan, checking account, or savings account between approximately 2011 and 2022, you may qualify for a direct payment. The bank is required to contact eligible customers directly. Payments are ongoing in 2026 as the remediation program works through millions of accounts.
This report covers what the $3.7 billion settlement covers, who the CFPB determined was harmed, how remediation payments are calculated, and what you should do if you think you were missed. One verified detail that surprises many readers: there is no single public claim form for the main CFPB settlement.
The Facts
| Detail | Information |
|---|---|
| Case | CFPB v. Wells Fargo Bank, N.A. (Consent Order) |
| Status | Active Remediation and Paying |
| Fund Size | $3.7 billion total ($2 billion consumer redress) |
| Est. Per Person | Varies by harm category, not yet publicly tiered |
| Claim Deadline | No public claim form. Eligible customers contacted directly. |
| Administrator | Wells Fargo under CFPB supervision |
| Proof Needed | Bank notifies you. Keep old account records. |
Is the Wells Fargo Settlement 2026 Real or a Scam?
The Wells Fargo settlement 2026 is real. It traces directly to a December 2022 Consent Order signed by the Consumer Financial Protection Bureau and Wells Fargo Bank, N.A. This is a federal enforcement action, not a private lawsuit filed by attorneys. The CFPB is the government agency created specifically to protect bank customers from exactly this kind of institutional misconduct.
Scammers have flooded the internet with fake “claim forms” and text messages promising fast Wells Fargo payouts. The critical fact to know is this: the legitimate CFPB settlement does not use a third party website for claims. Wells Fargo is required to identify and contact harmed customers from its own internal records.
If someone sends you a text saying you have a Wells Fargo claim waiting, and asks for your Social Security number or bank login, that is a fraud attempt. Report it to the CFPB directly.
- Confirmed real: CFPB Consent Order, December 2022
- Confirmed fund: $3.7 billion total
- Confirmed method: Bank contacts you, not the other way around
- Not confirmed: Any “$5,000 flat payment” claim circulating on social media
What Is the Wells Fargo $5,000 Settlement Claim?
The “Wells Fargo $5,000 settlement” is not a verified, confirmed payout tier from any official court or regulatory document. This figure circulates heavily on social media, Reddit, and third party claim websites. None of these sources trace back to a specific court order or CFPB consent decree that guarantees $5,000 to every customer.
What is confirmed is that individual payments under the CFPB settlement vary significantly. Some auto loan customers received amounts in the hundreds of dollars for wrongful repossession fees. Some mortgage customers received thousands for illegal fees and forced insurance. There is no flat $5,000 amount confirmed for all customers.
Anyone selling you on a guaranteed $5,000 check is either misinformed or attempting to profit from your confusion. The actual amounts depend on which product harmed you, how long the harm lasted, and how Wells Fargo’s internal remediation model calculates your specific loss.
Not yet confirmed: Any official tier list showing “$5,000 per person” from the CFPB or any court record.
Wells Fargo Settlement Eligibility: Who May Qualify?
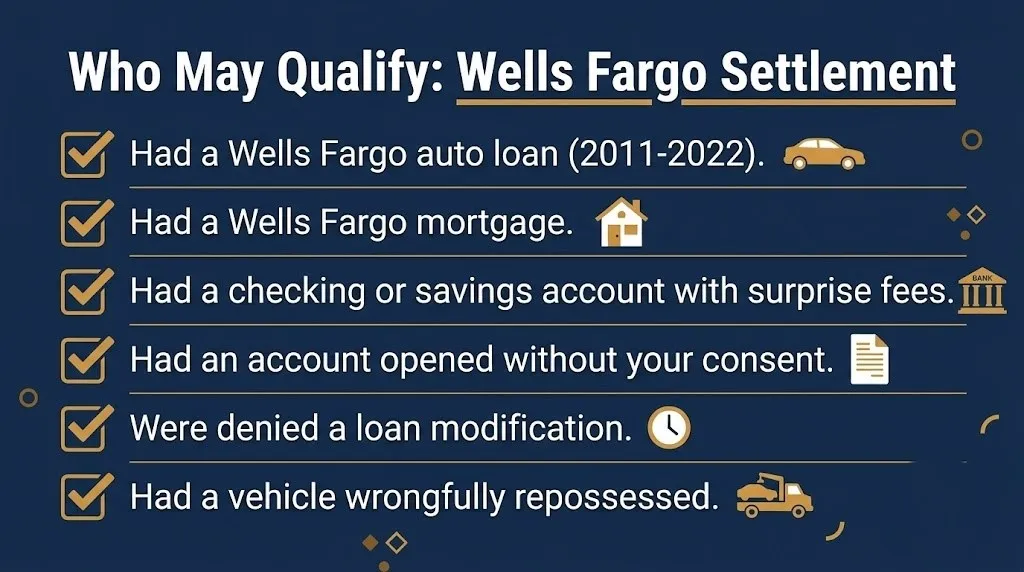
Wells Fargo settlement eligibility is determined by the type of product you held and the specific harm you experienced. The CFPB Consent Order identified seven major categories of consumer harm. You may qualify if you had one of the following products and experienced the listed problem.
| Product Type | Alleged Harm |
|---|---|
| Auto Loans | Wrongful repossession, GAP insurance refunds denied |
| Mortgage Loans | Illegal fees, loan modification denials, forced-placed insurance |
| Checking Accounts | Surprise overdraft fees, unauthorized account openings |
| Savings Accounts | Unexpected fees, account freezing without proper notice |
| Online Bill Pay | Payments processed incorrectly, fees charged in error |
| Consumer Deposits | Accounts opened without consent (fake accounts scandal) |
| Personal Loans | Payment processing errors, improper fees |
You do not need to still be a Wells Fargo customer to qualify. Former customers who closed accounts years ago are included if the harm occurred during the covered period, which runs roughly from 2011 through 2022.
How Much Is the Wells Fargo Settlement Check Amount Per Person?
The Wells Fargo settlement check amount per person is not a single fixed number. Payments are calculated individually based on the type and duration of harm. The CFPB’s $2 billion redress pool is divided across millions of customers. That means the average individual payment is likely in the range of a few hundred to a few thousand dollars.
Wells Fargo has confirmed sending direct payments to customers in several harm categories. Auto loan customers who had their vehicles wrongfully repossessed typically receive the highest amounts. Mortgage customers who were denied loan modifications may also receive significant payments. Customers harmed only by a single incorrect overdraft fee may receive smaller amounts.
What we know for certain:
- Total consumer redress fund: $2 billion
- Civil penalty to CFPB: $1.7 billion
- Payment method: Direct check or account credit from Wells Fargo
- Individual amount: Depends on your specific harm. Not yet publicly tiered in a confirmed schedule.
Key Takeaway: The “$5,000 Wells Fargo settlement” figure is not confirmed by any official document. Real payouts vary by harm type, and Wells Fargo contacts eligible customers directly.
Wells Fargo Settlement Details: What the CFPB Actually Found
The Wells Fargo settlement details go back years of documented misconduct. The CFPB found that Wells Fargo systematically harmed customers across multiple product lines. This was not a single incident. The regulator documented years of illegal behavior that enriched the bank at customer expense.
In auto lending, Wells Fargo charged customers for add on products like GAP insurance, then failed to issue refunds when loans were paid off early. In some cases, the bank repossessed cars from borrowers who were actually current on their payments. These were not isolated errors. CFPB investigators found systemic patterns across millions of accounts.
In mortgages, Wells Fargo charged improper fees during the pandemic forbearance period. It also wrongly denied loan modification requests, which led some customers directly into foreclosure. The CFPB called this “illegal activity” rather than accidental processing mistakes.
- Auto loans affected: Millions, including wrongful repossessions
- Mortgage customers harmed: Tens of thousands, some lost homes
- Fake accounts: Hundreds of thousands of unauthorized accounts opened
- Overdraft fees: Millions of illegal charges across consumer deposits
Wells Fargo Apex Triangle Settlement: Is This Separate?
The “Wells Fargo Apex Triangle settlement” is a term circulating online that does not correspond to a confirmed, named federal case or official settlement document. As of June 2026, this phrase appears primarily in social media posts and third party claim aggregator websites.
It is possible this refers to a private class action lawsuit filed in a specific district, or it may be a misidentified version of an existing settlement. However, no official court record, CFPB press release, or state attorney general announcement confirms an “Apex Triangle” settlement by that exact name.
If you saw this term in a Facebook post, YouTube video, or via a text message, treat it with caution. The verified and confirmed Wells Fargo settlement in force right now is the December 2022 CFPB Consent Order.
Not yet confirmed: Any settlement specifically named “Wells Fargo Apex Triangle” from a verified court or regulatory source. Check the official CFPB website for verified enforcement actions.
How to File a Wells Fargo Settlement Claim
Filing a formal claim for the primary CFPB settlement works differently than a typical class action. You do not need to find a website and enter your information unprompted. Wells Fargo is required by the Consent Order to review its own internal records and identify harmed customers automatically.
That said, there are steps you can take to protect yourself and ensure you are not missed.
- Gather your old Wells Fargo statements. Collect statements from 2011 to 2022 for any account.
- Log in to your Wells Fargo online account. Look for any notices or messages about remediation payments.
- Check your mail. Wells Fargo sends physical checks and letters to addresses on file.
- Update your contact information. If you moved since closing your account, contact Wells Fargo’s remediation line.
- Call Wells Fargo customer service. Ask specifically about the CFPB remediation program and whether your account is flagged.
- File a complaint with the CFPB. If you believe you were harmed but have not heard anything, file at the CFPB’s official complaint portal.
- Contact your state Attorney General. Several states ran parallel investigations and have separate consumer protection avenues.
- Do not pay a third party. No legitimate claim helper is required. This process is free.
Think of it like a manufacturer’s recall. The car company finds the affected vehicles in its own records and contacts the owner. You do not need a lawyer to get your recall repair done. The Wells Fargo remediation works the same way.
Reality Check: No one will text you a link to collect your Wells Fargo settlement money. The bank sends physical checks or direct account credits. Any website charging a fee to “file your Wells Fargo claim” is unnecessary and potentially fraudulent. Filing through the official CFPB complaint process costs nothing.
Wells Fargo Settlement Website: Where to Get Official Information
The Wells Fargo settlement website does not exist as a standalone, dedicated claim portal the way typical class action settlements do. Official information lives in two places: the Consumer Financial Protection Bureau’s official newsroom and Wells Fargo’s own dedicated remediation pages.
The CFPB published its full Consent Order publicly. That document runs over 80 pages and details exactly which products were affected and what remediation is required. Any website other than the official CFPB domain or WellsFargo.com claiming to be the “official settlement site” should be treated as suspicious.
Official sources to trust:
- CFPB official website: The Consent Order and press release are published there.
- WellsFargo.com: The bank has a dedicated “Consumer Remediation” section.
- State Attorney General websites: Several states list parallel settlement details.
- CFPB Complaint Portal: For customers who believe they were missed.
Key Takeaway: There is no single standalone “Wells Fargo settlement website” for filing a claim. Eligible customers are contacted by the bank directly, and official information lives on the CFPB’s own domain.
Wells Fargo Bank Settlement 2026 Details: Separate Class Actions
Beyond the CFPB Consent Order, multiple private class action lawsuits against Wells Fargo are active or recently resolved in 2026. These are separate from the federal enforcement action and cover different customer groups.
One notable private class action covers Wells Fargo’s Zelle-related fraud disputes. Customers who reported unauthorized Zelle transactions and were denied refunds filed suit. The status of that case as of mid 2026 is active litigation. No settlement amount is confirmed yet.
A separate class action covers Wells Fargo’s practice of charging multiple non sufficient funds fees on the same transaction. Several state courts have allowed these cases to proceed. Amounts and deadlines for these cases are not yet confirmed.
| Case Type | Status | Confirmed Amount |
|---|---|---|
| CFPB Consent Order | Active Remediation | $3.7 billion total |
| Zelle Fraud Class Action | Active Litigation | Not yet confirmed |
| NSF Fee Class Action | Active Litigation | Not yet confirmed |
| Auto Loan Overcharge Cases | Some settled, some active | Varies by state |
| Mortgage Modification Cases | Active Remediation | Part of CFPB order |
Wells Fargo Settlement Payout Date: When Will You Get Paid?
Wells Fargo settlement payout dates are staggered because remediation is happening in waves across different product categories. The CFPB Consent Order required Wells Fargo to begin paying customers within a set timeframe after the December 2022 agreement. Payments started going out in 2023 and are continuing through 2026.
If you have not received payment yet, that does not mean you were skipped. Wells Fargo is working through its largest harm categories first. Auto loan and mortgage customers received earlier waves. Smaller harm categories, like individual overdraft fee refunds, may come later in the remediation cycle.
There is no single confirmed “pay by” date that covers every eligible customer. The CFPB monitors compliance and can penalize Wells Fargo if remediation stalls.
- Auto loan payments: Started going out in 2023
- Mortgage remediation: Ongoing through at least 2026
- Deposit account refunds: Ongoing in 2025 and 2026
- Overall completion date: Not publicly confirmed, still under CFPB supervision
Wells Fargo 2026 Settlement: What Is Different This Year?
The Wells Fargo 2026 settlement landscape is different from prior years because the bank is now under active regulatory supervision. The Federal Reserve has maintained a separate asset cap on Wells Fargo since 2018. That cap limits how large the bank can grow until regulators confirm it has fixed its risk and compliance systems.
In 2026, the Fed’s asset cap remains a live issue. If regulators determine Wells Fargo has fully remediated its consumer harm, the cap may be lifted. That is a major financial incentive for the bank to pay customers quickly and completely. The bank’s stock price and growth plans depend on full compliance.
Additionally, several state attorneys general have launched separate investigations in 2025 and 2026 targeting Wells Fargo’s mortgage servicing practices. California, New York, and Illinois have each issued inquiry letters. These may produce additional state level settlements with their own claim processes.
- Federal Reserve asset cap: Still in place as of June 2026
- State AG investigations: Active in at least three states
- CFPB monitoring: Ongoing compliance review in 2026
Key Takeaway: Wells Fargo’s incentive to pay customers quickly is unusually high in 2026 because full remediation is tied directly to lifting the Federal Reserve’s asset cap on the bank.
Wells Fargo Class Action Settlement: How It Differs From the CFPB Order
A Wells Fargo class action settlement is a private legal agreement reached through civil litigation, not a government enforcement action. These two types of cases run on different tracks and have different rules for how you get paid.
In a class action, a named plaintiff sues on behalf of a group. Lawyers negotiate a deal. A judge approves it. A settlement administrator opens a claim portal. You file online. The CFPB Consent Order works the opposite way. The government agency investigated, found violations, and ordered the bank to pay. The bank identifies victims from its own records.
You may be eligible for both a CFPB remediation payment and a separate class action payout if different harms apply to you. These are not mutually exclusive. Accepting one does not automatically cancel your right to the other, though class action opt out rules and release language can be complicated.
- CFPB settlement: Government ordered, no claim form, bank contacts you.
- Class action: Private lawsuit, requires you to file a claim when notice is sent.
- State AG settlements: Varies by state, may require a separate claim.
Why Did Wells Fargo Pay $3.7 Billion?
Wells Fargo paid $3.7 billion because the CFPB documented years of systematic, intentional consumer harm. This was not the first time the bank faced consequences. In 2016, regulators fined Wells Fargo $185 million for the fake accounts scandal, where employees opened roughly 3.5 million unauthorized accounts to hit sales targets.
The 2022 CFPB action was far larger because it covered a much broader range of products and a longer time period. The CFPB found that the problems were not isolated to rogue employees. They were embedded in the bank’s business practices and management structures.
CFPB Director Rohit Chopra said at the time that Wells Fargo was a “repeat offender” and that the settlement was designed to ensure the bank could not simply treat fines as a cost of doing business. The $1.7 billion civil penalty, paid to the CFPB, reflects that deterrence goal.
- 2016 fake accounts fine: $185 million
- 2022 CFPB Consent Order: $3.7 billion
- Underlying issue: Systemic consumer harm across multiple product lines
- CFPB characterization: “Repeat offender” with embedded misconduct
What Happens Next
- Ongoing, 2026: Wells Fargo continues sending remediation checks to eligible auto loan and mortgage customers under CFPB supervision.
- Mid 2026: State attorneys general in California, New York, and Illinois are expected to release findings from their separate Wells Fargo mortgage servicing inquiries.
- Late 2026 (Expected): Federal Reserve review of Wells Fargo’s compliance progress could determine whether the 2018 asset cap is lifted.
- TBD: Private class action lawsuits covering Zelle fraud and NSF fees are expected to reach settlement or trial dates. No confirmed timeline yet.
- TBD: If new state-level settlements are reached, separate claim portals may open with their own deadlines.
Frequently Asked Questions
Is the Wells Fargo $5,000 settlement real?
No verified official document confirms a flat $5,000 payment to all Wells Fargo customers.
Individual payouts vary by harm type and are calculated from internal bank records.
This figure appears to come from social media posts, not court or CFPB records.
Do I need to file a claim to get a Wells Fargo settlement payment?
For the main CFPB settlement, no. Wells Fargo identifies eligible customers from its own records.
For private class action settlements, you will need to file when a notice is sent to you.
Watch your mail and email for official notices with a case number and Notice ID.
How do I know if Wells Fargo owes me money?
Check your Wells Fargo online account for any remediation notices or credits.
Contact Wells Fargo’s customer service line and ask specifically about the CFPB remediation program.
If you believe you were harmed and have not heard anything, file a complaint with the CFPB.
When will Wells Fargo send settlement checks in 2026?
Payments are already going out in waves. Auto loan and mortgage payments started in 2023.
Remediation is continuing through 2026 across deposit and loan product categories.
A single confirmed final payment date has not been publicly announced.
Is the Wells Fargo settlement the same as the fake accounts lawsuit?
No. The fake accounts scandal from 2016 was a separate enforcement action.
The 2022 CFPB settlement is larger and covers auto loans, mortgages, and checking accounts.
Some customers may be covered under both enforcement actions for different harms.
Can I still get paid if I closed my Wells Fargo account years ago?
Yes. The CFPB settlement covers former customers harmed between approximately 2011 and 2022.
Wells Fargo is required to use last known contact information to reach you.
Update your address with Wells Fargo or file a CFPB complaint if you think you were missed.
What is the Wells Fargo Apex Triangle settlement?
This name does not match any confirmed federal court case or CFPB enforcement action as of June 2026.
It appears in social media posts and third party claim sites without verifiable source documents.
Treat any website using this name with caution and verify through the official CFPB website only.
Will accepting a Wells Fargo payment stop me from joining a class action?
It depends on the specific settlement release language you sign.
Some remediation payments require you to waive further claims for the same harm.
If you receive a payment offer with a release form, read it carefully before signing.
The Wells Fargo remediation process is real, ongoing, and does not require you to pay anyone or sign up on a third party website. Your best move right now is to update your contact information with Wells Fargo and file a CFPB complaint if you believe you were harmed and have not heard anything.
Keep your old Wells Fargo statements from 2011 through 2022. They are your evidence if any dispute arises. The most important date in 2026 is not a claim deadline. It is the ongoing CFPB supervision window that keeps Wells Fargo legally obligated to keep paying.