Oasis Settlement Loans: 2026 Update on Pre-Settlement Funding Claims and Lawsuits
Quick Answer
- Oasis settlement loans are real financial products, not a lawsuit settlement you can claim.
- No class action settlement against Oasis Financial has been confirmed as of early 2026.
- If you have an existing Oasis funding agreement, review your contract terms directly for payoff obligations.
If you searched “oasis settlement loans” hoping to find a class action payout, you likely landed on the wrong idea. Oasis Financial is a company that provides pre-settlement funding, sometimes called lawsuit loans or settlement advances. It is not a settlement fund paying consumers. This matters because the language around “settlement loans” confuses many people searching for claim money.
That said, there are active legal conversations about how companies like Oasis charge interest and fees. Several state legislatures and consumer protection agencies have looked at whether pre-settlement funding contracts should be regulated more tightly. Here is what is actually verified, what is still pending, and what to do if you have an Oasis contract or are considering one.
The Facts
| Item | Detail |
|---|---|
| Company | Oasis Financial (Oasis Legal Finance) |
| Status | Active, no confirmed settled class action as of February 2026 |
| Fund Size | None confirmed against Oasis |
| Est. Per Person | Not applicable, no confirmed settlement |
| Claim Deadline | None exists for a confirmed Oasis settlement |
| Administrator | None appointed |
| Proof Needed | Not applicable |
Is Oasis Settlement Loans Legit or a Scam?
Oasis Financial is a legitimate company, not a scam. It operates as a pre-settlement funding provider, meaning it advances money to plaintiffs awaiting personal injury settlements. The company has been in business since 2003 and is one of the largest lawsuit funding companies in the United States.
That does not mean every customer has a good experience. Many consumers report high fees and repayment amounts that feel surprising when their case finally settles. But high cost is not the same as fraud. Oasis discloses terms in its contracts, though critics argue the disclosures are not always clear enough for people under financial stress.
If you received a text or email claiming you have an Oasis settlement payout waiting, be careful. Scammers sometimes use the names of legitimate funding companies to phish for banking details. Oasis does not send unsolicited texts asking for your account information. Always verify through the company’s official contact channels before responding.
Key Takeaway: Oasis Financial is a real funding company, but it is not paying out a class action settlement in 2026.
Is Oasis Pre Settlement Funding the Same as a Settlement?
Oasis pre settlement funding is not the same as receiving your lawsuit settlement. It is a cash advance against money you might receive later. You are borrowing your own potential settlement, minus fees and interest.
Think of it like getting a store refund early but paying a service fee for the advance. The actual settlement money still comes from the defendant or insurance company. Oasis gets repaid from that amount when your case resolves.
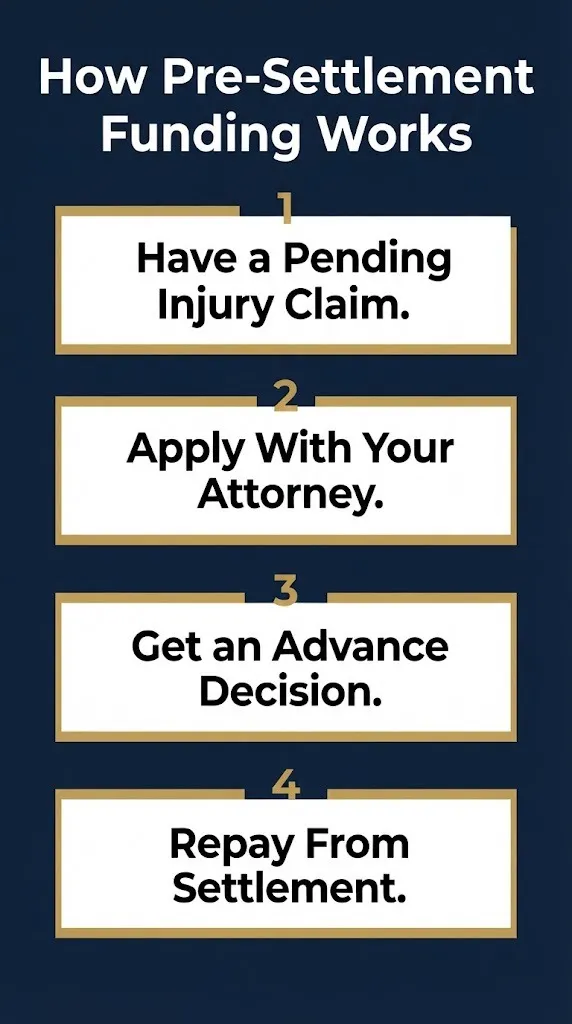
Here is the typical flow:
- You have a pending personal injury claim.
- You apply to Oasis for funding.
- Oasis reviews your case with your attorney.
- You receive a cash advance, often within 24 to 48 hours if approved.
- When your case settles, your attorney pays Oasis from the proceeds.
The key point: Oasis is a creditor in this arrangement, not a party to your lawsuit. If you lose your case, you typically owe nothing. That is the main difference between a lawsuit loan and a traditional loan.
How Much Does Oasis Settlement Funding Cost?
Oasis settlement funding costs vary widely. The company does not charge a flat interest rate like a bank loan. Instead, it uses a fee structure tied to how long your case takes to settle. Fees often compound over time.
For example, a $10,000 advance might cost $3,000 to $4,000 in fees if your case settles within 12 months. If it drags on for three years, the repayment could reach $20,000 or more. These are illustrative ranges based on industry patterns, not official Oasis rate sheets. Oasis does not publish a uniform fee schedule publicly.
Compare this to a credit card at 25 percent APR. That card would charge about $2,500 in interest on $10,000 over one year, roughly similar to the low end of the funding range. But pre-settlement funding can exceed credit card costs substantially on longer cases.
| Time to Settlement | $10,000 Advance | Estimated Repayment Range |
|---|---|---|
| 6 months | $10,000 | $12,000 to $14,000 |
| 12 months | $10,000 | $14,000 to $17,000 |
| 24 months | $10,000 | $18,000 to $24,000 |
| 36 months | $10,000 | $22,000 to $30,000 |
These ranges reflect industry patterns and consumer reports, not confirmed Oasis rate tables. Your contract terms control the actual amount.
What Is the Difference Between Oasis Lawsuit Loans and Regular Loans?
The difference is risk and repayment structure. A regular loan requires repayment regardless of what happens with your lawsuit. You pay it back from income or assets, win or lose. An Oasis lawsuit loan is non-recourse, meaning you only repay if you win or settle your case.
If you lose, Oasis gets nothing. That risk is why the company charges higher fees than a bank. It is underwriting your case, not your credit score. Oasis does not check your employment, credit history, or ability to repay in a traditional sense. The strength of your lawsuit is the collateral.
This structure also means Oasis cannot garnish your wages or seize your bank account if you lose. The worst-case scenario is that Oasis loses its investment. Your personal finances are shielded from collection in that situation.
Are There Any Oasis Financial Lawsuits in 2026?
There are no confirmed settled class actions against Oasis Financial as of February 26, 2026. The company has faced individual lawsuits and regulatory scrutiny over the years, but none have resulted in a consumer payout fund with a claims process open to the public.
Some cases have challenged the enforceability of funding agreements in specific states. For example, certain state courts have examined whether pre-settlement funding contracts are subject to usury laws. Results vary by jurisdiction. But a class action settlement with a claims administrator and payout schedule has not materialized.
If you see a website claiming you can join an Oasis class action settlement and receive money in 2026, treat it with skepticism. Verify the case number, court, and administrator independently. The absence of verified settlement details on court dockets and official settlement websites is a red flag.
Key Takeaway: No verified Oasis class action settlement exists in 2026, so any claim payout notice should be checked carefully.
What Is the Difference Between Oasis Pre Settlement Loan and Accident Settlement Loans?
Oasis pre settlement loan is a brand-specific term. Accident settlement loans is a broader category covering any funding tied to a personal injury claim. Oasis is one provider among many in the accident settlement loan space.
Other companies include Peachtree Financial Solutions, USClaims, Ally Lawsuit Loans, and High Rise Financial. Each has different fee structures and approval criteria. Some focus on specific case types, such as auto accidents or slip-and-fall claims.
When comparing providers, ask for the total repayment amount at 6, 12, and 24 months. A lower initial offer may carry steeper fees over time. Insist on seeing the full fee schedule in writing before signing anything.
How Do You Apply for Oasis Pre Settlement Funding?
Applying for Oasis pre settlement funding follows a structured process. Here are the steps:
- Contact Oasis by phone or through its official website.
- Provide basic case details and your attorney’s contact information.
- Oasis contacts your attorney for case documents.
- Underwriters review the liability and damages in your claim.
- You receive an approval decision, usually within one to two business days.
- If approved, you sign a funding agreement.
- Funds are disbursed by check, wire, or direct deposit.
- Your attorney manages repayment from your final settlement.
You cannot apply without an attorney. Oasis requires representation because your lawyer is the intermediary who confirms case facts and disburses settlement funds. If you do not have a lawyer, you will need to retain one before seeking funding.
What Are the Risks of Oasis Settlement Funding?
The main risk is cost. Fees compound and can eat a large portion of your settlement. You may walk away with significantly less money than you expected after repaying Oasis and paying your attorney.
Another risk is over-borrowing. Taking a larger advance than you need increases the fee burden. Some consumers borrow repeatedly against the same case, stacking fees and reducing their eventual net recovery.
There is also a transparency issue. The total repayment amount is not always obvious at signing. The contract may show a fee schedule rather than a single total cost figure. You may need to calculate the actual repayment at different settlement dates yourself or ask your attorney to do it.
Reality Check: No one texts you settlement money first. Legitimate settlement notices come by mail or through your attorney. Filing a claim is always free. Third-party “claim helpers” who charge fees are unnecessary. If someone asks for money to release your settlement, it is a scam.
What Is the Current Regulatory Status of Pre-Settlement Funding in 2026?
Pre-settlement funding regulation remains uneven across states. Some states treat it as a loan subject to usury caps. Others classify it as a purchase of an asset, exempting it from lending laws. That classification difference drives major variations in allowable fees.
In 2025, several state legislatures considered bills to cap fees or require standardized disclosures. The American Legal Finance Association, which represents companies like Oasis, has pushed for a uniform disclosure framework. Consumer advocates have argued for interest rate caps and mandatory plain-language repayment examples.
No federal regulation currently exists. The Consumer Financial Protection Bureau has not issued rules specific to pre-settlement funding as of February 2026. This leaves consumers relying on state laws that vary from broad to nonexistent.
How Do You Check Your Oasis Settlement Loan Status?
To check your Oasis settlement loan status, contact your attorney first. Your attorney tracks your underlying case and communicates with Oasis about repayment. Oasis does not have a public online portal for borrowers to check balances.
You can also call Oasis directly. The company assigns a case manager to each funded account. Have your account number or case reference ready. Ask for your current payoff amount and the fee accrued to date.
If your case has settled and your attorney has not yet disbursed funds, ask for the settlement statement. It should show the gross settlement, attorney fees, Oasis repayment, and your net amount. Compare the Oasis line item to the payoff amount on your funding statement. If they do not match, ask questions before signing the disbursement sheet.
Key Takeaway: Your attorney is the first point of contact for any Oasis account question. Always review the settlement statement before funds are distributed.
How Do You Get Out of an Oasis Settlement Loan?
Getting out of an Oasis settlement loan is difficult once you have accepted the funds. There is no standard cancellation period after disbursement. The contract binds you to repayment if your case settles.
Your options depend on timing. If you signed within the last few days, check whether your contract includes a rescission period. Some states require a cooling-off window for certain financial contracts. If not, you may still owe the full repayment if you keep the money.
If you change your mind before funds are disbursed, contact Oasis immediately. You may be able to withdraw your application and return any funds already sent. Do not spend the money and expect to cancel later. Once spent, the obligation stands.
What Alternatives Exist to Oasis Settlement Funding?
Alternatives to Oasis settlement funding exist and often cost less. Consider these options before signing a funding agreement:
- Negotiating a payment plan with medical providers to reduce immediate cash needs.
- Borrowing from a credit union or bank at a lower interest rate.
- Asking family for a short-term loan.
- Applying for a zero-interest credit card with an introductory period.
- Requesting a smaller advance from Oasis to reduce total fees.
- Seeking assistance from a legal aid or nonprofit that offers emergency grants.
Each option carries trade-offs. Family loans can strain relationships. Credit cards require creditworthiness. But the cost difference can be enormous. A 15 percent personal loan beats a funding agreement that charges 40 percent annualized in fees on most case timelines.
What Happens Next?
The pre-settlement funding industry will likely see continued state-level activity through 2026. Here is the expected timeline:
- Expected March 2026: Several state legislative sessions continue debating fee cap bills.
- Expected mid-2026: Consumer advocacy groups may release updated reports on funding industry practices.
- Expected late 2026: Any new state laws would take effect in 2027 at the earliest.
- Ongoing: Court cases challenging funding contract enforceability continue in individual jurisdictions.
- No confirmed date: Any class action settlement against Oasis would require court approval and a public notice process.
Watch for official announcements from state attorneys general and the Consumer Financial Protection Bureau. Any real settlement will appear on court dockets and through an appointed claims administrator. It will not arrive by unsolicited text.
Frequently Asked Questions
Is Oasis Financial a real company?
Yes. Oasis Financial is a real pre-settlement funding company operating since 2003. It is headquartered in Illinois and provides cash advances to plaintiffs awaiting lawsuit settlements.
Does Oasis Financial have a class action settlement in 2026?
No. There is no confirmed class action settlement against Oasis Financial with an open claims process as of February 2026.
How much does Oasis charge for pre-settlement funding?
Oasis does not publish a uniform fee schedule. Repayment amounts vary based on case length and advance size. Industry patterns suggest fees can range from 30 to 100 percent or more of the advance on longer cases.
Do you have to pay back Oasis if you lose your case?
No. Oasis funding is non-recourse. If you lose your case, you typically owe nothing. The company absorbs the loss.
Can you apply for Oasis funding without a lawyer?
No. Oasis requires an attorney on your case. Your lawyer provides case documentation and manages repayment from settlement proceeds.
How long does Oasis funding approval take?
Approval typically takes 24 to 48 hours after Oasis receives your case documents from your attorney. Disbursement follows quickly after you sign the agreement.
Is Oasis pre-settlement funding regulated?
Regulation varies by state. Some states treat it as a loan, while others classify it as an asset purchase. No federal rules specifically govern pre-settlement funding as of February 2026.
How do you check your Oasis payoff amount?
Contact your attorney or call Oasis directly. Ask for a current payoff statement. Review it against your settlement disbursement sheet before signing.