Settlement Funding Diamondback Funding 2026: Lawsuit Loans, Costs, and What You Must Know
Quick Answer
- Diamondback Funding offers non-recourse lawsuit loans, meaning repayment only happens if you win or settle.
- Approval is based on case strength, not credit score, but fees can significantly reduce your final settlement.
- There is no settlement deadline because this is a funding product, not a class action claims process.
Diamondback Funding is a pre-settlement funding company, not a defendant in a class action settlement. It provides cash advances to plaintiffs who are waiting for their lawsuits to resolve .
If you are searching for “settlement funding diamondback funding,” you likely want to know how these advances work, what they cost, and whether they are safe. You may have seen an ad, received a referral, or heard about lawsuit loans from someone in your network.
This article explains the verified facts about Diamondback Funding’s product, the real costs of pre-settlement advances, the risks that can eat into your settlement, and how to evaluate whether this type of funding makes sense for your situation. One detail most people miss: pre-settlement funding is not a loan in the traditional sense, and the repayment amount can grow substantially over time .
The Facts
| Company | Diamondback Funding |
|---|---|
| Product Type | Non-recourse pre-settlement funding (lawsuit loan) |
| Who Qualifies | Plaintiffs with active lawsuits and attorney representation |
| Funding Range | Not publicly disclosed. Varies by case value |
| Repayment | Only if case settles or wins |
| Cost Structure | Fees accrue over time, reducing final settlement |
| Claim Deadline | None. This is not a settlement claims process |
Is Diamondback Funding Legit or a Scam?
Diamondback Funding is a legitimate pre-settlement funding company, but lawsuit loans carry real financial risks that you need to understand before signing anything. It is not a scam, but it is also not free money.
The company has been in operation since at least 2026, with coverage appearing in financial and legal publications . It operates in the legal funding industry, which is regulated differently from state to state.
Pre-settlement funding is legal in most states. However, some states have caps on interest rates or specific disclosure requirements. The industry has faced criticism for high fees and aggressive marketing, but that does not make every company a scam.
The real risk is financial, not fraudulent. If your case takes years to resolve, the repayment amount can grow significantly, potentially leaving you with little or nothing after your attorney and the funding company are paid .
How Much Does Diamondback Funding Cost?
Diamondback Funding does not publish its fee structure, and no verified rate is available publicly. Pre-settlement funding fees industry-wide typically range from 2% to 5% per month, compounded over the life of the advance.
Not yet determined for Diamondback Funding specifically. The company uses case-by-case underwriting, and the cost depends on your case type, expected timeline, and funding amount .
Here is what the industry structure looks like:
| Fee Component | Typical Range | How It Works |
|---|---|---|
| Monthly fee | 2% to 5% | Accrues on the funded amount |
| Compounding | Often yes | Fees can accrue on prior fees |
| Origination | Varies | Some companies charge upfront |
| Maximum cap | State-dependent | Some states cap total repayment |
The longer your case takes, the more you owe. A $10,000 advance at 4% monthly compounded for 24 months could result in a repayment obligation of over $25,000 .
This is not a traditional loan with fixed payments. It is an advance against your settlement, and the repayment comes off the top when your case resolves.
Reality Check: No legitimate funding company will promise you “free money” or guarantee approval without reviewing your case. If someone contacts you offering immediate cash with no attorney involvement and no case review, that is a red flag. Pre-settlement funding always requires your attorney’s cooperation.
Who May Qualify for Diamondback Funding?
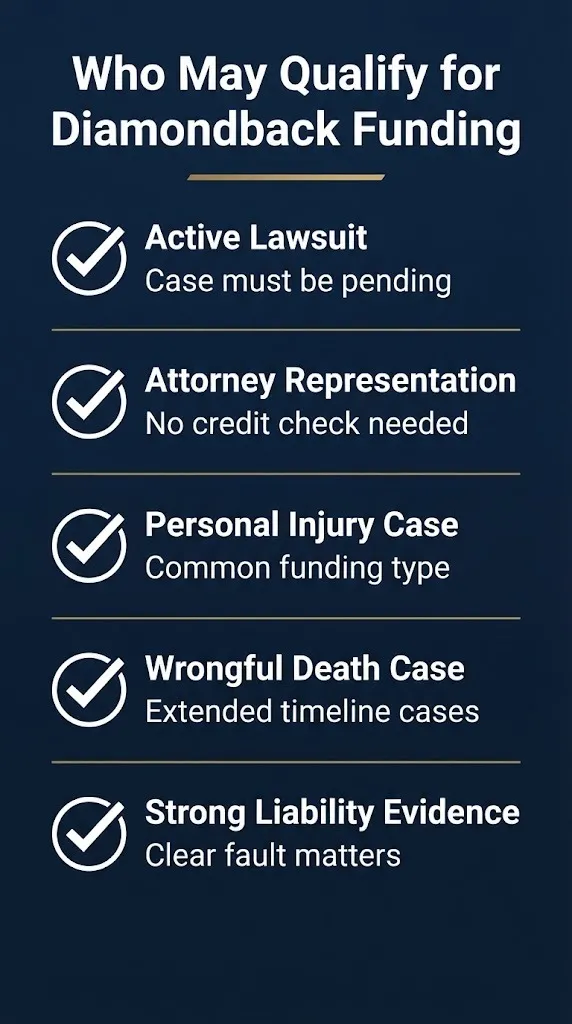
You may qualify for Diamondback Funding if you have an active personal injury or other eligible lawsuit and are represented by an attorney. The company does not fund cases without legal representation.
Common case types that may qualify include:
- Personal injury cases: Car accidents, slip and falls, workplace injuries, and other negligence claims .
- Wrongful death cases: These often involve extended timelines and significant financial strain on families .
- Certain class actions: Depending on structure and potential value .
- Other contingency cases: Where the plaintiff expects a settlement or judgment.
The approval decision is based on the strength of your case, the clarity of liability, and the projected settlement value. Your credit score and employment history do not matter .
Your attorney must cooperate with the process. The funding company communicates directly with your lawyer to verify the case details and arrange repayment from settlement proceeds .
Key Takeaway: Diamondback Funding advances are only available to plaintiffs with active lawsuits and attorney representation, and approval hinges entirely on case strength, not personal credit.
How Does the Diamondback Funding Process Work?
The Diamondback Funding process involves an application, attorney verification, case underwriting, and disbursement if approved. It is designed to be faster than traditional lending, but it still requires your attorney’s involvement.
Here is the step-by-step process:
- Apply for funding. You provide basic information about your case and your attorney .
- Diamondback contacts your attorney. They verify representation and gather case details .
- Underwriting review. Diamondback evaluates liability, damages, and likelihood of success .
- Approval decision. If approved, you receive a funding offer.
- Sign the agreement. You agree to repay from settlement proceeds if your case succeeds.
- Funds disbursed. Money is sent to you, often within a short timeframe .
- Repayment at resolution. When your case settles or you win, the advance plus fees are repaid from the proceeds.
You do not make monthly payments. The entire repayment comes from your settlement or judgment .
What Are the Risks of Pre-Settlement Funding?
The main risk of pre-settlement funding is that the repayment amount can consume a large portion of your settlement, leaving you with less than you expected. There is no repayment if you lose, but the cost of winning can be high.
The longer your case takes, the more the fees accrue. A case that settles in six months may cost you far less than a case that takes three years .
Financial pressure is another risk. Having cash available can reduce the incentive to settle quickly, but it can also create a false sense of security. If you spend the advance and your case settles for less than expected, you may end up with nothing after repayment .
Some states have specific regulations on legal funding. Not all companies operate in all states, and some states cap fees or require disclosures. Check your state’s rules before signing .
Finally, not every case qualifies. Claims with unclear liability or low settlement potential may be rejected .
What Happens Next if You Apply for Diamondback Funding?
If you apply for Diamondback Funding, the next stages involve attorney verification, underwriting, and either approval or denial. The timeline is typically shorter than a lawsuit itself.
Within 24 to 48 hours: Initial application review and attorney contact .
Within a few days: Underwriting decision based on case strength.
If approved: Funding agreement sent for signature and funds disbursed.
If denied: You may explore other funding companies or wait for your case to resolve.
At case resolution: Repayment is deducted from your settlement or judgment.
The entire process is designed to be faster than traditional lending, but it still depends on your attorney’s responsiveness and the clarity of your case details.
Frequently Asked Questions
Is Diamondback Funding a scam?
No. It is a legitimate pre-settlement funding company, but lawsuit loans carry real financial risks and high fees.
How much can I get from Diamondback Funding?
The funding amount is not publicly disclosed and depends on your case value. There is no standard amount.
Do I have to pay back Diamondback Funding if I lose my case?
No. The funding is non-recourse, meaning repayment only happens if your case settles or wins .
Does Diamondback Funding require a credit check?
No. Approval is based on case strength, not credit score or employment history .
What types of cases does Diamondback Funding accept?
Personal injury, wrongful death, and certain class action cases are commonly funded .
How long does Diamondback Funding take to approve?
Approval can happen quickly, often within a short time frame, once your attorney provides case details .
Can I get Diamondback Funding without an attorney?
No. Attorney representation is required for pre-settlement funding .
What happens if my case takes years to settle?
The longer your case takes, the more fees accrue, which reduces your final settlement amount .