Workers Compensation Insurance in NY 2026: Coverage Rules, Rates, and Benefits
Quick Answer
- New York requires workers’ compensation insurance for every employer, including those with part-time workers and family members .
- The 2026 maximum weekly benefit is $1,281.50, with a minimum of $384.45 .
- Governor Hochul approved an average 22% premium reduction for employers, effective October 1, 2026 .
The Facts
| Coverage Rule | Mandatory for all employers in New York State |
|---|---|
| 2026 Maximum Weekly Benefit | $1,281.50 (July 1, 2026 to June 30, 2027) |
| 2026 Minimum Weekly Benefit | $384.45 |
| Benefit Rate | Two-thirds of the New York State Average Weekly Wage (NYSAWW) |
| 2026 NYSAWW | $1,922.25 (calendar year 2025) |
| Premium Reduction | 22% average decrease effective October 1, 2026 |
| State Insurance Fund | NYSIF, the largest workers’ comp carrier in New York |
| Regulatory Body | New York State Workers’ Compensation Board |
Is Workers Compensation Insurance Required in New York?
Yes, workers’ compensation insurance is required in New York for all employers. The rule is one of the strictest in the country: if you have even one employee, you need coverage .
That includes part-time workers, seasonal staff, and family members who work for the business . There are very few exemptions, and the state enforces the mandate through business permits and proof-of-coverage requirements .
Employers have three options for obtaining coverage:
- Private insurance company. Shop the competitive market.
- New York State Insurance Fund (NYSIF). The state-run carrier and the largest workers’ comp writer in New York .
- Self-insurance. Rare and requires Board approval plus a substantial security deposit .
Self-insurance is a privilege, not a right. As of July 1, 2025, the minimum security deposit for workers’ compensation self-insurers is $1,907,000 . That number alone tells you why most employers buy a policy instead.
How Much Does Workers Compensation Insurance Cost in New York?
The average workers’ compensation rate in New York is approximately $2.50 per $100 of payroll for direct market coverage, though rates vary widely by industry classification and claims history .
Your premium is calculated with a formula: (annual payroll divided by 100) multiplied by your class code base rate, then adjusted by your experience modification rate (EMR) . The EMR is the biggest lever you control. A clean claims history compounds into lower premiums year over year.
The big news for 2026: Governor Kathy Hochul announced an average 22% reduction in workers’ compensation premium rates, effective October 1, 2026 . That represents an estimated savings of more than $1 billion for New York businesses, or an average of $1,779 per insured .
NYSIF has also returned more than $700 million to its policyholders in the last year through dividends and discount programs . The state’s workers’ comp rates have decreased steadily since 2020, with approved rate reductions averaging 10.3% annually over six years .
For small employers, PEO arrangements can provide access to pooled rates that are often significantly lower than direct market rates, with one analysis citing a discount factor of 0.46 applied to direct market rates .
Key Takeaway
Key Takeaway: New York requires workers’ comp coverage from the first employee, and the 22% premium reduction effective October 1, 2026, makes this the cheapest time in years for employers to shop for coverage.
How Much Is Workers Compensation in New York in 2026?
The maximum weekly workers’ compensation benefit in New York for injuries occurring between July 1, 2026, and June 30, 2027, is $1,281.50 . The minimum weekly benefit is $384.45 .
New York pays two-thirds of your average weekly wage, subject to those caps . The maximum and minimum are adjusted annually on July 1 based on the New York State Average Weekly Wage, which the Department of Labor reported as $1,922.25 for calendar year 2025 .
How does the math work for you? If you earned $900 per week before your injury, two-thirds is $600. That is below the cap, so your weekly benefit is $600. If you earned $3,000 per week, two-thirds would be $2,000, but the cap limits you to $1,281.50.
| Date of Accident | Weekly Maximum | Weekly Minimum |
|---|---|---|
| July 1, 2026 to June 30, 2027 | $1,281.50 | $384.45 |
| July 1, 2025 to June 30, 2026 | $1,222.42 | $325.00 |
Your benefit rate is locked to your date of injury. It does not increase if new maximum or minimum rates take effect later .
Who May Qualify for New York Workers Compensation Benefits?
You may qualify for New York workers’ compensation benefits if you suffered a work-related injury or illness. The system is no-fault, meaning you do not have to prove your employer did anything wrong .
New York provides several types of benefits:
- Medical treatment. All necessary care for your work injury, paid by the workers’ comp insurer .
- Lost wage benefits. Weekly checks if your injury prevents you from working for more than seven days .
- Permanent disability benefits. Compensation for lasting impairment.
- Death benefits. For surviving dependents.
- Travel reimbursement. Mileage and transportation costs for treatment visits .
A key protection: you should not pay out of pocket for workers’ compensation treatment, medication, or prescribed equipment . The insurer pays those bills unless your claim is denied.
Reality Check: No one calls you out of the blue and offers workers’ comp settlement money without paperwork. If someone promises a fast settlement for an upfront fee, it is a scam. Filing a claim with the Workers’ Compensation Board is free, and legitimate settlements go through the Board’s approval process.
What Is the Difference Between NYSIF and Private Workers Comp Carriers?
NYSIF is the New York State Insurance Fund, a state-run workers’ compensation carrier. It is the largest writer of workers’ comp in New York and operates as a competitive alternative to private insurers .
NYSIF functions like a private carrier but with a public mission. It was created in 1914 to provide coverage for employers who could not find it in the private market . Today it competes directly with private carriers and offers several advantages:
- Dividends. NYSIF has returned more than $2.8 billion to policyholders under Governor Hochul’s leadership .
- Safety programs. Free consultations for large policyholders required to comply with Industrial Code Rule 59 .
- Fast processing. NYSIF reports a 97% timely initial payment rate, surpassing industry benchmarks .
Private carriers like Travelers, AmTrust Financial, and others also write coverage in New York . The right choice depends on your industry, claims history, and whether you qualify for group safety programs through NYSIF.
For high-risk industries, NYSIF is often the most competitive option. For businesses with strong safety records, private carriers may offer better pricing.
How to File a Workers Compensation Claim in New York
Filing a New York workers’ comp claim starts with reporting your injury to your employer, then filing the Employee Claim form with the Board. Here are the steps :
- Seek medical care immediately. Tell your provider the injury is work-related.
- Report your injury to your employer in writing within 30 days.
- Get treatment from a Board-authorized provider. Emergency care is covered from any provider .
- File Form C-3 with the Workers’ Compensation Board. Do this as soon as possible .
- Meet the two-year deadline. A claim must be filed within two years of your injury or illness .
- Attend all medical appointments. Missed appointments can be used to dispute your claim.
- Keep records of everything. Pay stubs, medical bills, work restrictions, and correspondence.
- Request a hearing if your claim is disputed. You have the right to an attorney, and the Board determines the fee, which is deducted from your award, not paid upfront .
Key Takeaway
Key Takeaway: New York workers’ comp claims must be filed within two years of injury, and the filing itself is free; attorney fees are set by the Board and paid from your award, not out of pocket.
What Does Workers Compensation Insurance Cover in NY?
New York workers’ compensation insurance covers medical treatment, lost wages, and rehabilitation for work-related injuries and illnesses. Here is the full scope:
- Medical care. Doctor visits, hospital stays, surgery, prescriptions, and medical equipment .
- Lost wage benefits. Weekly payments if your injury prevents you from working for more than seven days .
- Permanent disability. Compensation for lasting impairments that affect your earning capacity.
- Vocational rehabilitation. Job retraining if you cannot return to your previous work.
- Death benefits. For dependents if a work injury is fatal.
- Travel expenses. Reimbursement for mileage and transportation to treatment visits .
The workers’ compensation system is no-fault. That means you get benefits regardless of who caused the injury. In exchange, you generally cannot sue your employer for the injury .
There is one important exception: if a third party (someone other than your employer) caused the injury, you may have a separate personal injury claim. A defective machine, a negligent driver, or an unsafe property owner could all be third parties.
How to Choose a Workers Compensation Insurance Carrier in NY
Choosing the right carrier means balancing price, service, and safety resources. Here is what to compare:
- Premium quotes. Get quotes from at least three carriers, including NYSIF and private insurers.
- Dividend history. NYSIF has paid significant dividends; ask private carriers about their record.
- Safety programs. Free consultations and training can reduce injuries and lower premiums over time.
- Claims service. Ask about timely payment rates and claims handling.
- Industry expertise. A carrier that knows your trade will classify you accurately and price you fairly.
The 22% rate reduction effective October 1, 2026, means this is an especially good time to shop . Your current carrier may not have passed the full savings through automatically.
Think of it like renewing your car insurance. The rate environment changed, and loyalty does not always pay. A fresh quote costs nothing.
What Happens Next in New York Workers Compensation in 2026?
Here is the expected timeline for rate changes and regulatory developments:
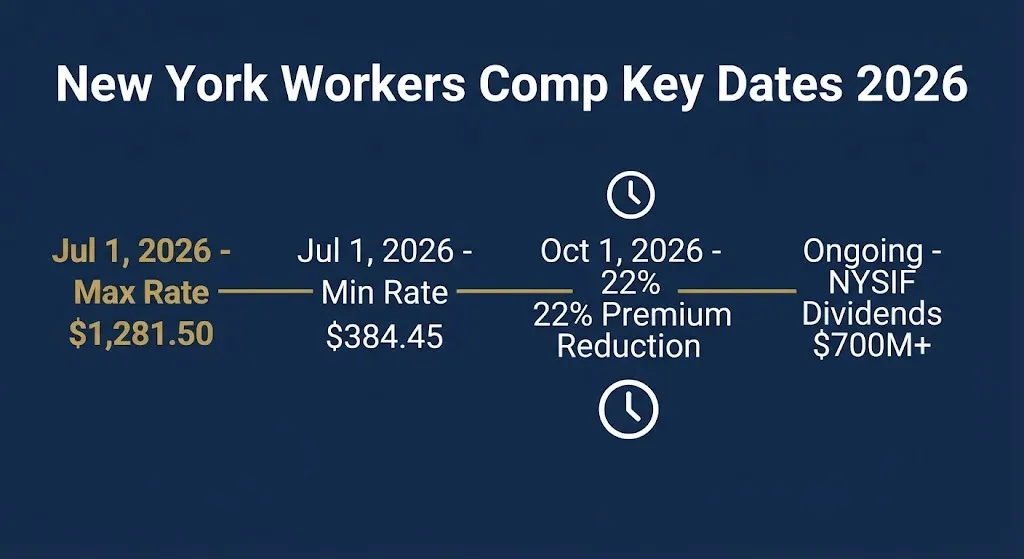
July 1, 2026: The maximum weekly benefit increased to $1,281.50 and the minimum to $384.45 for new injuries .
October 1, 2026: The 22% average premium reduction took effect for employers .
Ongoing 2026: NYSIF continues returning dividends and discounts to policyholders, with more than $700 million distributed in the last year .
TBD: Any further legislative changes to the Workers’ Compensation Law. No major changes beyond the annual rate adjustments have been enacted.
Frequently Asked Questions
Do I need workers comp insurance in New York if I have one employee?
Yes. New York requires workers’ compensation coverage for every employer, including those with one employee, part-time workers, and family members .
What is the maximum workers comp rate in New York for 2026?
The maximum weekly compensation rate for injuries on or after July 1, 2026, is $1,281.50 .
How much does workers comp insurance cost in New York?
The average rate is approximately $2.50 per $100 of payroll, but rates vary by industry class code and claims history. The 22% reduction effective October 1, 2026, lowers costs for most employers .
What is NYSIF?
NYSIF is the New York State Insurance Fund, a state-run workers’ compensation carrier and the largest writer in New York. It competes with private carriers and returns dividends to policyholders .
How long do I have to file a workers comp claim in New York?
You must report your injury to your employer within 30 days and file Form C-3 with the Board within two years of the injury or illness .
Can I see any doctor for workers comp in New York?
For non-emergency care, you must use a provider authorized by the Workers’ Compensation Board. In an emergency, you can go anywhere and the insurer will reimburse the care .
Can I be fired for filing a workers comp claim in New York?
No. Retaliation against an employee for filing a workers’ compensation claim is illegal. If your employer retaliates, you may have additional legal claims .
What happens if my workers comp claim is denied in New York?
You can request a hearing before a Workers’ Compensation Law Judge. You have the right to an attorney, and the Board determines the fee, which is deducted from your award .
Your Next Step
If you were injured on the job in New York, report it to your employer in writing today. Keep a copy of that notice. Then file Form C-3 with the Workers’ Compensation Board online as soon as possible.
The 2026 maximum weekly rate of $1,281.50 applies to injuries on or after July 1, 2026. Your benefit is locked to your injury date, so the sooner you file, the sooner your claim moves forward. And if you are an employer, October 1, 2026, is the date the 22% rate reduction took effect. Shop your coverage now.