JG Wentworth Debt Settlement 2026: Fees, Program Costs, Complaints, and What You Actually Get
Quick Answer
- Is it legit? Yes. JG Wentworth is a real company founded in 1991 with an A+ BBB rating. Debt settlement is a legal but risky financial product .
- How much does it cost? 18% to 25% of your total enrolled debt, plus a $9.95 setup fee and $9.95 monthly maintenance fee .
- The catch: You must stop paying your creditors, your credit score will drop, and you could be sued while funds accumulate in escrow .
If you are drowning in credit card debt and searching for JG Wentworth debt settlement, you have probably heard the jingle: “I have a structured settlement and I need cash now.” But JG Wentworth is not just buying structured settlements anymore. The company now runs a debt relief program that promises to settle your credit cards for less than you owe.
Here is the number that matters most: JG Wentworth charges 18% to 25% of your enrolled debt as its fee, calculated on the original balance, not on what you save . On $25,000 of debt, that fee alone can be $6,250 before you pay a single creditor.
This article breaks down what the program actually costs, how the fee math works against you, what real customers complain about, and the states where JG Wentworth debt settlement is not even available. One surprising verified detail: JG Wentworth reports a 46% average savings before fees, but after fees that number drops to 21% .
The Facts
| Case Type | Debt settlement program operated by JGW Debt Settlement, LLC (JG Wentworth) |
|---|---|
| Company Status | Active, founded 1991, headquartered in Chesterbrook, Pennsylvania |
| Minimum Debt Required | $10,000 in qualifying unsecured debt |
| Settlement Fee | 18% to 25% of total enrolled debt |
| Additional Fees | $9.95 one-time setup, $9.95 monthly maintenance |
| Average After-Fee Savings | 21% of enrolled debt (reported by company) |
| Average Program Length | 32 months |
| Not Available In | West Virginia (other states may use partner law firms) |
| BBB Rating | A+ accredited since 1994 |
| Proof Needed | None to enroll, but you must stop paying creditors |
Is JG Wentworth debt settlement legit or a scam?
JG Wentworth debt settlement is legitimate in the sense that the company is real, licensed where required, and operates a debt relief program that has helped hundreds of thousands of clients since 1991.
The company holds an A+ rating from the Better Business Bureau and an accreditation from the Association for Consumer Debt Relief . It was named one of USA TODAY’s Most Trusted Brands 2026 based on a survey of more than 23,000 consumers .
But “legitimate company” does not mean “good deal for you.” Debt settlement as a product carries serious risks regardless of who runs it. You stop paying your creditors. Your credit score drops. Your accounts go delinquent. Creditors can sue you while you wait for settlements.
JG Wentworth’s own disclosure acknowledges this. The company says clients “typically resolve enrolled debts within 24 to 48 months” and save an average of 44% before fees . That 44% figure is real, but it is not your savings. Your savings is what is left after JG Wentworth takes its cut.
Key Takeaway: JG Wentworth is a real company, not a scam. But debt settlement is a high-risk product, and the math works better for JG Wentworth than it does for you.
How much does JG Wentworth debt settlement cost in 2026?
JG Wentworth charges a settlement fee of 18% to 25% of your total enrolled debt, plus a $9.95 setup fee and $9.95 monthly maintenance fee. The fee is based on what you owe, not what you save.
This is the single most misunderstood part of the program. You do not pay 25% of the savings. You pay 25% of the debt you enrolled.
Here is the math on a $25,000 enrollment:
| Cost Component | Amount |
|---|---|
| Enrolled debt | $25,000 |
| Example settlement amount | $14,000 |
| JG Wentworth fee (25% of enrolled) | $6,250 |
| Setup and monthly fees | ~$350 over 32 months |
| Total out of pocket | $20,600 |
| Your actual savings | $4,400 (17.6%) |
JG Wentworth reports that customers save an average of 46% before fees and 21% after fees . That 21% figure aligns with the math above. On $25,000, a 21% net savings is $5,250.
The fee percentage varies by state and individual situation. JG Wentworth’s website says fees are “a percentage of each debt that you enroll and settle” and that percentage “varies from client to client” . Bankrate reports the range as 18% to 25% . NerdWallet confirms the same range and notes the fee cannot be collected until a debt is successfully settled .
Key Takeaway: The fee is 18% to 25% of what you owe, not what you save. On a $25,000 debt, expect to pay at least $4,500 in fees even if everything goes perfectly.
What is the JG Wentworth fee on a $20,000 debt?
On a $20,000 debt, the JG Wentworth settlement fee ranges from $3,600 to $5,000 depending on your state and situation. You also pay a $9.95 setup fee and $9.95 per month for the escrow account.
Finder.com ran this exact calculation and concluded that on $20,000 of Visa debt, you would pay between $3,600 and $5,000 in JG Wentworth fees . That is on top of whatever you pay the creditor to settle.
The monthly maintenance fee adds up too. At $9.95 per month for an average 32-month program, that is roughly $318 in account fees alone . JG Wentworth also offers an optional legal insurance add-on for $17.99 per month if you want representation in case a creditor sues .
Adding it all up on a $20,000 enrollment with a 25% fee:
- JG Wentworth fee: $5,000
- Setup fee: $9.95
- Monthly maintenance (32 months): $318
- Total fees: $5,327.95
If the debt settles for $11,200 (a 44% reduction), you pay $11,200 to the creditor plus $5,328 in fees, for a total of $16,528. Your actual savings on the original $20,000 is $3,472, or about 17%.
Key Takeaway: On a $20,000 debt, you could pay more than $5,300 in fees to JG Wentworth alone, regardless of how much the creditor agrees to accept.
JG Wentworth debt settlement reviews: what do real customers say?
JG Wentworth debt settlement reviews are mixed. The company has a 4.8-star Trustpilot rating, but BBB complaints and ConsumerAffairs reviews describe difficulty leaving the program, slow settlement progress, and poor customer service near the end.
JG Wentworth’s own marketing highlights a 4.8-star average across more than 27,500 verified reviews . That is a strong number. The Better Business Bureau shows an A+ rating .
But the complaints tell a different story. A BBB complaint from July 2026 describes a customer trying to leave the program and remove accounts that belonged to a co-applicant. The customer wrote: “I reached out to have them remove the accounts they had listed for me and they said that it was pending and to wait longer” . The back-and-forth took weeks to resolve.
A ConsumerAffairs reviewer from 2024 described waiting “2 1/2 months” for funds after selling an annuity, with repeated document errors that required resigning . Another reviewer said customer service was “almost non-existent” during the last six months of the program, and it took three months to correct a bank account change .
The pattern in negative reviews is not fraud. It is friction. Programs that take 32 months to complete create plenty of opportunities for miscommunication, account errors, and frustration.
Key Takeaway: Most customers finish the program without major problems, but complaints cluster around exits, account changes, and the final months of service.
Reality Check
No debt settlement company can guarantee a specific savings amount before they negotiate. JG Wentworth’s “44% average savings” is before fees, and your results depend on your creditors, your state, and how quickly you accumulate funds. If you cannot afford the monthly deposit, do not enroll.
What states is JG Wentworth debt settlement not available in?
JG Wentworth’s debt relief program is not available directly in West Virginia. In some other states, the company connects consumers with independent law firms that provide debt resolution services. State fee caps vary widely.
NerdWallet reports that JG Wentworth debt settlement is “not available in: West Virginia” . Other sources indicate that JG Wentworth operates directly in approximately 30 states and uses partner law firms in other jurisdictions .
State regulation of debt settlement is a patchwork. Some states cap fees at very low levels. For example:
- Georgia: 7.5% fee cap
- Florida: 7.5% fee cap plus $50 enrollment fee cap
- Delaware: 18% settlement fee cap
- Illinois: 5% of savings fee cap
- Maine: 15% settlement fee cap
This data comes from a New York City Bar Association white paper on debt settlement regulation . JG Wentworth’s 18% to 25% fee range would violate the caps in several of those states if applied directly to consumers there. That is why the company uses partner law firms in restricted jurisdictions. Attorneys are often exempt from state debt settlement fee caps.
Before enrolling, verify what fee is legal in your state. JG Wentworth will do this for you, but you should understand the rules yourself.
Key Takeaway: If you live in Georgia, Florida, Illinois, Maine, or another state with strict fee caps, your JG Wentworth fee may be lower than advertised or the program may route you to a partner law firm.
How does the JG Wentworth debt settlement program actually work?
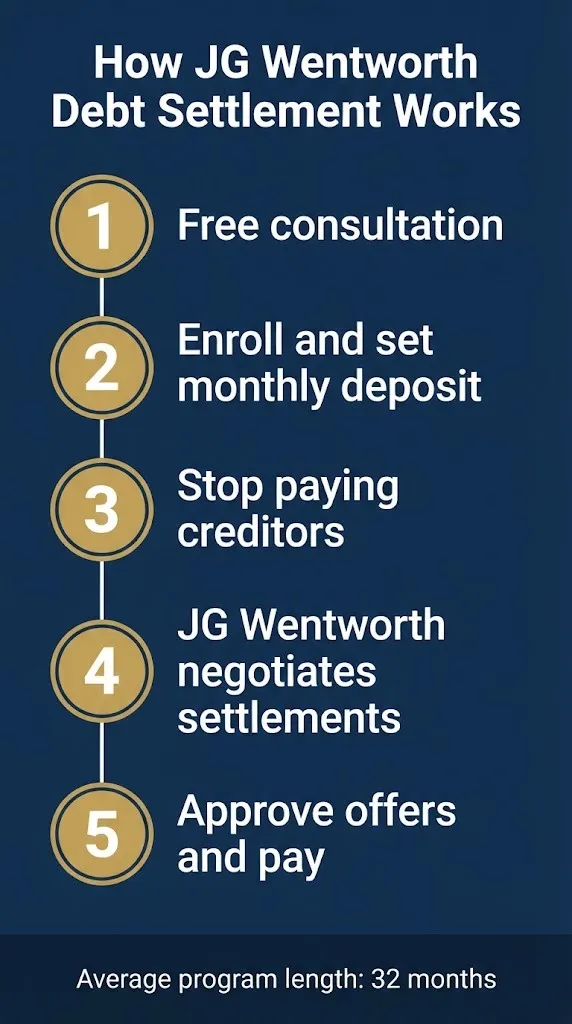
The JG Wentworth debt settlement process requires you to stop paying your creditors, deposit money into a dedicated FDIC-insured account each month, and let JG Wentworth negotiate settlements as funds accumulate.
Here is the step-by-step process:
- Free consultation: You call or apply online. JG Wentworth reviews your debts, income, and expenses.
- Enrollment: You agree to a monthly program payment and open a dedicated FDIC-insured account.
- Stop paying creditors: You stop making payments to enrolled debts. This is intentional and necessary for settlement.
- Accumulate funds: You make monthly deposits. JG Wentworth typically waits until enough money builds up to make a credible settlement offer.
- Negotiation: JG Wentworth contacts creditors and negotiates. You approve or reject each settlement offer before any money moves.
- Settlement payment: When you approve an offer, funds from your account pay the creditor. JG Wentworth takes its fee.
- Repeat: The process continues for each enrolled debt until all are settled or the program ends.
JG Wentworth settles an average of six debts per client, and different creditors settle at different times depending on their response . The entire process takes 32 months on average, and JG Wentworth says clients typically resolve debts within 24 to 48 months .
One important detail: you must stop paying your creditors. If you keep paying them, there is no incentive for them to settle for less. This is standard in debt settlement, but it is also the step that damages your credit the most.
Key Takeaway: The program only works if you stop paying your creditors. That is the core mechanic, and it is why debt settlement hurts your credit score.
Is JG Wentworth debt settlement better than National Debt Relief or Freedom Debt Relief?
JG Wentworth has a higher minimum debt requirement ($10,000) and higher bottom-end fees (18%) than National Debt Relief and Freedom Debt Relief, which both accept $7,500 minimums and charge as low as 15%.
Here is how the three compare:
| Company | Minimum Debt | Fee Range | Reported After-Fee Savings | BBB Rating |
|---|---|---|---|---|
| JG Wentworth | $10,000 | 18% to 25% | 21% | A+ |
| National Debt Relief | $7,500 | 15% to 25% | ~20% | A+ |
| Freedom Debt Relief | $7,500 | 15% to 25% | Varies | A+ |
National Debt Relief accepts consumers with $7,500 in unsecured debt, 25% lower than JG Wentworth’s minimum. Its fees can drop to 15%, lower than JG Wentworth’s 18% floor. After all fees, National Debt Relief reports average savings of approximately 20%, comparable to JG Wentworth’s 21% .
Freedom Debt Relief also has a $7,500 minimum and a 15% to 25% fee range. It offers a program cost guarantee: if your total settlement cost including fees exceeds your original enrolled debt, the company refunds the fee difference .
JG Wentworth’s advantages are brand recognition, a long operating history, and a broad service network. Its disadvantages are the higher minimum and higher floor on fees.
Key Takeaway: If you have less than $10,000 in debt, JG Wentworth will not enroll you. National Debt Relief and Freedom Debt Relief will, and they may charge less.
JG Wentworth debt settlement complaints: what are the most common issues?
The most common JG Wentworth debt settlement complaints involve difficulty exiting the program, slow progress on settlements, account errors during the final months, and customer service breakdowns.
BBB complaint data from 2026 shows a pattern of customers struggling to remove accounts or co-applicants from the program . One complainant wrote: “They ignored this and failed to do anything” after requesting account removal.
ConsumerAffairs reviews highlight similar themes. A 2024 reviewer said customer service was “good up until the last 6 months of the program” before becoming “almost non-existent” . Another described taking three months to correct a bank account change.
JG Wentworth’s response to BBB complaints is typically professional and offers to resolve the issue directly. The company removed a co-applicant and processed creditor removals after a complaint was escalated .
The complaints are not about fraud or theft. They are about the operational friction of a 32-month program with multiple accounts and changing life circumstances. That friction is real, and you should expect it if you enroll.
Key Takeaway: Most complaints are about exits and account changes, not missing money. If your life circumstances change during the program, expect delays.
What happens next: JG Wentworth debt settlement in 2026 and 2027
Expected late 2026: JG Wentworth continues operating under its current fee structure and state-by-state availability. No regulatory changes specific to the company are pending.
Expected early 2027: The company’s USA TODAY Most Trusted Brands recognition from March 2026 remains in effect through the next survey cycle.
Ongoing: JG Wentworth faces a TCPA class action filed in the Western District of North Carolina alleging unwanted telemarketing calls to a number on the Do Not Call Registry . The case is pending.
Ongoing: State-level debt settlement regulation continues to evolve, with fee caps in states like Georgia and Florida limiting what companies can charge directly.
Frequently Asked Questions
Is JG Wentworth debt settlement a scam?
No. JG Wentworth is a legitimate company founded in 1991 with an A+ BBB rating. Debt settlement is a legal but high-risk product.
How much does JG Wentworth charge for debt settlement?
JG Wentworth charges 18% to 25% of your total enrolled debt, plus a $9.95 setup fee and $9.95 monthly maintenance fee.
Does JG Wentworth debt settlement hurt your credit?
Yes. The program requires you to stop paying your creditors, which causes delinquencies and lowers your credit score.
How long does JG Wentworth debt settlement take?
The average program length is 32 months. JG Wentworth says clients typically resolve debts within 24 to 48 months.
Can I cancel JG Wentworth debt settlement?
Yes, you can cancel, but BBB complaints show that exiting the program can involve delays and account errors.
Is JG Wentworth debt settlement available in my state?
JG Wentworth operates directly in about 30 states and uses partner law firms elsewhere. It is not available in West Virginia.
What is the minimum debt for JG Wentworth debt settlement?
You need at least $10,000 in qualifying unsecured debt to enroll.
Does JG Wentworth debt settlement really save money?
JG Wentworth reports 44% average savings before fees and 21% after fees. Your results depend on your creditors and state.
What You Should Do Next
Before you call JG Wentworth, pull your credit reports and list every debt with its balance and interest rate. Calculate what 25% of your total enrolled debt would be. That is the worst-case fee you might pay.
Then compare that number to what you would save by negotiating directly with your creditors or using a nonprofit credit counselor. Debt settlement is not the only option, and for some people it is the wrong one.
The most important number to remember: 18% to 25% of your enrolled debt. That is what JG Wentworth charges, regardless of how much you save.