Deferred Compensation Calculator 2026: What It Can Project, What It Cannot, and the 409A Trap Most Calculators Ignore
Quick Answer
- A deferred compensation calculator estimates future account growth, not guaranteed payouts. Results depend entirely on the assumptions you enter.
- Nonqualified deferred compensation has no IRS contribution cap in 2026. Qualified 457(b) plans cap at $24,500, plus catch-up contributions for eligible ages.
- A 409A violation triggers immediate taxation of all deferred amounts, a 20% additional tax, and interest charges, none of which a basic calculator will warn you about.
A deferred compensation calculator projects what your deferred salary could grow to by retirement, using your contribution rate, employer match, and an assumed return. That is the honest answer. The tool does arithmetic on your inputs. It does not verify whether your plan complies with tax law, whether your employer will stay solvent, or whether your payout timing will trigger a penalty.
This matters most for two groups: public employees in 457(b) plans and executives in nonqualified deferred compensation arrangements. Both use calculators, but the rules governing each are completely different. The 457(b) side has published IRS limits for 2026. The nonqualified side has no statutory cap and a much sharper downside.
Here is what this article covers: the 2026 contribution limits, how calculator projections actually work, the 409A penalty structure most tools ignore, and the questions you should ask before trusting any projected balance. One detail worth knowing upfront: the lack of a 10% early withdrawal penalty in 457(b) plans is real, but it does not mean the money is tax-free.
The Facts
| Item | Verified Detail |
|---|---|
| 2026 457(b) Base Limit | $24,500 for most participants |
| 457(b) Age 50+ Catch-Up | $8,000, bringing the total to $32,500 |
| 457(b) Special Catch-Up | Up to double the limit in the three years before normal retirement age |
| Nonqualified Deferred Comp Limit | No statutory dollar limit. Plan document controls |
| 409A Failure Penalty | Immediate income inclusion, 20% additional tax, plus interest |
| 457(b) Early Withdrawal Penalty | None on separation from service, regardless of age |
Is a deferred compensation calculator legit or just a guess?
A deferred compensation calculator is a legitimate planning tool, not a prediction. It performs compound interest math on the numbers you feed it. The output is only as reliable as your assumptions about contributions, returns, and time horizon.
The calculator itself is not regulated. No federal agency approves these tools. A calculator on a bank website and a calculator on a random blog use the same basic formula: future value equals present value times the sum of periodic contributions compounded at a assumed rate.
What makes a calculator useful is transparency. Good tools show the formula and the assumptions. Weak tools hide the inputs and present a single number as if it were certain.
You should treat every projection as a range, not a target. A 7% average return assumption can produce wildly different outcomes depending on sequence of returns and fees. The calculator cannot model a market crash in year 15 or a plan fee increase in year eight.
Key Takeaway: A deferred compensation calculator is arithmetic, not advice. It projects growth from your assumptions and cannot verify your plan’s compliance or your employer’s stability.
How much can you contribute to deferred compensation in 2026?
The 2026 contribution limit depends entirely on which type of plan you have. A 457(b) plan has a published IRS cap. A nonqualified deferred compensation plan does not.
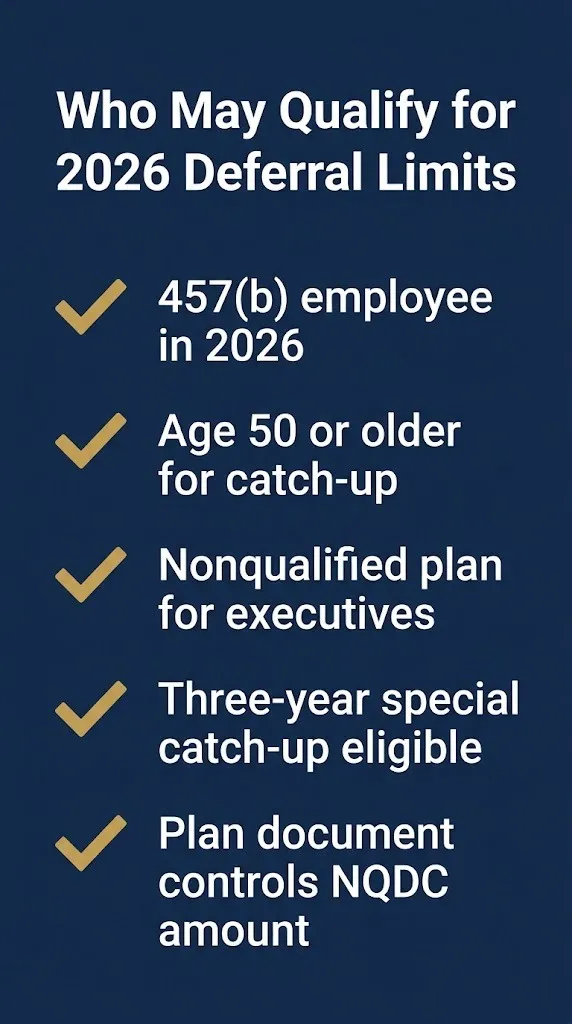
For 457(b) plans, the base employee deferral limit for 2026 is $24,500 . Participants age 50 or older can add an $8,000 catch-up, bringing their ceiling to $32,500 . Governmental 457(b) plans also allow a special catch-up in the three years before normal retirement age, permitting deferrals up to double the annual limit if you have unused deferral capacity from prior years .
Nonqualified deferred compensation plans have no statutory dollar limit under the tax code . The amount you can defer is governed by your plan document and employer policy. This is why executives use them: they can defer far more than the qualified plan caps allow.
| Plan Type | 2026 Employee Limit | Catch-Up Available |
|---|---|---|
| 457(b) governmental | $24,500 | $8,000 age 50+ |
| 457(b) special catch-up | Up to double the limit | Three years before retirement age |
| Nonqualified deferred comp | No statutory cap | Plan document controls |
Key Takeaway: The 2026 457(b) limit is $24,500 with an $8,000 catch-up for age 50 and over. Nonqualified plans have no IRS cap, which is both their appeal and their risk.
What does a deferred compensation calculator actually calculate?
A deferred compensation calculator calculates compound growth on a stream of contributions. That is the entire function. It takes your salary, deferral percentage, employer match, expected return, and years to retirement, then projects a future balance.
The standard formula is iterative. Each year, the calculator adds your deferral and employer match to the prior balance, then applies the expected return rate. The result is a nominal future value, meaning it does not adjust for inflation or taxes at distribution .
Some calculators go further and estimate after-tax payout by applying an assumed tax rate to the projected balance . That is a useful addition, but it is still an estimate. Your actual tax rate at distribution depends on your income in that year, which the calculator cannot know.
What the calculator does not do is more important. It does not model 409A penalties. It does not account for creditor risk if your employer becomes insolvent. It does not warn you that nonqualified deferred compensation is an unfunded promise, not a trust-held asset .
A plain-life comparison: a deferred compensation calculator is like a car’s estimated range display. It tells you how far you can go based on current fuel and average consumption. It does not tell you about the traffic jam ahead or the gas station that closed.
Key Takeaway: Calculators project nominal compound growth from your inputs. They do not model taxes at distribution, 409A penalties, creditor risk, or inflation.
What is the 409A trap that deferred compensation calculators ignore?
The 409A trap is this: if a nonqualified deferred compensation plan fails to comply with Internal Revenue Code Section 409A, all deferred amounts become immediately taxable, plus a 20% additional tax and interest charges . No standard calculator models this scenario.
Section 409A governs the timing of deferral elections, permissible payment events, and distribution schedules for nonqualified plans. The rules are strict. A late deferral election, an impermissible payment trigger, or an incorrect plan amendment can trigger the penalty regime even if the violation was inadvertent .
The penalty applies to the employee, not the employer. If your plan is noncompliant, you owe income tax on all previously deferred amounts, even if you have not received a dollar yet. On top of that, you owe an additional 20% of the deferred amount. Interest accrues from the year the compensation was first deferred .
Here is what a calculator will show you versus what 409A can do:
| Scenario | Calculator Projection | 409A Reality |
|---|---|---|
| $200,000 deferred over 5 years | Grows to projected balance | Immediately taxable in violation year |
| Assumed 7% return | Compounds annually | Return irrelevant to penalty calculation |
| Tax at distribution | Estimated at your future rate | Taxed at current rates plus 20% penalty plus interest |
Key Takeaway: A 409A violation turns deferred compensation into immediately taxable income plus a 20% penalty. No calculator will warn you before you enroll.
How do you use a deferred compensation calculator correctly?
You use a deferred compensation calculator correctly by treating it as a scenario tool, not a prediction. Run multiple scenarios with conservative and optimistic return assumptions. Compare the outputs. The spread between them is your real planning range.
Here are the steps to get a useful projection:
- Enter your actual deferral amount. Use the dollar figure you plan to defer each paycheck or year, not a percentage that changes with raises.
- Verify your employer match. Read your plan document. Some matches have vesting schedules that can forfeit unvested funds if you leave early .
- Use a conservative return assumption. A 5% return is a more cautious planning number than 8%. Run both to see the range.
- Model the years to distribution, not just to retirement. If your plan pays out over 10 years, the balance continues to grow during the payout period in some designs.
- Ignore the single number. Look at the range across scenarios. The midpoint is not a promise.
- Check whether the calculator accounts for taxes. If it does not, discount the output by your expected tax rate at distribution.
Reality Check: No calculator will tell you whether your employer will be solvent when your payout comes due. Nonqualified deferred compensation is an unsecured promise. A rabbi trust can protect you from a change of heart, but not from bankruptcy. If the company fails, your deferred balance may be treated like any other unsecured claim.
What is the difference between 457(b) and nonqualified deferred compensation?
The difference between a 457(b) plan and a nonqualified deferred compensation plan is the difference between a regulated retirement account and a contractual promise. Both defer taxes. They do not share the same protections.
A 457(b) plan is a qualified employer plan under the tax code . It has published contribution limits, and governmental 457(b) assets are generally held in trust for participants. The plan is subject to ERISA fiduciary rules in most cases.
A nonqualified deferred compensation plan is an unfunded arrangement for a select group of management or highly compensated employees . It is not subject to most ERISA protections, including fiduciary rules and funding requirements. The assets remain the employer’s property, subject to the claims of general creditors .
| Feature | 457(b) Governmental | Nonqualified Deferred Comp |
|---|---|---|
| Contribution limit | $24,500 in 2026 | None in tax code |
| Creditor protection | Generally trust-held | Unsecured claim |
| ERISA fiduciary rules | Apply | Generally do not apply |
| 10% early withdrawal penalty | Does not apply | Does not apply |
| 409A penalty risk | Not applicable | 20% plus interest on failure |
Key Takeaway: A 457(b) is a regulated account. A nonqualified plan is a contract with your employer. The creditor risk is the difference most calculators ignore.
What happens next if you are planning around a deferred compensation calculator?
Here is what to do with your projection:
- Now: Check whether your plan is 457(b) or nonqualified. The rules are completely different.
- Before you enroll: Read the plan document for the payment triggers and any forfeiture provisions.
- Before you rely on a projection: Run a second scenario with a return assumption two percentage points lower.
- At distribution: Confirm the withholding rate. Nonqualified deferred comp is often withheld at a flat 22%, which may fall short if your actual bracket is higher .
- If you move states: Research whether your former state can tax the payout. Federal law limits that power for substantially equal periodic payments over 10 years or more .
Frequently Asked Questions
What is a deferred compensation calculator?
A deferred compensation calculator is a tool that projects the future value of deferred salary using compound growth. It takes your contribution rate, employer match, expected return, and time horizon as inputs.
How much can I defer in 2026?
The 457(b) limit is $24,500 for most participants, plus an $8,000 catch-up if you are 50 or older . Nonqualified deferred compensation has no statutory limit. Your plan document controls.
Is deferred compensation taxed when I defer it?
No. Deferral reduces your current taxable income. You pay income tax when the money is distributed. Social Security and Medicare taxes are generally withheld at the time of deferral for nonqualified plans .
What happens if my employer goes bankrupt?
Nonqualified deferred compensation is an unsecured claim. You may recover only a fraction of your balance in bankruptcy. A rabbi trust protects against a change of heart, not insolvency .
Does a deferred compensation calculator include taxes?
Most basic calculators do not. Some estimate after-tax payout by applying an assumed rate, but the result is still an estimate. Your actual rate depends on your income in the distribution year.
What is a 409A violation?
A 409A violation occurs when a nonqualified deferred compensation plan fails to follow the timing and distribution rules in Internal Revenue Code Section 409A. The penalty is immediate taxation, a 20% additional tax, and interest charges .
Can I contribute to both a 457(b) and a 401(k)?
Often yes, if your employer offers both. The 457(b) limit is separate from the 401(k) limit, so you may be able to contribute up to the full employee limit in each plan .
Is the 10% early withdrawal penalty waived for 457(b) plans?
Yes. Governmental 457(b) plans do not impose the 10% early distribution penalty on withdrawals after separation from service, regardless of your age . Ordinary income tax still applies.
The calculator is a starting point, not a guarantee. Check your plan document for the payment triggers, confirm whether your plan is 457(b) or nonqualified, and run a second projection with a lower return assumption. The 2026 457(b) limit of $24,500 is the only number you can rely on without checking your own plan.