Is Workers Compensation Taxable in 2026? The Complete Tax Guide for Injured Workers
Quick Answer
- Workers compensation benefits are not taxable at the federal level under IRS Publication 907.
- Lump sum settlements keep their tax-free status if they replace wages for a work injury.
- Social Security Disability Insurance can become taxable if your combined income crosses IRS thresholds.
Workers compensation benefits are not taxable income. The IRS excludes them from federal income tax under Section 104(a)(1) of the Internal Revenue Code.
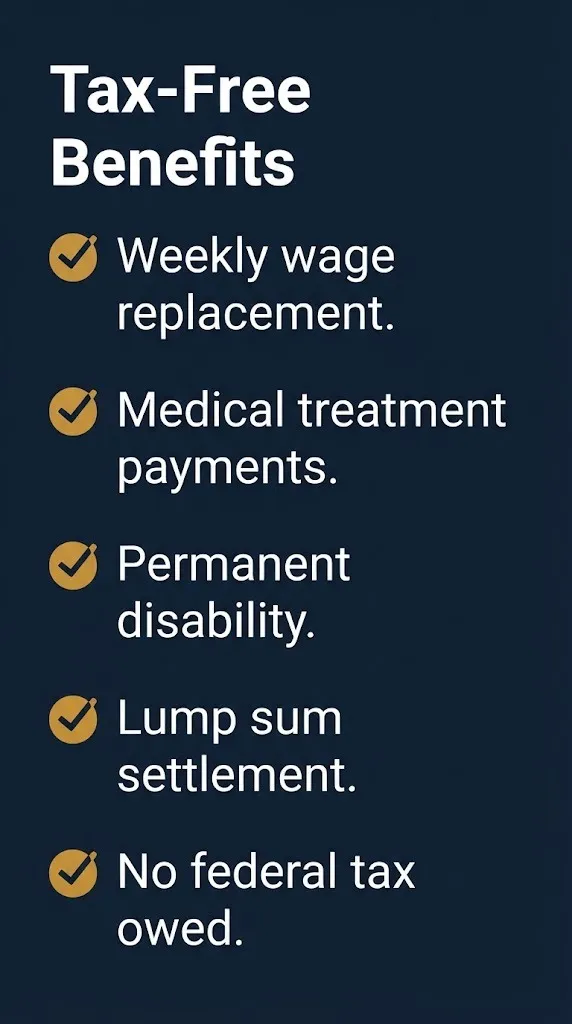
That rule applies to weekly wage replacement checks, medical care payments, and most lump sum settlements. The exclusion has been in place for decades and remains unchanged for 2026.
But the answer gets more complicated when other benefits enter the picture. Social Security, pensions, and certain settlement structures can trigger taxes on part of your money.
This article covers the federal rule, state tax treatment, how lump sums work, when offsets can create surprise tax bills, and what to ask a tax professional before you file.
The Facts
| Item | Details |
|---|---|
| Federal Tax Status | Not taxable |
| IRS Authority | Section 104(a)(1), Publication 907 |
| State Tax Treatment | Not taxable in most states |
| Lump Sum Status | Usually tax-free |
| Social Security Offset | May trigger tax on SSDI |
| 2026 Change | None confirmed |
| Tax Form Required | None for workers comp alone |
Are Workers Compensation Benefits Taxable Income?
No. Workers compensation benefits are not taxable income at the federal level.
The IRS excludes them because they replace wages lost to a work injury, not because of any income earned. The law treats them as compensation for a physical loss, not a paycheck.
This exclusion applies to weekly temporary disability payments, permanent disability payments, and medical care provided under a workers compensation claim.
You do not report these benefits on Form 1040. You do not receive a W-2 or 1099 for them.
Most states follow the federal rule and also exclude workers compensation from state income tax. A few states have no income tax at all, which makes the question moot.
Is Worker Compensation Taxable at the State Level?
No, not in most states. The overwhelming majority of states exclude workers compensation benefits from state income tax.
New Jersey, Pennsylvania, and a handful of others have their own rules, but none currently tax workers compensation benefits as ordinary income.
If you live in a state with no income tax, such as Florida, Texas, or Nevada, the issue never comes up.
If you moved to a new state while receiving benefits, check that state’s tax code. The rule follows your residence, not the state where you were injured.
The state exclusion applies whether you receive weekly checks or a lump sum. State treatment generally mirrors the federal rule.
Is a Workers Compensation Lump Sum Settlement Taxable?
No, a lump sum settlement for a work injury is generally not taxable at the federal level.
The IRS looks at the reason for the payment. If the lump sum replaces wages or compensates for a physical injury, it keeps the Section 104 exclusion.
Here is how different settlement types are treated:
| Settlement Type | Tax Treatment |
|---|---|
| Wage replacement lump sum | Not taxable |
| Medical benefits settlement | Not taxable |
| Permanent disability payout | Not taxable |
| Interest on delayed payment | Taxable |
| Emotional distress only, no physical injury | May be taxable |
| Punitive damages | Taxable |
The key distinction is physical injury. Workers compensation settlements almost always flow from a physical work injury, so the exclusion applies.
What Part of Workers Compensation Is Taxable?
The only commonly taxable parts of a workers compensation claim are interest, punitive damages, and attorney fee structures.
Interest paid because the insurer delayed your benefits is taxable. That interest is income, separate from the underlying benefit.
Punitive damages are rare in workers compensation because the system is no-fault. But if they exist, they are taxable.
Attorney fees can create phantom income in rare settlement structures. Ask your lawyer whether their fee was deducted before or after the settlement amount was fixed.
For the vast majority of injured workers, none of these apply. The weekly check and the medical care are both tax-free.
Key Takeaway: Your core workers compensation benefits are tax-free. Only interest, punitive damages, and unusual fee structures trigger tax.
Does Workers Compensation Affect Social Security Tax?
Workers compensation can reduce your Social Security Disability Insurance benefits through an offset. That offset can indirectly affect your tax bill.
The Social Security Administration reduces SSDI when your combined workers compensation and SSDI exceed 80 percent of your average current earnings before disability.
The offset itself is not a tax. But it changes how much SSDI you receive, and SSDI can be taxable.
Here is the chain reaction:
- You receive workers compensation and SSDI at the same time.
- SSA applies the offset and reduces your SSDI.
- Your reduced SSDI may still be partially taxable.
- Half your SSDI plus other income determines the taxable portion.
- Workers compensation stays tax-free regardless.
This is the most common way injured workers end up owing tax without realizing why.
Are Workers Compensation Benefits Subject to FICA or Medicare Tax?
No. Workers compensation benefits are not subject to FICA, Social Security tax, or Medicare tax.
Your employer does not withhold payroll taxes from workers compensation checks. The checks are not reported on a W-2.
This differs from sick pay or short-term disability paid by your employer. Those payments often are subject to payroll taxes.
The distinction matters at tax time. If your employer paid you sick leave before workers compensation kicked in, that sick pay may be taxable.
How Does Workers Compensation Affect My Tax Return?
Workers compensation generally does not appear on your tax return at all.
You do not enter it as income. You do not attach a schedule. You do not receive a tax form for it.
The only time workers compensation touches your return is when it reduces your Social Security benefits. Your SSA-1099 will show a lower number, and you report that lower number.
If you received interest on a delayed payment, that interest goes on Schedule B. The underlying settlement does not.
Key Takeaway: Workers compensation is invisible on your tax return unless it triggers a Social Security offset or you receive taxable interest.
Is Workers Compensation Taxable If I Return to Work?
No. Workers compensation benefits remain tax-free even if you return to work part-time or full-time.
Your regular wages become taxable again once you return to work. Those wages are reported on your W-2 as usual.
Any partial disability benefits you still receive stay tax-free. The two income streams are treated differently for tax purposes.
This split can confuse employers and payroll companies. Check your pay stub to make sure workers compensation payments are not run through payroll with tax withholding.
Do I Have to Report Workers Compensation on My Tax Return?
No. You do not report workers compensation benefits on your federal tax return.
The IRS does not require a form for these benefits. You do not include them on line 1 as wages or on any other income line.
If a tax preparer asks you to report workers compensation as income, ask why. The preparer may be confusing it with short-term disability or unemployment.
Unemployment benefits are taxable. Workers compensation is not. The two are often confused.
Can Workers Compensation Make My Social Security Benefits Taxable?
Workers compensation itself does not make your Social Security taxable. The offset can.
Here is the real-world example of how it works:
| Scenario | Amount |
|---|---|
| SSDI before offset | $1,800 per month |
| Workers compensation | $1,200 per month |
| Combined | $3,000 per month |
| Pre-disability average earnings | $3,500 per month |
| 80% threshold | $2,800 per month |
| Offset amount | $200 per month |
| Adjusted SSDI | $1,600 per month |
Your taxable income for SSDI purposes is based on the adjusted figure, not the original. The workers compensation remains tax-free.
Reality Check: No IRS rule allows you to deduct workers compensation benefits or claim a credit for them. Anyone selling a “workers comp tax loophole” is selling something that does not exist.
What Is the IRS Rule for Workers Compensation?
The IRS rule comes from Section 104(a)(1) of the Internal Revenue Code. It excludes from gross income any amount received under a workers compensation act as compensation for personal injuries or sickness.
The IRS reinforces this in Publication 907, the tax guide for persons with disabilities.
The rule has been stable for decades. It applies to federal workers compensation under FECA, state workers compensation programs, and longshore and harbor workers compensation.
Railroad workers compensation under the Railroad Retirement Act has different rules. That program may be taxable, unlike state workers compensation.
How Does a Workers Compensation Settlement Affect My Tax Bracket?
A workers compensation settlement should not affect your tax bracket because it is not included in gross income.
The settlement is invisible for purposes of calculating your adjusted gross income, taxable income, and marginal rate.
This differs from a personal injury settlement that includes punitive damages or interest. Those components are taxable and can push you into a higher bracket.
For a pure workers compensation settlement, your tax bracket stays exactly where it would have been without the settlement.
What Records Should I Keep for Workers Compensation Tax Purposes?
You should keep records even though the benefits are not taxable. The IRS may question why your income dropped or why you received large deposits.
Keep your Notice of Benefits, settlement agreement, and any commission orders. These documents prove the payments were workers compensation, not taxable income.
Here is a simple record list:
- Notice of Benefits from the insurer.
- Every commission order or award.
- The signed settlement agreement.
- Bank statements showing the deposits.
- Your SSA-1099 if you also received SSDI.
- Any 1099-INT for interest paid on delayed benefits.
Key Takeaway: Tax-free does not mean record-free. Keep the documents that prove your payments qualify for the exclusion.
What Happens Next
Expected 2026: No changes to the federal workers compensation tax exclusion are pending in Congress.
Ongoing: The IRS updates Publication 907 annually. The 2026 version is expected to keep the same exclusion.
Your move: Review your settlement agreement for interest, punitive damages, or unusual fee language before signing.
Tax filing: Do not report workers compensation as income. Keep records in case of an IRS inquiry.
The tax treatment of workers compensation is one of the clearest rules in the tax code. Your benefits are not taxable, period.
The only wrinkles come from Social Security offsets, interest payments, and rare settlement structures. Know those exceptions and you will not be surprised at tax time.
The 2026 tax year brings no changes to the federal rule. Keep your documents, skip the phantom income, and file with confidence.