Where to Get Workers Compensation Insurance in 2026: Coverage, Costs, and Requirements
Quick Answer
- Workers compensation insurance is available from SECP-registered general insurance companies in Pakistan, including both conventional insurers and Takaful operators.
- Premium rates generally range from 1% to 1.5% of the total wages, salaries, and earnings paid to workers.
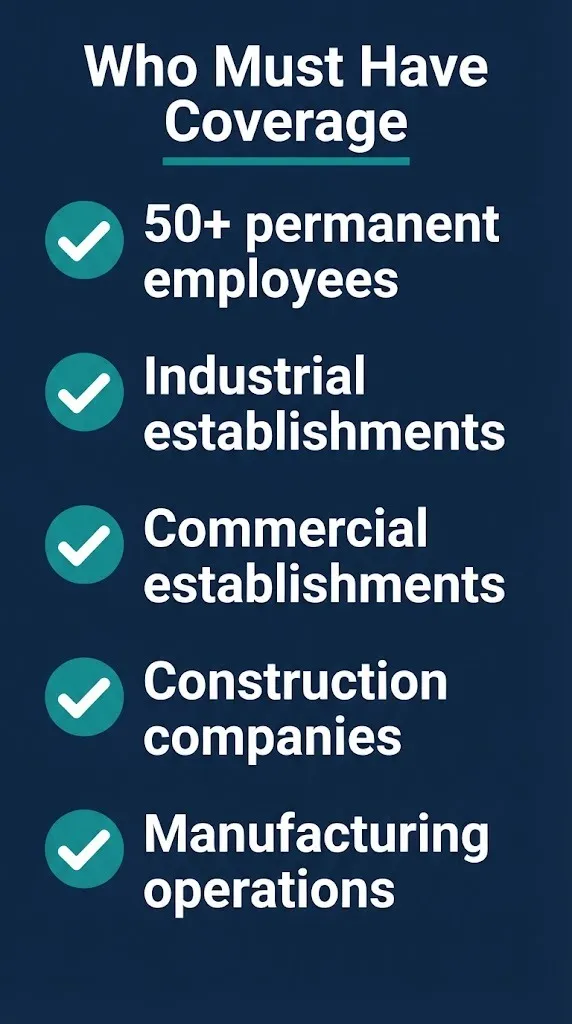
- The policy is required under the Workmen’s Compensation Act 1923 for industrial and commercial establishments with 50 or more employees.
Introduction to Workers Compensation Insurance
Workers compensation insurance is a policy that covers an employer’s legal liability when a worker suffers injury, disability, or death arising out of and in the course of employment. In Pakistan, this coverage is available from private general insurance companies and Takaful operators regulated by the Securities and Exchange Commission of Pakistan (SECP).
If you run a business with employees, you may be legally required to carry this coverage. The Workmen’s Compensation Act 1923 makes employers liable for compensation when workplace accidents cause injury or death. Insurance transfers that financial risk from your business to an insurer.
This article explains where to buy coverage, what it costs, what the law requires, and how to file a claim when a worker gets hurt. One detail that surprises many employers: employees pay nothing toward the premium, and if an employer fails to insure a permanent worker, the employer becomes personally liable for the full compensation amount.
The Facts
| Item | Detail |
|---|---|
| Coverage Type | Workers compensation insurance (also called Workmen’s Compensation or Employer’s Liability) |
| Status | Available from private insurers and Takaful operators in Pakistan |
| Legal Basis | Workmen’s Compensation Act 1923, Provincial Employees’ Social Security Ordinance 1965, Standing Orders Ordinance |
| Who Must Comply | Industrial and commercial establishments with 50 or more employees must insure permanent workers |
| Est. Premium | 1% to 1.5% of total wages, salaries, and other earnings paid to workers |
| Who Pays | Employer pays the full premium. No employee contributions. |
| Where to Buy | SECP-registered general insurance companies and Takaful operators |
| Proof Needed for Claim | Medical examination report, accident notice, proof of employment relationship |
Is Workers Compensation Insurance Legally Required in Pakistan?
Workers compensation insurance is legally required for certain employers in Pakistan, but the mandate is not universal. The Standing Orders Ordinance requires all industrial and commercial establishments with 50 or more employees to insure all permanent workers against natural death, disability, and death or injury arising out of contingencies not covered by the Workmen’s Compensation Act or the Provincial Employees’ Social Security Ordinance .
That means if you run a factory with 50 or more permanent workers, you must carry coverage. If you run a smaller operation, the requirement may not apply, but your liability under the Workmen’s Compensation Act remains.
The Workmen’s Compensation Act 1923 makes every employer liable for compensation when a worker suffers injury by accident “arising out of and in the course of his employment” . That liability exists whether or not you have insurance. Insurance simply gives you a way to pay it without draining your business account.
There’s a key distinction here. The Workmen’s Compensation Act creates the liability. The Standing Orders Ordinance creates the insurance mandate for larger employers. Small businesses may not face the insurance requirement, but they still face the liability.
Key Takeaway: If you have 50 or more permanent workers, insurance is mandatory. If you have fewer, you still face liability under the Workmen’s Compensation Act, but the insurance mandate may not apply.
How Much Does Workers Compensation Insurance Cost in Pakistan?
Workers compensation insurance in Pakistan typically costs between 1% and 1.5% of your total annual payroll for covered workers. That range comes from a 2021 study of insurance premium rates in Pakistan .
A real policy example from August 2026 shows the range in practice. Universal Builders & Engineers paid Rs. 13,810 in gross premium for a policy with a sum insured of Rs. 433,010. That works out to roughly 3.2% of the sum insured. Another policy for Mohammad Ayub Electric Service carried a Rs. 1,560 premium against a Rs. 180,000 sum insured, or about 0.87% .
The variation comes from several factors:
| Factor | Impact on Premium |
|---|---|
| Industry risk level | Construction and manufacturing pay more than offices |
| Total payroll | Higher wage bills mean higher premiums |
| Claims history | Past claims raise future premiums |
| Number of workers | More workers mean more exposure |
| Job classifications | Higher-risk roles cost more to insure |
The premium is calculated as a percentage of the total wages, salaries, and other earnings paid to all covered workers. You declare your estimated annual payroll when you buy the policy. At the end of the policy period, you reconcile actual wages paid and pay any difference.
For a business with a Rs. 5 million annual payroll, the premium would run roughly Rs. 50,000 to Rs. 75,000 per year. That’s a small price compared to the potential compensation payout if a worker dies or becomes permanently disabled.
Where Can You Buy Workers Compensation Insurance?
You can buy workers compensation insurance directly from SECP-registered general insurance companies and Takaful operators in Pakistan. These are private companies, not government agencies.
Here are the main providers that offer this coverage:
| Provider | Type | Notes |
|---|---|---|
| UBL Insurers | Conventional | Offers Workmen Compensation Takaful certificates |
| Salaam Takaful | Takaful | Has dedicated Workmen’s Compensation proposal forms |
| Reliance Insurance | Conventional | Lists Workmen Compensation as a product offering |
| Other SECP-registered insurers | Both | Most general insurers offer this coverage |
The process works like this. You contact an insurer or broker, fill out a proposal form declaring your business type and estimated payroll, and the insurer quotes a premium rate. If you accept, the policy is issued and you pay the premium.
Salaam Takaful’s proposal form shows what insurers ask for. You must include all persons employed. You declare your total wages and salaries for the past twelve months. You state whether you want coverage for contractors and subcontractors’ workers as well .
You can also work through an insurance broker who will compare quotes from multiple insurers. That’s often faster than contacting each company separately.
What Does Workers Compensation Insurance Cover?
Workers compensation insurance covers four main categories of work injury under Pakistani law. The coverage tracks the compensation categories in the Workmen’s Compensation Act and the Provincial Employees’ Social Security Ordinance .
| Category | What It Covers |
|---|---|
| Temporary Incapacity | Worker is unable to work for a limited period |
| Permanent Partial Incapacity | Worker loses some earning capacity permanently |
| Permanent Total Incapacity | Worker cannot work at all permanently |
| Fatal Injury | Worker dies from workplace accident or occupational disease |
For temporary disability, the benefit is 60% of average wages (100% in Punjab and Sindh) paid after a 3-day waiting period, for up to 180 days .
For permanent total incapacity, compensation is 75% of the worker’s average earnings over the previous 12 months. In Punjab, that rises to 100% of previous average wages .
For fatal injury, dependents receive a survivors’ grant of Rs. 200,000 under the Workmen’s Compensation Act. A widow receives 60% of the deceased worker’s monthly pension. Minor children receive 20%, and full orphans receive 40% .
The policy typically excludes certain events: terrorist acts, war, nuclear events, and malicious acts by the policyholder. Those exclusions are standard in the commercial contract used for this coverage .
How Do You File a Workers Compensation Claim?
Filing a workers compensation claim requires prompt notice and a medical examination. The process protects both the worker and the employer by creating a documented record.
Here are the steps:
- Worker gives notice of the accident to the employer as soon as practicable.
- Employer arranges a free medical examination within three days of the notice .
- Employer notifies the insurer of the claim and submits required documents.
- Insurer reviews the claim against policy terms and coverage limits.
- Medical report determines the nature and extent of injury or disability.
- Compensation is calculated based on the disability category and wage rate.
- Payment is made either directly or through the Commissioner for Workmen’s Compensation.
If a worker refuses medical examination, their right to compensation is suspended during the refusal . That’s a critical rule for both sides to understand.
Disputes about liability, amount, duration, or the nature of disablement go to the Commissioner for Workmen’s Compensation. Civil courts do not have jurisdiction in these matters .
What Are the Deadlines for Workers Compensation Claims?
The deadline for filing a workers compensation claim is generally three years from the date of the accident, or three years from the date of death in fatal cases .
For injury benefit claims under the Provincial Employees’ Social Security scheme, the timeline is much shorter. The claim must be made within seven days of the first certificate of incapacity from an authorized medical practitioner. The institution may accept late claims within three months if there were reasonable grounds for the delay .
For survivor’s pension, the claim must be made within fifteen days of death, with the same three-month extension possible .
Missing the three-year deadline for a Workmen’s Compensation Act claim usually means losing the right to compensation entirely. The seven-day and fifteen-day deadlines for Social Security benefits are shorter but have built-in flexibility for reasonable delays.
What Happens If an Employer Doesn’t Have Workers Compensation Insurance?
If an employer fails to insure a permanent worker as required, the employer becomes personally liable for the full compensation amount. The law places that obligation directly on the employer, not on any insurer .
That means if a worker dies or is permanently disabled and the employer had no policy, the employer must pay the survivors’ grant, pension, or lump sum compensation from business assets or personal funds. For a fatal claim, that could mean Rs. 200,000 or more in immediate payments plus ongoing pension obligations.
The requirement applies to industrial and commercial establishments with 50 or more employees. For smaller employers, the insurance mandate doesn’t apply, but the liability under the Workmen’s Compensation Act still does. A small business owner who chooses not to buy coverage is self-insuring, whether they realize it or not.
The premium is the employer’s responsibility entirely. Employees make no contributions. That’s a key difference from social security schemes, where contributions may be shared.
What Happens Next with Workers Compensation Requirements?
The regulatory framework continues to evolve at the provincial level. Here are the key developments to watch:
Ongoing 2026: Provincial labor departments continue implementing the Punjab Labour Code 2025 and similar reforms in other provinces.
Expected 2026-2027: SECP and provincial labor departments may update compliance guidance for smaller employers.
Ongoing: The ILO continues working with Sindh province to strengthen employment injury insurance systems .
Ongoing: Courts continue hearing disputes over coverage, liability, and compensation amounts.
The core requirement is not likely to change. If you have employees, you have liability. The question is whether you transfer that risk to an insurer or carry it yourself.
Frequently Asked Questions
Is workers compensation insurance mandatory in Pakistan?
It’s mandatory for industrial and commercial establishments with 50 or more employees to insure permanent workers. Smaller employers face liability under the Workmen’s Compensation Act but may not face the insurance mandate.
How much does workers compensation insurance cost?
Premiums typically range from 1% to 1.5% of total annual payroll. The exact rate depends on your industry, claims history, and the number of workers covered.
Where can I buy workers compensation insurance in Pakistan?
You can buy it from SECP-registered general insurance companies like UBL Insurers, Salaam Takaful, and Reliance Insurance. Insurance brokers can also help you compare quotes.
Do employees contribute to workers compensation premiums?
No. The employer pays the full premium. Employees make no contributions to workers compensation insurance.
What benefits does workers compensation insurance cover?
It covers temporary incapacity, permanent partial incapacity, permanent total incapacity, and fatal injury. Benefits include wage replacement, lump sum compensation, and survivors’ pensions.
What happens if I don’t have workers compensation insurance?
If you’re required to have it and don’t, you become personally liable for the full compensation amount. That could include lump sum payments and ongoing pension obligations to survivors.
How long do I have to file a workers compensation claim?
The general deadline is three years from the accident or death. Social Security injury benefit claims must be filed within seven days of the first medical certificate, with a possible three-month extension.
Who resolves disputes about workers compensation claims?
The Commissioner for Workmen’s Compensation handles disputes about liability, amount, duration, and the nature of disablement. Civil courts do not have jurisdiction in these matters.